Author: SwiftCargo Team

  • Skilled Visa Settlement Patterns: Where Freight Demand Appears

    Skilled Visa Settlement Patterns: Where Freight Demand Appears

    The headline numbers are easy to find: 190,000 permanent places in the 2023–24 Migration Program, 137,100 of them skilled, and hundreds of thousands more temporary employer-sponsored visas active at any one time. What those totals hide is geography. Skilled migrants in Australia do not all move to Sydney. Most end up exactly where the visa structure told them to go. State nomination sends them to Adelaide and Perth. Regional sponsorship sends them to Ballarat and Toowoomba. Employer-sponsored visas track to wherever the sponsor operates. The freight demand that follows spreads unevenly in a way the headline number conceals.

    If a logistics planner reads only the national migration figure, they get the timing right and the geography wrong, which is the same as getting it wrong. The visa programme is a logistics signal disguised as immigration policy.
    Skilled Visa Settlement Patterns: Where Freight Demand Appears

    Visa structure and freight geography

    Australia’s SkillSelect system operates through expression of interest rounds. Nomination thresholds, occupation ceilings, and age cutoffs all vary by state. The design is deliberately regional. The federal government has used the program since 2012 to direct skilled migrants away from Sydney and Melbourne and toward states with specific workforce shortages.

    Settlement patterns are therefore structured, not random. South Australia’s State/Territory Nominated category delivered 2,647 places in 2023-24. A cohort on that scale produces a predictable cluster of new households in and around Adelaide. A Western Australia occupation list that opens an engineering or healthcare category produces a Perth cluster on the same logic. Logistics businesses that treat Australia as one uniform demand zone miss these clusters entirely.

    Household moves, personal effects consignments, and relocation support follow the settlement geography the visa structure creates.
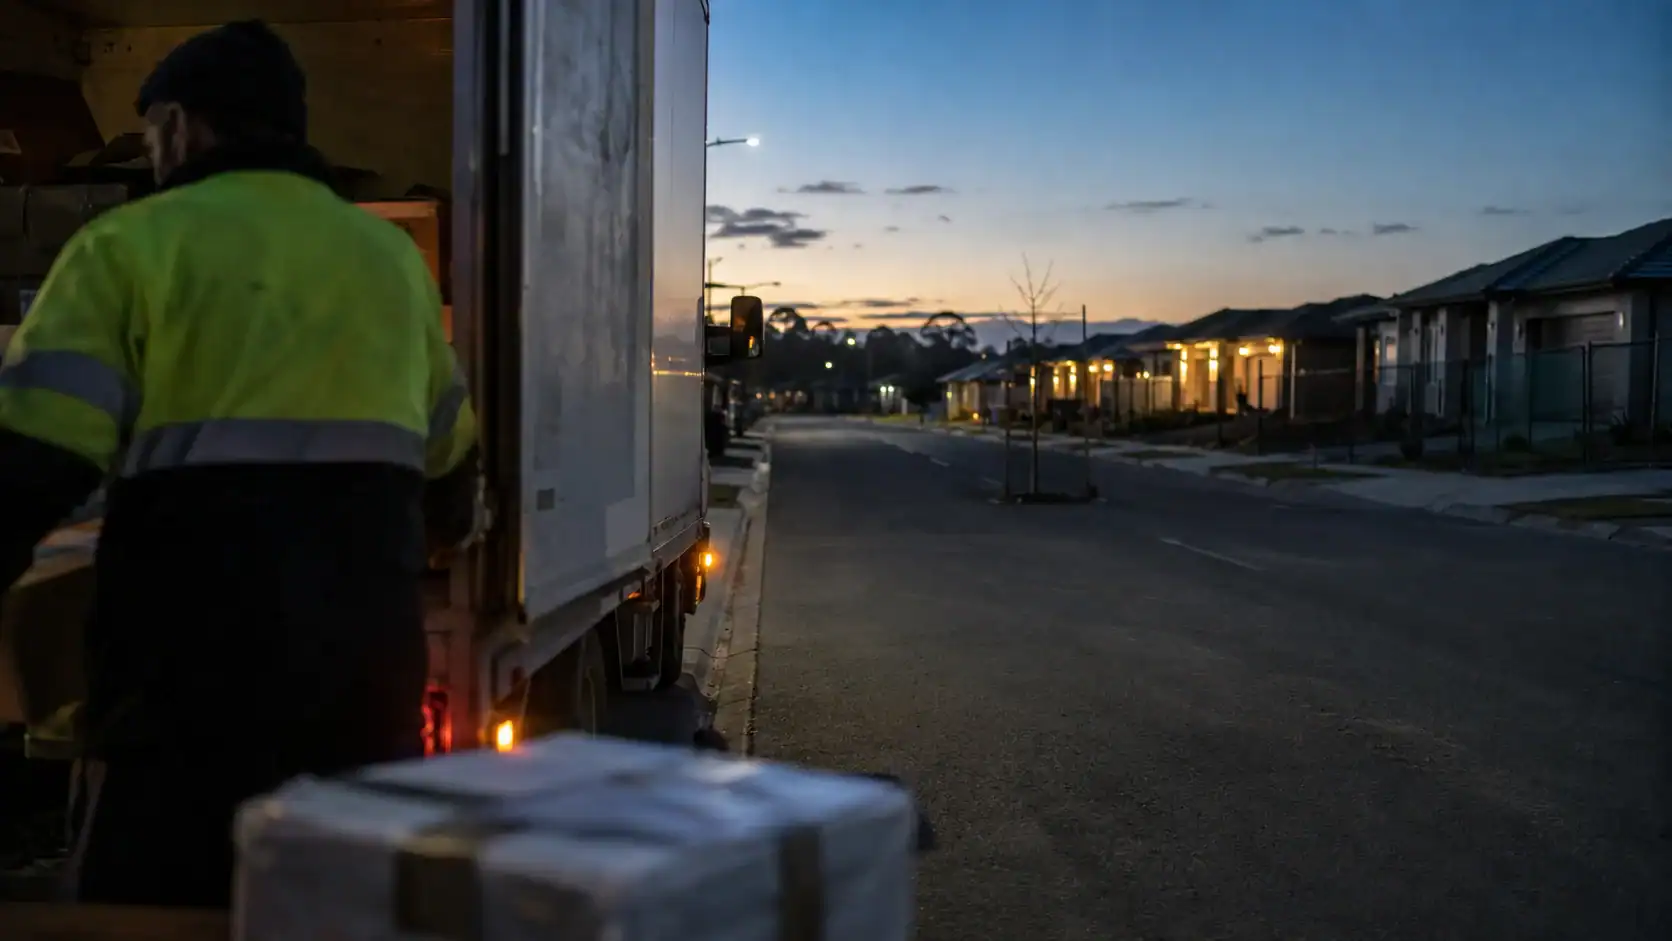
    Delivery driver in high-visibility workwear unloading a crate from a truck on a new-build Australian suburban street at dusk

    State nomination programs and their settlement effects

    The main skilled migration pathways that drive settlement patterns are the Skilled Nominated visa (subclass 190) and the Skilled Work Regional visa (subclass 491). Both require state or territory nomination. The 190 is permanent from the day of grant, though nominating states ask holders to live there for the first two years. A 491 holder can apply for the Permanent Residence (Skilled Regional) visa (subclass 191) after holding the 491 for at least three years in a regional area.

    The commitment periods matter for freight demand. A 190 holder arriving in South Australia will likely have household goods follow within 6–18 months of arrival. A 491 holder settling in a regional area such as Townsville, Geelong, or Darwin will have a similar household arrival profile but a different port and inland delivery requirement. Geelong is close enough to Melbourne port that the inland leg is manageable. Townsville is a different calculation.

    Picture the arithmetic from the receiving end. A container bound for a 491 holder in Ballarat comes off a ship at Melbourne, clears, and then travels a little over an hour northwest on the Western Freeway to a town that has been quietly absorbing regional-nomination families for years. The nurse or engineer who filled that container chose Ballarat because a nomination pointed there, not because a shipping line did. By the time the truck turns into the driveway, the visa decision made eighteen months earlier has become a physical thing: a pallet-load of a life, set down in a place the national migration totals never named.

    According to the Home Affairs migration program report for 2023–24, the state breakdown for skilled stream visas was led by Victoria and NSW but with allocation shifts toward South Australia, Western Australia, and Queensland compared to five years earlier. The distribution shifts every program year as state quotas are renegotiated.

    The employer-sponsored category (subclass 482 and 186) follows a different logic. Settlement tracks to the sponsor’s location. When a mining company sponsors engineers to Western Australia, those engineers arrive at Perth. When aged-care providers sponsor workers in Queensland, the demand follows that corridor. State economies have different sector compositions: mining in WA, agriculture and professional services in SA, construction in Queensland. Those compositions map fairly directly onto which origin countries and which household freight profiles are likely to follow.

    Which cohorts move full households

    Not all skilled migrants move full households, and the distinction matters for estimating freight volume against settlement data.

    The cohorts most likely to ship significant household goods are professionals arriving from established relocation source markets: the UK, Germany, South Africa, India (middle and senior managerial), and Southeast Asia returning expats. These arrivals tend to have 15–35 CBM of household contents, which requires LCL sea freight for smaller volumes and a 20ft container for larger moves.

    The cohorts least likely to ship in bulk are arrivals under working-holiday pathways, international students transitioning to permanent residence (they have been living in Australia for years already), and arrivals from origin markets where sending household goods by air in multiple small shipments is standard practice. These arrivals may generate demand for household goods biosecurity inspection when items do arrive, but the volumes are lower per consignment.

    The visa type does not determine household volume directly, but it correlates with arrival profile, income level at destination, and likelihood of sponsored family migration. Sponsored family migration is often the trigger for the full household shipment. A 482 holder who arrived solo will often ship household goods only once the partner and children follow, typically 6–24 months after initial arrival.
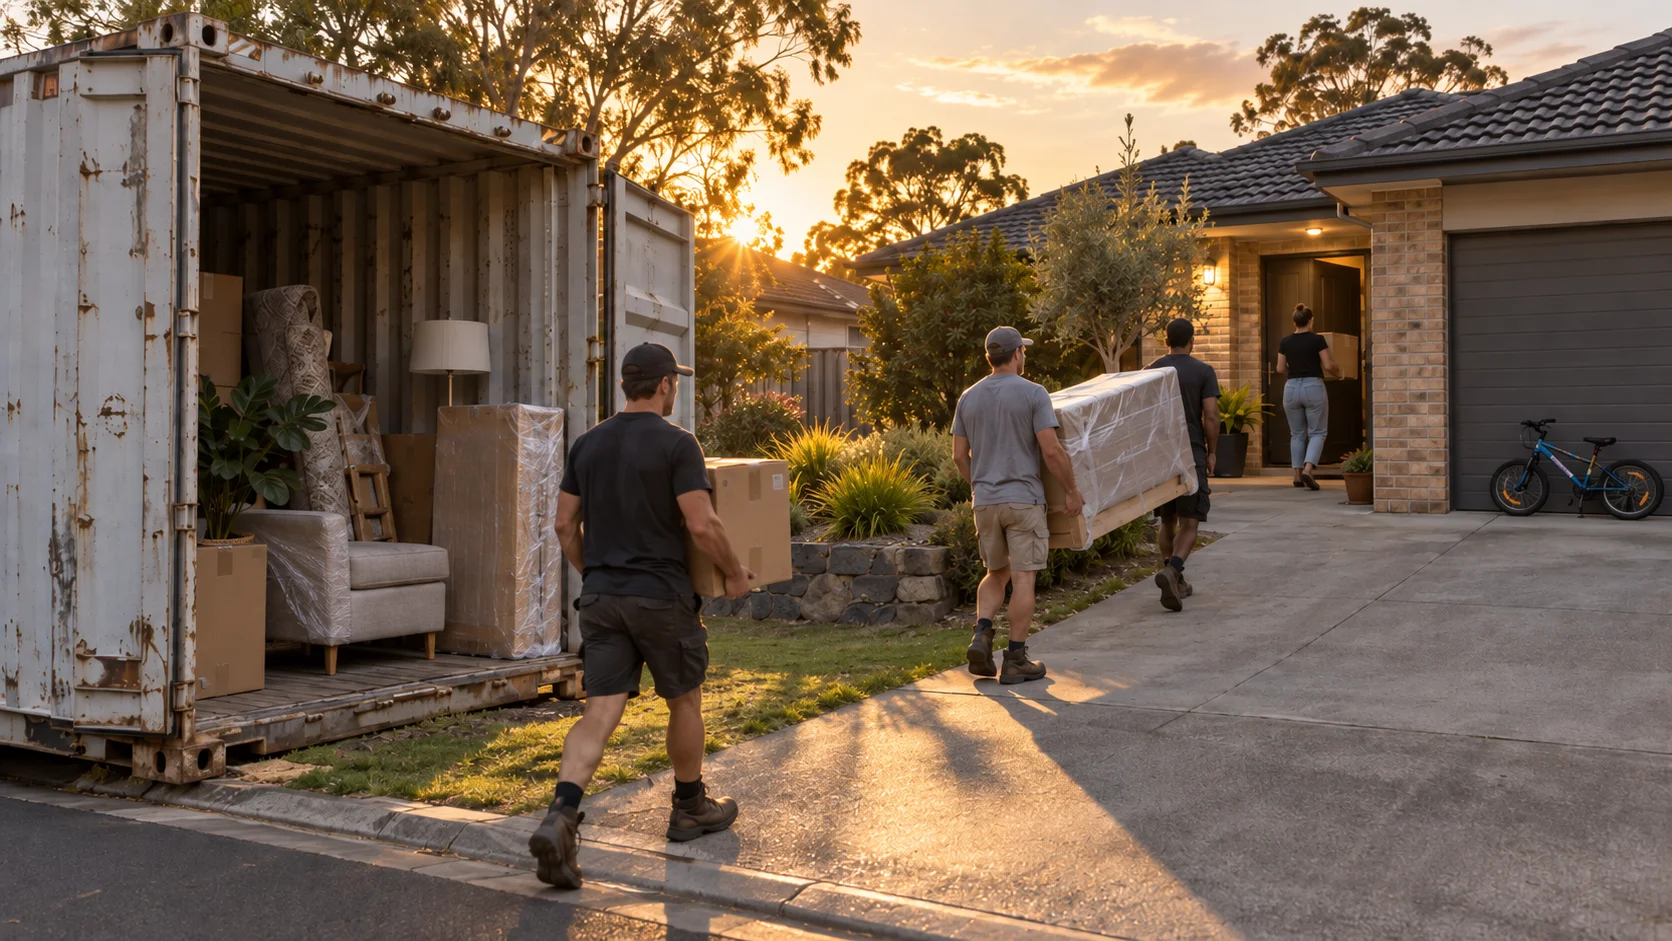
    Shipping container sits open at the kerb outside a suburban Australian home

    Origin country patterns and freight corridors

    The origin country mix of skilled migrants matters because it determines which shipping corridors carry the freight load and what the typical consignment profile looks like.

    India is consistently the largest source country for skilled migrants under the permanent program. Home Affairs data records 45,820 Skill stream places for Indian citizens in 2023–24. Indian arrivals tend to ship household goods by sea, often from Chennai or Mumbai, with a mix of LCL consignments and full container moves for larger families. The Melbourne and Sydney corridors absorb most of this volume, though Perth has grown as Indian employer-sponsored arrivals in the resources sector increase.

    The UK remains a significant source, particularly for 190 and employer-sponsored arrivals in professional services and healthcare. UK-to-Australia moves are typically full-container or near-full-container moves. UK households are large, and UK movers are experienced in international relocation. The freight corridor is direct sea freight, typically via Felixstowe or Southampton to Sydney, Melbourne, or Adelaide.

    South Africa produces consistent demand on the Perth corridor, driven by the longstanding SA migration community in Perth and ongoing employer-sponsored arrivals in mining and engineering. South African moves often include vehicles, which adds complexity to the consignment and biosecurity inspection requirements.

    China and the Philippines are significant sources for temporary employer-sponsored visas (482), but they produce lower average household freight volume per arrival than the UK or South Africa cohorts. Two things explain that: the more recent arrival profiles, and the fact that many arrivals have already established a household in Australia through earlier visa stages.

    How settlement patterns become a logistics signal

    Translating migration data into a freight signal takes two steps: identifying where the settlement is going, and estimating the lag between visa grant and household arrival.

    The ABS overseas migration series and Home Affairs visa statistics both publish settlement data. Both carry a 12-month publication lag, so the data available now describes what happened 12 months ago. The forward signal comes from watching nomination quota announcements and occupation list changes, which precede actual arrivals by 18–36 months.

    The lag between visa grant and household goods arrival ranges from 3 to 18 months and varies by origin country and family status. Migrants arriving solo under temporary visas often wait until permanent residence is granted or until family migration is approved before shipping household goods. Arrivals under 190 or 186 (permanent from day one) tend to ship sooner, often within 6 months of settling into a property.

    Confidence layers in migration data

    National net-migration totals: high confidence. The ABS overseas migration series reports quarterly. The direction holds for 12–24 months and is reliable enough for medium-range planning.

    State-level settlement splits by visa category: medium confidence. Home Affairs publishes cohort data with a one-year lag, and the split shifts when policy changes. Regional nomination quotas have changed twice in the last five years. The state-level picture is directionally useful but not precise for quarter-specific planning.

    Quarter-specific city-level demand timing: low confidence. The three-to-eighteen-month grant-to-arrival gap already noted is too wide to pin demand to a particular quarter, and it varies by origin country and family status. An operator who treats all three layers as equally reliable ends up overconfident on timing and underprepared for geographic variance. The appropriate response is not more data. It is a clearer view of which layer is driving the planning decision.
    Logistics manager beside a regional map pinned with clustered colour markers

    What strong operators do with this information

    Strong operators align route focus, service readiness, and capacity planning around where migrants are actually going rather than where the business vaguely hopes demand will appear.

    In practical terms, this means tracking state nomination quota announcements (published each program year by Home Affairs), watching ABS regional population data for settlement trend confirmation, and building partner relationships in second-tier cities (the Adelaide, Perth, and Brisbane corridors) rather than assuming all volume funnels through Sydney and Melbourne port infrastructure.

    For incoming shipments to Australia, the relevant operational questions include timing against biosecurity inspection requirements and inland delivery to the actual settlement destination, which is often not the port city. A consignment arriving at Port of Melbourne for a migrant settling in Geelong has a different inland leg than one destined for Carlton. Settlement data makes that inland planning more honest.

    The gap compounds when a settlement cluster is discharge-side invisible. A state-nominated cohort settling in the Adelaide Hills, for instance, still clears at the same South Australian port as an Adelaide-CBD shipment on paper, but the actual last-mile leg runs materially longer and carries different access constraints for a large container than an inner-city delivery does. An operator planning capacity purely off port-level throughput sees no difference between those two consignments; an operator planning off settlement data sees the inland-leg gap coming months in advance, while there’s still time to price it and staff for it rather than absorb it as an unplanned cost on delivery day.

    For quotes and cost estimates on Australian inbound shipments, the Australian shipping cost overview provides current volume thresholds and price ranges by origin. For the full customs and biosecurity process, the Australian shipping process guide covers documentation requirements, inspection timelines, and port options.

    Settlement pattern data is only useful if it connects to a specific operational question. The ABS migration series, the Home Affairs visa grant breakdown, and the state-and-territory population release each answer a different question at a different level of resolution and lag. The ABS quarterly migration total answers “how many,” with a 12-month lag. The Home Affairs state breakdown answers “where,” with a 12–18 month lag. The nomination quota announcements, which precede arrivals by 18–36 months, answer “where it is going.” Using all three as if they answer the same question produces confident forecasts on the wrong time horizon. The correct use is sequential: quota announcements shape 2–3 year capacity planning; settlement data confirms or corrects 12-month corridor assumptions; current booking patterns calibrate the immediate quarter. The discipline is holding those three layers apart rather than collapsing them into a single “migration is strong” summary. A logistics business that manages that has what it needs to decide where to build capacity before the freight pressure appears.

    Related reading: An Itemized Quote Shows What an Australian Freight Forwarder Handles

    Frequently Asked Questions

    Why do skilled visa programs matter to logistics businesses?

    Because they determine where migrants settle, and settlement patterns shape relocation and freight demand. A national visa total tells you volume; state-level settlement data tells you geography.

    Does state nomination affect where freight demand appears?

    Yes. State nomination directs migrants to specific states, and the 2–3 year commitment periods mean those migrants will generate household freight demand in that state rather than in Sydney or Melbourne. The effect is predictable and observable in ABS data.

    Why is settlement data more useful than national migration headlines?

    Because it translates migration into actual geographic demand. National figures tell you the Australian market is growing. Settlement data tells you which ports, cities, and delivery corridors to prioritise.

    What is the biggest planning mistake with migration data?

    Treating demand as nationally uniform. Skilled migrant settlement is structured by visa design. It clusters in predictable locations based on nomination, employer, and regional program mechanics.

    How long is the lag between visa grant and household goods arrival?

    Typically 3–18 months, varying by visa type, family status, and origin country. Permanent residence visa holders (190, 186) ship sooner. Temporary visa holders (482) often wait until permanent residence is approved or family migration follows.
  • Exporting Animal Products from Australia: DAFF Certification and Market Access

    Exporting Animal Products from Australia: DAFF Certification and Market Access

    Animal-product exports are the kind of trade many people underestimate because the goods do not look exotic. Wool, leather, pet food, hides, skins, and related by-products can all seem commercially ordinary. But controlled export systems do not treat them casually. These goods often move through structured certification frameworks because destination markets care about sanitary status, origin, product category, and documentary confidence.

    That is why this category should not be treated as ordinary freight with a few extra papers attached. For many animal-product exports, the documentary pathway is part of the commercial product. If the product is defined incorrectly, if the wrong official route is assumed, or if destination-market expectations are not built into the job early enough, the shipment can become physically movable and still commercially weak.

    Exporting Animal Products from Australia: DAFF Certification and Market Access

    Why Animal-Product Exports Are Documentation-Heavy by Design

    These categories attract heavier documentation because the importing market is rarely assessing freight risk alone. It is also assessing sanitary confidence, product identity, origin, and whether the goods fit a recognised official pathway. That is why wool, leather, pet food, hides, and similar products can carry more control logic than a casual exporter expects.

    The documentary burden is not arbitrary. If a destination market is concerned about disease status, product classification, or commodity treatment, the official file becomes part of how that risk is managed. The shipment only moves cleanly when the documents support the category the importer thinks it is buying and the regulator thinks it is admitting.

    The freight leg may be straightforward, but the paperwork is not secondary. It is what keeps the freight leg commercially valid.

    Why the Category Is Broader Than Many Exporters Expect

    Exporters get caught here because “animal products” is a broader and more regulated category than it sounds. It can include raw and processed materials, by-products, treated goods, finished pet consumables, and products that sit close to veterinary, sanitary, or commodity-control logic.

    The exporter has to understand the category logic used by the control system, not just the commercial product description. If those two frames diverge, the file becomes unstable. A business may describe a product one way for marketing or invoicing while the export-control pathway treats it as something more sensitive, more specific, or more conditional.

    That is especially relevant in mixed or borderline categories such as processed animal-derived goods, value-added wool or leather products, and pet-food items that may appear straightforward commercially but still carry official requirements in practice.

    How Australian Certification Systems Matter

    Australia’s export systems create the official route by which controlled goods can be documented and accepted internationally. DAFF’s export documentation and controlled-goods frameworks are not optional polish layered on after the sale. They are part of the infrastructure that makes the trade commercially real, as DAFF: Export Documentation and DAFF: Controlled Goods both set out.

    A destination market often wants more than a commercial invoice and packing list. It may want an official certificate, commodity-specific declarations, or evidence that the product sits inside the correct sanitary or export-control channel. If the exporter has not mapped that pathway, the shipment can reach the booking stage before anyone realises the official side is still incomplete.

    Exporters should treat documentation systems as operating systems rather than admin tasks. Once the document route is clear, the exporter can plan with confidence instead of rediscovering the pathway every time a buyer places an order.

    The document sequence on a controlled animal-product export is fixed: commodity definition, DAFF controlled-goods registration, export certificate request, inspection sequence, health certificate or sanitary declaration, and the market-access conditions document for the destination country. Each piece precedes the next. The goods travel after the file is complete, not while the file is being assembled.

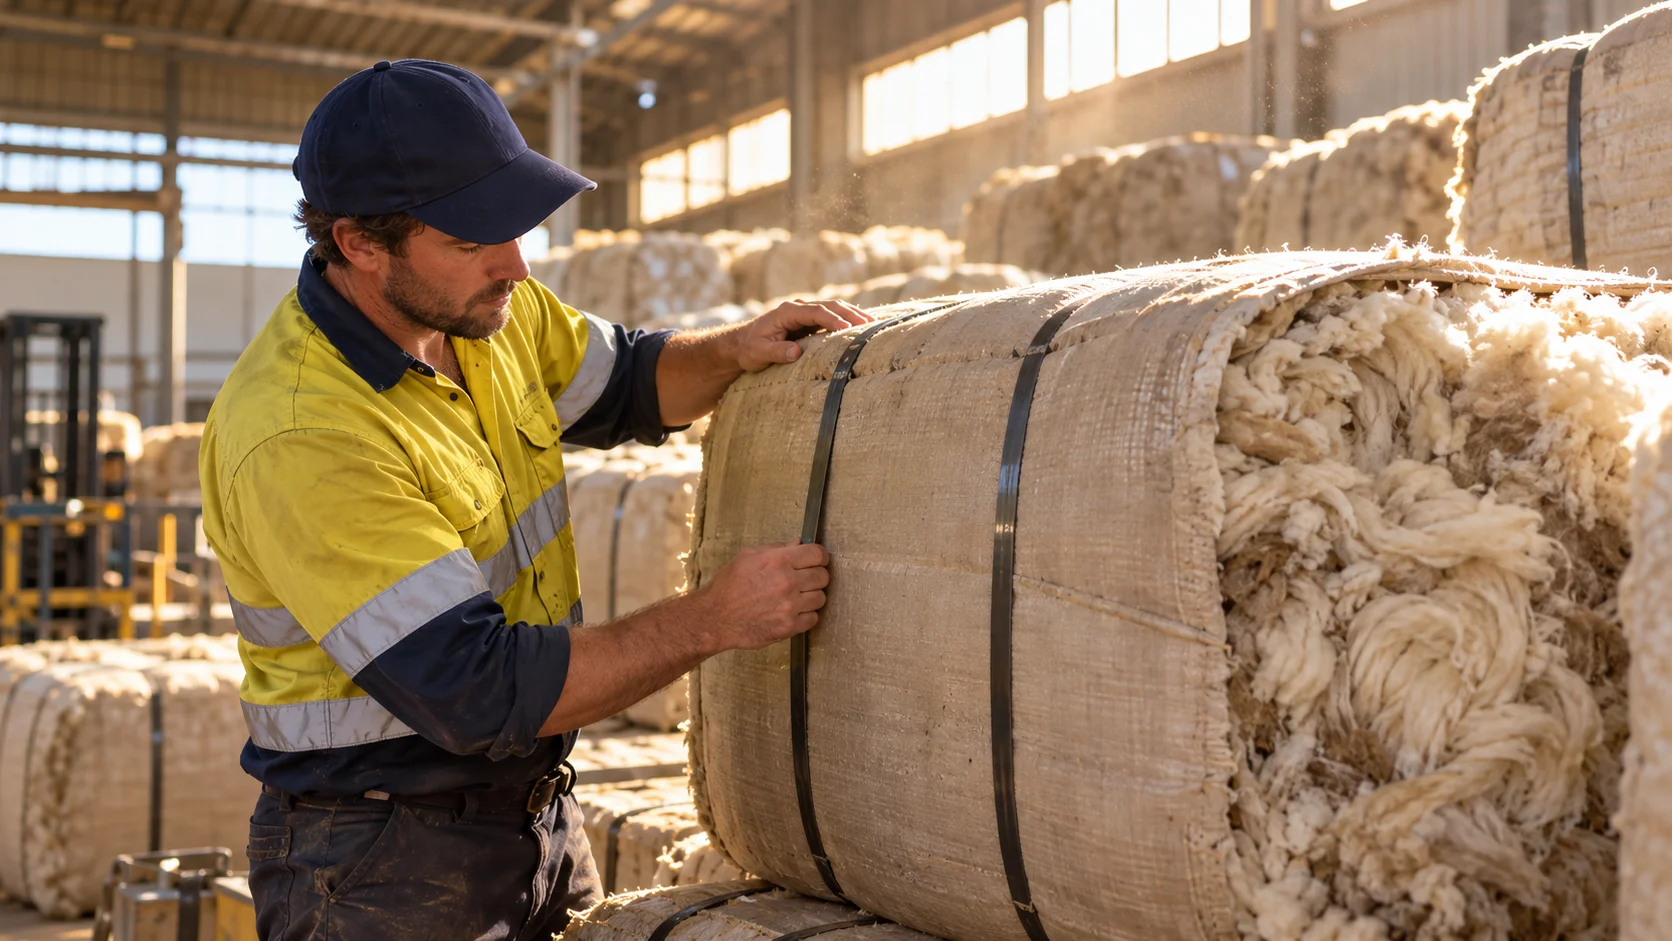
    In an Australian wool-handling facility, a worker checks a compressed wool bale's binding straps before it's stacked with several others, the bale's natural

    Why Market Requirements Still Control the Outcome

    Australian systems are only half the story. The destination market still decides what it will accept, and that means importing-country requirements have to shape the export design. A certificate that looks valid in the abstract is not enough if it does not match the destination’s conditions for that product.

    Strong exporters start with destination acceptance logic and work backward through the Australian framework. They ask what the buyer’s market requires, what category the product will sit in, what official document path supports that category, and how the shipment needs to be prepared so the pathway remains credible from origin to destination.

    Timing matters here too. If a market expects a certain declaration, treatment, or document sequence, the freight booking cannot lead the job. Exporters have to understand the official pathway early enough that the export plan does not trap the team in a weak position later.

    For Australian exporters shipping to destination markets with specific biosecurity conditions, the relevant processes are documented on the Swift Cargo Australia customs and export guide.

    What Good Exporters Do Differently

    Good exporters in these categories are disciplined in three ways. They define the commodity correctly, they confirm the documentary route before the goods move, and they treat controlled export work as a market-access process wearing a logistics uniform.

    A wool exporter who gets the certification pathway wrong does not find out at the port. They find out three weeks later, in an email from the importing country’s own inspector, after the goods have already been sitting in a bonded facility accumulating storage fees on a shipment that was never going to clear. That is the actual cost of treating certification as paperwork instead of as the product. The exporters who never receive that email are not luckier. They confirmed the documentary route before the goods moved, not after, and the ten extra minutes it took at the planning stage is the cheapest insurance in this entire guide.

    • They define the commodity before they define the shipment. If the product category is unclear, the logistics plan is premature.
    • They confirm the official pathway before committing to timing. A booking is not progress if the certificate route is still uncertain.
    • They build documents around the destination market, not around habit. Repeat templates are useful only if they still match the lane and commodity.
    • They treat repeatability as a capability. The goal is not just to get one shipment through. It is to build a process that can survive the next shipment too.
    • They communicate constraints early. Buyers and internal teams do better when the exporter surfaces the control logic before rushing the freight forward.

    That mindset reduces rework, rejection risk, and the kind of delay that turns a viable shipment into a weak commercial outcome. Buyers do not only want one successful consignment. They want confidence that the next one will move with the same discipline. Some exporters build process memory around commodity definition, document logic, and lane-specific controls. That creates a quieter but real advantage over competitors who are still improvising each file.

    Readers who need the detailed certificate framework should continue to Export Certification and Phytosanitary Requirements.

    On a clean stainless packing line inside a pet food processing facility.

    What the Requirements Actually Look Like: Wool, Leather, and Pet Food

    The abstract point becomes concrete the moment you look at three of the most common animal-product exports, because each one carries a different documentary shape.

    Wool. Greasy and scoured wool are not the same export problem. Buyers in many markets expect a National Wool Declaration covering mulesing status and, increasingly, dark-and-medullated-fibre risk, alongside standard commercial documents. The packaging matters too: timber dunnage and pallets have to meet ISPM 15 heat-treatment marking, or the consignment can be held at the destination for a wood-packaging breach that has nothing to do with the wool itself. This is the same phytosanitary logic that governs Australian fresh-produce exports, applied to a different commodity.

    Leather and hides. A raw salted hide, a wet-blue, and a finished leather good move under different rules. Raw and semi-processed hides are far more sanitary-sensitive and usually require a health certificate confirming the animals passed ante- and post-mortem inspection. Finished leather is often treated more like a manufactured good. Exotic skins such as crocodile add a CITES permit layer on top of the sanitary file. The entire pathway depends on which of these three the product actually is.

    Pet food. Exporters are caught here more often than anywhere else. Pet food commonly requires the manufacturing establishment itself to be DAFF-registered for export, plus an importing-country health certificate that matches that market’s exact wording. China requires the facility to hold GACC registration before a single carton ships; the EU requires product from an approved establishment entering through a designated Border Control Post with TRACES-NT documentation. None of this is discoverable at the booking stage. It is a months-ahead facility-and-market question, not a freight question.

    A pallet of finished leather goods sits precisely wrapped at a warehouse's export staging point, corner protectors perfectly aligned at each edge.

    How the Best Exporters Run This vs How Most Do

    Most exporters in this category work forward from the product they already make: they have wool, or hides, or a pet-food line, and they go looking for a buyer. The certification then becomes paperwork to be sorted once the order lands. The best exporters work backward from the destination market’s admissibility rules, and they do the discovery before they promise a ship date. That single reversal is what separates a lane that runs cleanly from one that stalls at the certificate stage.

    The best teams also treat the first successful shipment as a prototype, not a finish line. They capture exactly which commodity definition worked, which certificate template the destination regulator accepted, and which inspection sequence the consignment passed. The second and tenth shipments are then reproductions, not fresh improvisations. It is the same discipline good product teams use: learn the requirement deeply once, then build a repeatable process around it rather than rediscovering it under deadline pressure every quarter.

    And they manage the commercial layer with the same care as the documentary one. Two things move the margin as much as a freight quote does: the day an export invoice is struck, and the rate at which it converts. That is why disciplined exporters watch why the day of export matters for exchange-rate exposure rather than leaving it to chance. Getting the certificate right keeps the shipment legal; getting the timing right keeps it profitable.

    A missing certificate is not bad luck. It is a planning failure that surfaced late, at the worst possible moment, in front of a customer waiting on a ship date. Nobody at the border cares whose job it was to confirm the destination market’s admissibility rules. The shipment is stopped either way. The exporters who never get caught out assign a single person to own the certification chain for each commodity line, end to end, before the first order is quoted. That person tracks which regulator, which template, which inspection window, and reports back the moment anything is uncertain, instead of assuming someone else already checked. Certification discipline is not a compliance department’s job to clean up afterward. It belongs to whoever is closest to the shipment, and it starts before the sale, not after the ship date is promised.

    Related reading: DAFF and FSANZ Enforce Separate Rules for Importing Food to Australia

    Frequently Asked Questions

    Are wool, leather, and pet food exports treated as ordinary freight?

    Not usually. These goods often depend on certification, controlled-export pathways, or destination-market requirements that go beyond ordinary freight paperwork.

    Why do animal-product exports require so much documentation?

    Because destination markets often want sanitary, origin, or commodity-specific assurance before they accept the goods.

    Can exporters rely on generic commercial invoices alone?

    Often not. The official pathway depends on the product category, the destination market’s conditions, and whether the right export documentation has been prepared.

    What is the biggest mistake in this category?

    Underestimating how much the certification system and category definition shape whether the shipment can move cleanly.

    Does pet food require special registration to export from Australia?

    Commonly yes. Many markets require the manufacturing establishment itself to be DAFF-registered for export and the consignment to carry an importing-country health certificate. Some markets go further. China requires GACC facility registration, and the EU requires product from an approved establishment entering through a designated Border Control Post. It is a facility-and-market question to resolve months ahead, not at booking.

    How far ahead should I confirm animal-product export requirements?

    Before you promise a ship date. Commodity definition, establishment registration, and destination health-certificate wording can take weeks to months to put in place, and none of it is discoverable at the freight-booking stage. Working backward from the destination market’s admissibility rules early is what keeps the lane from stalling at the certificate stage.

  • Australia Export Certification: The Market-Access Logic

    Australia Export Certification: The Market-Access Logic

    Export certification sounds administrative until a shipment is delayed, rejected, or stripped of commercial value because the importing country’s conditions were not met. That is why exporters should think about certification as a market-access system rather than as a paperwork exercise.

    For Australian exporters, the core question is not just whether the goods exist and can be moved. The real question is whether the shipment can be accepted at destination under the importing country’s official requirements. If the certificate pathway, inspection logic, and freight plan do not line up, the cargo can be physically mobile and still commercially blocked.

    This matters most with plant goods and plant products, where phytosanitary controls sit directly inside market access. But the broader lesson applies to controlled exports more generally. Documentation is not a layer that sits on top of the shipment after the real work is done. It is part of the shipment design.

    Australia Export Certification: The Market-Access Logic

    Why Export Certification Is Really a Market-Access Problem

    Many exporters learn this lesson too late. They assume the commercial sale is the hard part and the certificate work is an administrative tail-end task. In reality, the certificate pathway often decides whether the sale can be completed.

    That is because official documentation is not generic. It has to match the importing country’s conditions. A certificate may be technically issued and still misaligned with destination requirements. That mismatch leaves the goods stuck, rejected, or delayed. The exporter can feel as if the shipment is “ready” when the market-access side is still unfinished.

    That is why the best framing is simple: export certification is part of market design. It tells you whether the lane is commercially viable, whether the cargo needs inspection or official treatment, and whether the documents will support entry at the other end. Treating it as paperwork leads to weak execution because the exporter builds the freight plan before the access logic is stable.

    For Australia-based exporters, official certification interacts with DAFF systems, controlled-goods pathways, and the destination country’s own requirements. For consignments bound for ASEAN markets, the AANZFTA preference framework adds an origin-certification layer that must align with the phytosanitary pathway. That is a chain, not a checklist.

    Why Phytosanitary Requirements Matter So Much

    Phytosanitary requirements matter because plant and plant-product trade is governed by risk control, not by transport willingness. Cargo can be packed, booked, and moved. None of that says whether a destination country will allow it in.

    Importing countries want official assurance that relevant plant goods meet their plant-health conditions. Phytosanitary certificates carry that assurance. The certificate is not ceremonial. It is evidence inside a destination-country risk framework, set out in DAFF: Plant Export Certification.

    Many exporters underestimate how early they need to plan here. If the goods need inspection, treatment, sampling, specific declarations, or a precise description format, those details cannot always be repaired after packing and booking are already underway. The shipment design needs to reflect the certificate logic early enough for the pathway to remain credible.

    How Certification and Country Rules Interact

    The exporter has to understand two things at once. First, what Australia can certify. Second, what the destination country actually requires. Those are related questions, but they are not identical.

    MICoR earns its place here: it records importing-country requirements and the conditions attached to different goods and markets. That matters because a certificate is only commercially useful if it matches the conditions controlling entry at destination.

    In practical terms, that means documentation, inspection, commodity preparation, and freight timing all need to be read together. If the destination expects a certain inspection sequence or official assurance and the exporter builds the freight plan first, the job becomes fragile. A shipment can move physically while the compliance side remains unresolved.

    Destination rules need to shape the plan upstream, not arrive late as a compliance surprise after the goods are already committed to a lane.

    That timing point is more important than it looks. If inspections, certificate issuance, supporting declarations, or authority checks need to happen in a certain order, then the freight booking cannot be treated as the master plan. In many export workflows, the certificate sequence is what makes the booking viable in the first place. When exporters reverse that logic, they create urgency where none was needed and lose control over the job.

    A packing shed for agricultural export goods, crates of produce checked by a quality officer's hands before sealing, natural warehouse light with a cooler shadow toward

    What the Certificate Actually Certifies

    “Certification” in the abstract hides how specific the machinery is, so it is worth being concrete about the paperwork. A job-to-be-done framing makes the point: the exporter is not really buying a document, but hiring a certificate to unlock one importing country’s border rule. The consignment may be entirely genuine. If the certificate does not match that specific rule, it has not done the job it was hired for.

    For most Australian agricultural exports the Department of Agriculture, Fisheries and Forestry issues the phytosanitary certificate under the Export Control Act 2020. The EXDOC system generates it once the goods meet the destination’s declared conditions. Those conditions are not guesswork: the department maintains the Manual of Importing Country Requirements (MICoR), which records what each market demands. The certificate has to align with that wording rather than a generic template.

    Wood packaging adds a second layer. ISPM 15 requires timber pallets and dunnage to be heat-treated or fumigated and stamped with the international mark. A missing or unreadable stamp can hold an otherwise-compliant consignment at the border.

    The most common failure is not fraud or contamination; it is a certificate that describes the shipment accurately but does not match the exact form of words the destination lodged with the IPPC.

    Why Documentation Quality Decides Smoothness

    Export failures are often blamed on regulation in the abstract, but the deeper cause is usually one of three things: requirement mismatch, weak documentation quality, or poor sequencing. None of those problems are glamorous. All of them are expensive.

    A weak file can damage a perfectly saleable shipment. Product details may be described too loosely. Certificate assumptions may not match the commodity or the destination. Supporting records may be incomplete. An inspection step may be mistimed. The problem is not that regulators love friction. The problem is that the file no longer gives the destination market the assurance it expects.

    This is why exporters have to treat documentation quality as a commercial discipline. Good exporters do not simply gather papers. They build a file that supports the real destination pathway.

    • They verify the market and commodity requirement set early.
    • They check whether the required official wording, declarations, or inspection steps are clear before the cargo is locked in.
    • They avoid treating certificate requests as generic admin requests detached from the lane.
    • They make sure freight timing does not undermine the inspection or document sequence.

    Repeat exporters gain an advantage here. Once the team has seen how a market behaves, they can start building repeatable documentation habits instead of reinventing the file each time. That reduces delay risk and makes it easier to spot when a new consignment is drifting away from the conditions that made the prior one work.

    An export coordinator reviewing a wall-mounted production schedule (content implied, not readable) in an office overlooking a packing floor visible through a large

    What Strong Exporters Do Differently

    Strong exporters work backwards from destination acceptance. They identify the market’s import conditions, confirm the certificate pathway, prepare the goods to satisfy that pathway, and only then finalise the logistics plan. That sequence sounds basic, but it separates serious operators from hopeful ones.

    In practice, the better workflow usually looks like this.

    • Start with the destination rule set. The question is not “what documents do we usually ship with?” It is “what does this market require for this product?”
    • Confirm the official certification pathway. Make sure the certificate that can be issued actually supports the destination requirement.
    • Prepare the cargo around the certificate logic. Inspection, treatment, packing, and timing should not undermine the official pathway.
    • Build the freight plan after the compliance path is credible. Transport speed is useless if the market-access side is weak.
    • Protect repeatability. The strongest exporters do not just get one shipment through. They build a process that can survive the next shipment too.

    Buyers and partners see operator quality here too. An exporter who understands certification as part of market access is easier to trust than one who talks about paperwork only after a problem appears.

    Consider the chronology of how a single export-certification failure unfolds at the Australian end. A South Australian grape consignment leaves Adelaide on a Tuesday morning. By Wednesday afternoon the importer in Shanghai notes a discrepancy on the phytosanitary certificate: the variety listed in box 9 does not match the variety listed on the commercial invoice. By Thursday, the consignment is held at the Chinese port. By Friday, the Australian exporter has been notified, has called the original phytosanitary inspector, and is requesting a replacement certificate. By the following Monday, the consignment is being re-routed, downgraded, or destroyed.

    Each step in that chronology was preventable at the previous step. The certificate discrepancy was a typing error a week earlier. The variety mismatch existed on the documents three days before departure. The cost of catching it on Tuesday morning was zero. The cost of catching it on the following Monday was the entire margin on the consignment. The certificate is not the safeguard. The internal documentation review is. Exporters who run that review as a non-negotiable pre-departure step pay almost nothing for it. Exporters who skip it sometimes pay everything.

    The Recordkeeping Trail Regulators Actually Follow

    Every phytosanitary certificate DAFF issues sits on top of a documentation trail, and that trail is what regulators go looking for when a pattern of rejections starts to form. Under the Export Control Act 2020, established exporters do not necessarily submit fresh paperwork for every shipment. Many operate under what DAFF calls an Approved Arrangement. This standing accreditation lets a business self-certify defined export functions inside a documented quality system that DAFF audits periodically. Those functions include inspection, packing, and labelling. The arrangement replaces one-off government sign-off on every consignment.

    The distinction is bigger than it sounds. An exporter without an Approved Arrangement is, in effect, asking a DAFF officer to verify every shipment from first principles. An exporter who has earned one is trusted to run the process itself. DAFF then checks the paperwork behind the system rather than the produce in front of it.

    That trust is not free. Earning it requires a demonstrated quality system, trained staff, and records that hold up months after the ship has sailed. That last requirement is the one exporters underestimate until an audit finds it. The certificate that leaves the country with the cargo is a summary. The file that stays behind is the evidence, and it is the file DAFF actually pulls when a pattern of rejections, not a single mistake, triggers a review. Exporters who treat that standing file as an afterthought are the ones who eventually lose the arrangement. Exporters who make one honest error on a variety code rarely do. DAFF’s own audit logic is built to catch systems breaking down, not shipments that had one bad day.

    Why a Paper Certificate Is Becoming the Slow Option

    Why does one Australian consignment clear a foreign port on the day it lands, while an identical one from the same packer waits a week for a courier envelope? Increasingly the answer is the format of the certificate rather than its content. The International Plant Protection Convention runs an electronic exchange, the IPPC ePhyto Solution, through which national plant protection organisations send phytosanitary certificates to each other directly. DAFF participates: for a growing list of destination markets, the certificate generated at the Australian end travels as data to the importing authority rather than as a stamped original in the shipper’s document pouch.

    The practical difference shows up at the moment something goes wrong. A typing error on a paper original, like the grape-variety mismatch above, means a replacement certificate has to be issued, couriered and presented, and the consignment sits until it arrives. An electronic certificate can be reissued and re-sent the same day. The same discipline applies to the HS code and commodity description on the invoice, which the destination authority reads side by side with the certificate. Whether a market accepts ePhyto at all is itself an importing-country requirement, recorded market by market in MICoR, and that is where the question belongs. The form the market wants, and how fast a certificate can be corrected, decide the real exposure. For a perishable load, the second answer can be worth more than the freight rate.

    Exporters looking at commodity-specific certification should continue to Exporting Animal Products from Australia. For lane design and regional market logic, Shipping Timeline to Australia covers how the inbound leg is sequenced. For Australian customs requirements on inbound shipments, Swift Cargo’s Australian customs guide covers what goods face on arrival.

    Frequently Asked Questions

    What is a phytosanitary certificate?

    It is an official certificate used to show that plant or plant-product goods meet the relevant plant-health requirements of the destination market.

    Why does export certification matter so much?

    Because many markets will not accept goods unless the official documentation and certificate pathway match their import conditions.

    Can exporters treat certification as a final admin step?

    That is risky. Certification logic should shape the export plan before the shipment is booked, not after the logistics side is already committed.

    What is the biggest export mistake here?

    Moving the cargo plan ahead of the destination-country compliance pathway and assuming the documentation can always be repaired later.

  • Shipment Timing Changes Customs Costs in Australia

    Shipment Timing Changes Customs Costs in Australia

    Importers often talk about shipment timing as if it were only a lead-time question. They ask when the goods will leave, when they will arrive, and whether stock will land before the deadline. In Australia, that is only part of the story. Shipment timing can also become a valuation issue because customs conversion rules can make costs depend on specific dates.

    That is why the logistics calendar is not just an operational calendar. For some imports, it is part of landed-cost design. A team that watches only the arrival date can miss the date that actually matters for customs valuation. A finance team can feel comfortable with the treasury-side rate while the customs-side outcome still moves against them. The result is not usually a legal mystery. It is a coordination failure.

    Shipment Timing Changes Customs Costs in Australia

    Why Shipment Timing Is a Cost Variable, Not Just a Logistics Variable

    Most logistics discussions focus on service performance. Will the goods arrive in time? Can the supplier release on schedule? Does the warehouse have enough buffer? Those are real questions, but they do not exhaust the timing issue.

    In Australia, border valuation requires foreign-currency values to be converted into AUD under official rules. ABF: Exchange Rates That requirement turns shipment timing into a cost variable. Once that is understood, timing stops being just a service-level concern and becomes part of import-cost planning.

    This matters most when teams assume all important dates are commercially intuitive. They usually are not. Finance may care about invoice date or payment date. Logistics may focus on sail date or ETA. Procurement may anchor on supplier readiness. Customs valuation can hinge on a different date altogether. If those assumptions drift apart, the importer can feel sure they understand cost exposure while still watching the wrong clock.

    That is why importers need to treat the phrase “shipment timing” more carefully. It is not only about speed. It is about which moment in the chain carries the monetary consequence.

    How Customs Timing Enters the Import File

    Separate commercial dates from customs dates. Commercial teams build plans around the dates that help them run the job. Customs uses the dates that matter inside the legal valuation framework. Those are not always the same thing.

    Australia’s border rules on customs value and exchange-rate conversion spell out the basic mechanism. Imported goods valued in foreign currency need to be converted into AUD using the customs framework, not whatever internal reference point the business happens to prefer. ABF: Customs Value Customs Act 1901

    That is where shipment timing enters the file. If the shipment moves on one date rather than another, the customs outcome can change even when the supplier price never changed. The logistics calendar therefore becomes a border-cost variable rather than a neutral transport detail.

    Importers with tight margins, frequent shipments, or volatile currency conditions have the most at stake. A small conversion change may be tolerable on one consignment and commercially material across a larger purchasing cycle. Importers working through this can find current customs requirements at Swift Cargo: Australian customs procedures.

    Why Timing Mistakes Happen So Easily

    These mistakes happen because the work is fragmented. The freight team is trying to keep cargo moving. Finance wants cost visibility. Procurement wants supplier execution. Customs wants a legally sound valuation basis. Each group is rational inside its own lane, but the importer still loses if nobody reconciles the lanes.

    Landed-cost surprises therefore often feel avoidable in hindsight. They usually come from ordinary coordination gaps, not from exotic legal traps.

    • The finance team watches one exchange-rate assumption while customs uses another timing basis.
    • The logistics team changes movement timing without realizing it may change the cost outcome.
    • The procurement team locks in a purchase decision without checking whether shipment flexibility still exists.
    • No one clarifies which date will actually matter if the FX environment moves before export.

    This is one reason importers should be wary of oversimplified advice. The topic is hard because several teams can be technically competent and still misalign around the one date that matters, not because the rule is conceptually impossible.

    Why Strong Operators Treat Timing as Integrated

    The strongest importers treat timing as an integrated planning issue rather than as a late-stage customs clean-up task. They model the likely customs effect while the goods are still being planned, not after the freight is committed and the commercial flexibility has mostly disappeared.

    That changes behavior. A team that understands the customs timing rule is less likely to confuse a favorable commercial FX rate with a favorable border outcome. It is more likely to ask whether the shipment schedule still has room to move. It is also more likely to communicate landed-cost uncertainty before someone downstream treats an early estimate as a fixed truth.

    This does not mean every shipment needs elaborate modeling. It means the importer should know when timing matters enough to warrant attention. Coordination pays off more with high-value consignments, margin-sensitive products, volatile FX periods, and frequent import programs.

    Strong operators also understand that timing interacts with other cost layers. Duty, GST, freight timing, and customs conversion do not sit in separate universes. If the business wants a realistic landed-cost view, it needs to read those layers together rather than one at a time.

    The Exchange Rate You Can Actually Choose

    Most importers hold two beliefs about currency at the same time. The first is that exchange rates matter enormously to their landed cost. The second is that there is nothing to be done about them short of becoming a hedging desk. Both feel true, and together they produce a kind of learned passivity: the rate is treated like weather.

    The customs conversion mechanism contradicts this. The valuation rate is anchored to a specific, rule-defined date. An importer who controls the export date therefore partly controls which rate applies, without a forward contract, without an options desk, without any financial product at all. The lever is operational, not financial. It sits in the shipping schedule, which the importer already manages for other reasons.

    That inverts the usual assumption about where currency decisions live. The finance team watches the rate it cannot control, while the operations team controls a rate it never watches. The importers who benefit from the mechanism simply noticed that the lever was on the other desk.

    Finance, procurement, logistics and customs teams each tracking a different date, converging on one shipment file

    How to Use This Without Overcomplicating the Job

    The practical fix is simpler than the topic sounds. Importers do not need to build a grand FX doctrine. They need a better pre-shipment checklist.

    • Identify the governing customs timing issue early. Do not wait until the file is in motion to ask which date affects the conversion outcome.
    • Align finance, procurement, logistics, and customs assumptions. If each team is watching a different date, the budget is already at risk.
    • Translate the timing issue into landed-cost impact. The team should know whether the customs difference is trivial, tolerable, or worth planning around.
    • Decide whether timing flexibility is commercially worth preserving. Some shipments justify speed over precision. Others do not.
    • Communicate the uncertainty honestly. Do not present a tentative cost assumption as a locked result if timing can still change it.

    That last point matters more than many teams expect. A budget can be directionally correct and still be operationally misleading if the timing assumption underneath it has not been settled. This is why good operators prefer conditional language early in the shipment cycle rather than false precision. They would rather explain that the customs-side outcome still depends on the governing timing point than reassure stakeholders with a number that may not survive the actual export sequence.

    Thinking in terms of materiality also helps. Not every customs timing difference will justify changing the shipment plan. Some will be too small to matter. Others will be large enough that preserving timing flexibility becomes commercially sensible. The job is to know when the timing rule deserves real attention, not to chase perfection.

    A perceptual trick explains why teams keep watching the wrong date. An arrival date feels concrete: the day the goods appear, the day the customer is satisfied, the day the story ends. The mind therefore files it as the date that matters. The export date feels like a formality already behind you. Yet the formality fixes the valuation rate, and the vivid date fixes nothing. People reliably overweight the moment they can picture and underweight the moment that actually prices the shipment. Noticing that inversion is most of the discipline.

    This page works best as a bridge between freight planning and the more specific customs-valuation pages. Readers who want to see how currency swings have moved import costs over a full cycle should move next to AUD Peak to Volatility 2013-2020: Import Planning Lessons. Readers trying to connect timing to actual border charges should continue to Australian Import Landed Cost: The 8 Layers Quotes Leave Out. Readers who still think in service-level timing only should also read Shipping Timeline to Australia.

    That reading path matters because the real question is rarely “what is the rule?” It is usually “what should we now do differently with the shipment, the budget, or the explanation to stakeholders?” The cluster is stronger when this page makes that next step obvious.

    Who Actually Owns the Export-Date Number in Your Business

    Most importers who get caught out by this rule are not confused about how it works. They have simply never assigned anyone to watch it. Three functions touch a shipment before it clears customs, and none of them treats the export date as their number to track. For each one, it genuinely is not.

    The buyer negotiates price and locks a quote. Their job ends at the purchase order. The freight forwarder books the vessel and confirms the actual sailing date. Their job ends at the bill of lading. The customs broker lodges the entry using whatever exchange rate applies on the day the goods are exported. But the broker’s job only starts once the shipment is already at the border, and they had no part in choosing that rate. Everyone owns a piece of the shipment. Nobody owns the number that decides what it costs.

    The fix is not a new system. It is a named owner. Pick one person: the buyer, a finance team member, or whoever already builds the landed-cost estimate. Give them a single job in the two weeks before departure: check the AUD exchange rate on the date the booking confirms sailing, not the date the original quote was locked. If the rate has moved by more than a point or two against the assumption the quote was built on, that person flags it before the entry is lodged with the broker, not after the duty invoice lands on someone’s desk. On a shipment where duty and GST together run to several thousand dollars, a two-cent move in the AUD rate often separates a landed-cost estimate that holds from one that quietly misses by a few hundred dollars nobody budgeted for.

    The best-run import operations treat customs FX exposure as a discovery problem with an obvious owner, not as something that happens to them between departments. That owner checks the exposure at the one moment it can still be acted on: before the booking confirms, not after the invoice arrives and the number is already fixed.

    Frequently Asked Questions

    Why does shipment timing affect customs costs in Australia?

    Imported goods valued in foreign currency are converted into AUD under official customs rules. The timing basis behind that conversion can change the cost result.

    Is arrival date always the most important date for customs valuation?

    No. Importers often over-focus on arrival date when the customs framework may be concerned with another date inside the valuation process.

    What usually causes mistakes on this issue?

    Mistakes usually come from misalignment between finance, procurement, logistics, and customs assumptions. Different teams watch different dates and assume they are all talking about the same cost basis.

    What is the practical fix?

    Model the customs timing issue before the shipment is locked in, align the internal teams on the relevant date, and decide whether timing flexibility is commercially worth preserving.

  • Choosing an Australian Container Port: The Inland Freight Logic

    Choosing an Australian Container Port: The Inland Freight Logic

    Importers often choose an Australian port the way tourists choose an airport: by looking at the city name they recognise first. That is understandable, but it is not how serious cargo planning works.

    Australia’s main container ports are not interchangeable. Each gateway sits inside a different operational environment, with different throughput realities, inland connections, customer catchments, and congestion implications. The vessel may arrive successfully in all cases, but what happens after discharge can vary materially depending on where the cargo enters the country.

    That is why importers have to ask the “best port” question more precisely. Best for which destination, with which delivery deadline, via which inland route? An importer shipping perishables to Brisbane faces different gateway logic than one moving heavy machinery to a Perth construction site.

    For many importers, port choice is really a delivery-system choice in disguise.

    Choosing an Australian Container Port: The Inland Freight Logic

    Why Port Choice Matters More Than Many Importers Expect

    Importers new to Australia often over-focus on the sea leg, because ocean transit feels like the dramatic part of the move. But in practice, a large share of the friction sits after the ship arrives: terminal handling, slot availability, trucking, warehousing, rail, and the distance between the port and the real destination of the goods.

    So a gateway can look efficient in headline terms and still be wrong for the shipment. If the cargo lands in the biggest port but then has to travel inefficiently across the country, the importer may win the ocean map and lose the actual delivery plan.

    Australia makes this more important than some other markets because it is both large and concentrated. Population, warehousing, and business activity cluster heavily around a few states and metropolitan corridors, while the inland distances between those corridors remain commercially meaningful. A gateway decision is therefore not only a maritime decision. It is a national distribution decision.

    BITRE’s Waterline reporting exists precisely because port performance, container throughput, and landside efficiency matter at a system level. Raw container counts matter less than how that throughput translates into performance and cost for the importers using those gateways.

    How Australia’s Main Container Gateways Differ

    Melbourne is the obvious place to start because it is the country’s largest container port. Port of Melbourne publishes container statistics showing how central it remains to national trade. That scale matters because it creates route density and broad shipping relevance, especially for south-eastern demand. But “largest” is not the same as “best for everyone.” Choosing Melbourne out of habit rather than logic can still make a Queensland or Western Australia delivery less efficient.

    Sydney / Port Botany is another core gateway because it serves the country’s largest metropolitan economy and a major warehousing and consumption corridor. Beyond city size, Port Botany plugs directly into a large eastern-seaboard commercial base. For cargo bound for Sydney and its surrounding logistics network, it can be the natural answer. But if the goods are not meant for that catchment, Port Botany can become a convenient-sounding detour rather than an efficient gateway.

    Brisbane deserves more attention than many importers give it. For Queensland-bound cargo, the “default to Sydney or Melbourne” instinct often reflects familiarity rather than good freight design. Brisbane can reduce unnecessary inland movement for importers serving the state directly, especially where delivery certainty matters more than the prestige of entering through a larger port. That does not mean Brisbane is automatically better. It means the importer should stop treating eastern Australia as one undifferentiated delivery zone.

    Adelaide can be strategically useful when the cargo is genuinely South Australia-facing or when the importer values a gateway that reduces east-coast backtracking. It is smaller than Melbourne or Sydney, but smaller ports are not inherently inferior. For some supply chains they are simply more honest about where the goods need to go.

    Fremantle plays a different role in Australian freight logic because it is the main container gateway for Western Australia. Fremantle Ports describes itself as handling the overwhelming majority of the state’s container trade. That alone shows why a WA-bound shipment should not default lazily to the eastern seaboard. Once the destination is Perth or the broader WA market, the inland-distance argument changes sharply.

    So the basic map is clear. Melbourne and Sydney dominate national attention. Brisbane is often the logical choice for Queensland, Adelaide matters when South Australia is the real market, and Fremantle is decisive for Western Australia. Importers go wrong when they reduce this to a popularity contest between ports instead of matching the gateway to the freight job.

    An elevated view over a large Australian container terminal showing dense, orderly stacks of containers extending toward working gantry cranes at the berth.

    What the Throughput Numbers Actually Tell You

    The rough numbers behind the hierarchy explain why the habit of defaulting to the biggest gateway is so durable. Melbourne handled 3.39 million TEU in the 2024–25 financial year, up 3.7% on the year before. That makes it Australia’s busiest container port by a clear margin: Port Botany moved roughly 2.5 million TEU, Brisbane 1.4 million, Fremantle 0.8 million, and Adelaide 0.4 million. The ranking is real, and it does buy something concrete: more services, more sailings, and more competitive line-haul rates on the ocean leg.

    But throughput measures ocean-side density, not your landed cost. A Perth importer might route through Melbourne simply because it is the larger port. That choice buys route density they will never use, plus roughly 3,400 kilometres of eastern-seaboard-to-WA backhaul that Fremantle would have removed entirely. The useful question is never which port moves the most boxes. It is how much the extra sailings on a larger gateway are actually worth once the inland leg is priced in. For a genuinely WA- or Queensland-facing shipment, that premium is usually smaller than the backtracking it creates. Pricing that trade-off honestly is the core of any serious total landed cost calculation.

    Why the Best Gateway Depends on the Inland Job, Not Just the Ocean Leg

    The ocean leg usually gets the storytelling. The inland leg usually decides whether the plan was intelligent.

    If the goods are heading to Melbourne warehouses, Melbourne’s scale and directness can be compelling. If the goods are for greater Sydney distribution, Port Botany may be the cleaner answer. If the goods are going deep into Queensland, Brisbane can save an importer from paying for a hidden second strategy after discharge. And if the cargo is for Western Australia, routing through Fremantle is often not a refinement. It is the core logic.

    This matters for delivery timelines as much as for cost. A port is not just a point of arrival. It is the beginning of the next chain: deconsolidation, clearance coordination, trucking, rail, warehouse appointment slots, and final delivery sequencing. A gateway that adds unnecessary inland complexity often feels acceptable while the shipment is still at sea and much less acceptable once the post-port costs begin to accumulate.

    The same landed-cost logic applies to the freight quote itself, and pricing your actual gateway beats a generic estimate.

    That is one reason Inland Rail matters conceptually even for importers who are not routing cargo on that corridor today. Australia’s freight network is not static. Port choice is partly a bet on how efficiently the national inland system can move the goods after discharge.

    Before selecting a port, the smartest importers ask a blunt question: “If this port is not the closest honest answer to the destination market, what exactly are we gaining by using it?” If the answer is vague, the gateway decision probably is too.

    A single truck queued behind two others at a container terminal's gate, engines idling, morning light with soft engine-heat shimmer above the hoods.

    How Congestion, Productivity, and Cost Change the Picture

    Port choice is also about how stress shows up in the system. Throughput, stevedore performance, truck turn times, landside pressure, and handling costs all shape the commercial reality of using a gateway. BITRE Waterline and ACCC container-stevedoring reporting both matter because they move the discussion beyond anecdotes and into observable system performance.

    The practical lesson is not that one port is always “congested” and another is always “smooth.” It is that importers should not choose a port on city prestige and ignore the landside reality. An importer may save money on one line-item and lose far more through slower retrieval, inefficient inland transfer, or weak alignment with the final distribution footprint.

    Infrastructure Australia has also highlighted the strategic importance of major freight gateways and the broader question of port efficiency in national supply chains. That reinforces the same core point: a port is part of a system, and weak system fit eventually shows up in commercial results.

    Importers rarely price one operational detail in advance: the Vehicle Booking System (VBS) each terminal runs to schedule truck collection slots. A container that clears customs cleanly can still sit in the yard for days if the receiver’s transport operator cannot secure a VBS slot during a congested week. Slot availability tightens fastest at the terminals carrying the most volume. That is a second, quieter argument against defaulting to the biggest port: the gateway with the most ship calls is often also the gateway where the actual bottleneck is the trucking slot, not the vessel berth.

    Revisit the gateway choice whenever the cargo profile changes. A port can be rational for a broad east-coast replenishment job and still be a poor fit for a WA-focused project. A gateway can make sense while the importer is buying flexibility, then stop making sense once priorities shift toward faster regional delivery or lower inland handling complexity. Timing matters in the same way: a port that handles a January shipment cleanly may struggle with the same cargo arriving inside the peak shipping window, when berth pressure and inland congestion compound.

    “Truck turn times” sound abstract until they show up as a number on an invoice. Trucks routinely wait an extra 60–90 minutes per pickup at some container yards. That is not just an inconvenience for the transport operator. The time gets priced into detention charges, driver labour, and the knock-on delay to whatever delivery slot was booked at the other end. Multiply a modest 30-minute average delay across a business receiving even a handful of containers a month, and the yearly cost of landside inefficiency can exceed what most importers ever save by chasing the marginally cheaper ocean freight quote. BITRE and the ACCC publish stevedore performance data because this gap between the freight invoice and the total landed cost is real and measurable. It is also easy for an importer to miss if they only compare the number on the shipping line’s quote.

    We price Australian imports around the gateway that fits your cargo.

    Most SMEs receive a detailed, all-inclusive quote within 24 hours, no hidden fees, built around your real port and destination.

    Price your Australia import

    How to Choose a Smarter Australian Port

    The right port choice usually comes from asking a better set of questions:

    • Where do the goods actually need to end up, not just where the biggest famous port is?
    • How much inland transport does each gateway option create or avoid?
    • Is the shipment sensitive to delivery timing, warehousing slots, or regional distribution speed?
    • Would a smaller but better-aligned port produce a cleaner total outcome than a larger default gateway?
    • What does the chosen gateway do to total landed cost once transport after discharge is included?

    If the answer is still “Sydney” or “Melbourne,” that may be correct. But then it is correct for a reason, not because those names dominate the national map. Freight decisions made from habit tend to be expensive. Freight decisions made from distribution logic tend to age better.

    Choose a gateway with the inland job in mind, and the payoff is simpler delivery plans, fewer downstream surprises, and better alignment between the ocean booking and the real commercial job. Swift Cargo’s Australia shipping process outlines how port selection fits into the broader import workflow.

    Shipping Timeline to Australia   Sydney vs Melbourne vs Brisbane: Which Port Is Best for Inbound Cargo

    Related reading: Container Detention and Demurrage in Australia: How the Charges Work and How to Avoid Them

    Frequently Asked Questions

    What is the biggest container port in Australia?

    Port of Melbourne is generally the largest container port in Australia by throughput. That makes it a central national gateway, but not automatically the best choice for every destination.

    Is Sydney always the best port for imports into Australia?

    No. Port Botany is a major gateway, but the best port depends on where the goods need to go after discharge. For Queensland-, South Australia-, or Western Australia-bound cargo, other gateways may produce a cleaner total delivery plan.

    Why does port choice affect inland freight?

    The port is only the start of the domestic delivery chain. Trucking distance, rail options, warehousing logic, and final destination all change depending on where the container enters Australia.

    Should importers choose the biggest port or the closest port?

    Neither by default. The right choice is the port that best balances vessel access, post-port handling, inland transport, and final delivery efficiency for the actual shipment.

  • “Amazing Thailand”: How the 1997 Baht Crisis Built a Tourism Boom

    “Amazing Thailand”: How the 1997 Baht Crisis Built a Tourism Boom

    On July 2, 1997, Thailand gave up defending the baht. What followed was not a tidy market adjustment but a violent economic repricing that tore through banks, corporate balance sheets, and public confidence across the region. Most retellings of the crisis stop there. They stay with the collapse.

    That misses the more interesting part. Thailand did not merely survive the shock. A much weaker currency was among the ugliest features of the crisis, and Thailand converted it into a usable international offer. The country became cheaper for foreigners almost overnight, and the Tourism Authority of Thailand moved faster than most governments would have dared. Instead of treating tourism promotion as a soft extra during a financial emergency, it used tourism as one of the quickest ways to pull foreign spending back into the economy.

    That is why the “Amazing Thailand” campaign matters. Not because it was catchy, and not because every tourism board eventually starts talking about experiences, culture, or hospitality. It matters because Thailand understood a hard commercial truth that many governments and businesses still miss: when an exchange-rate shock changes purchasing power, demand does not automatically appear. Someone has to package the new value, distribute it, and turn it into actual economic behavior.

    The late-1990s campaign did exactly that. Thailand took a crisis-born pricing advantage and translated it into a global value proposition. It linked currency weakness to destination marketing, then reinforced that effort with distribution partnerships and travel-industry channels that could reach high-value visitors. The campaign did not fix the whole economy. But it did something important and fast: it turned a macroeconomic wound into an exportable service offer.

    That makes this more than tourism history. It is a lesson in how countries turn international attention into spending. For Swift Cargo readers, that matters because Thailand’s modern relocation, logistics, and long-stay appeal did not happen by accident. The country spent decades getting better at converting global movement into local economic activity. The same country that learned how to market itself intelligently to travelers later became one of Asia’s more durable hubs for expats, trade-linked movement, and cross-border services.

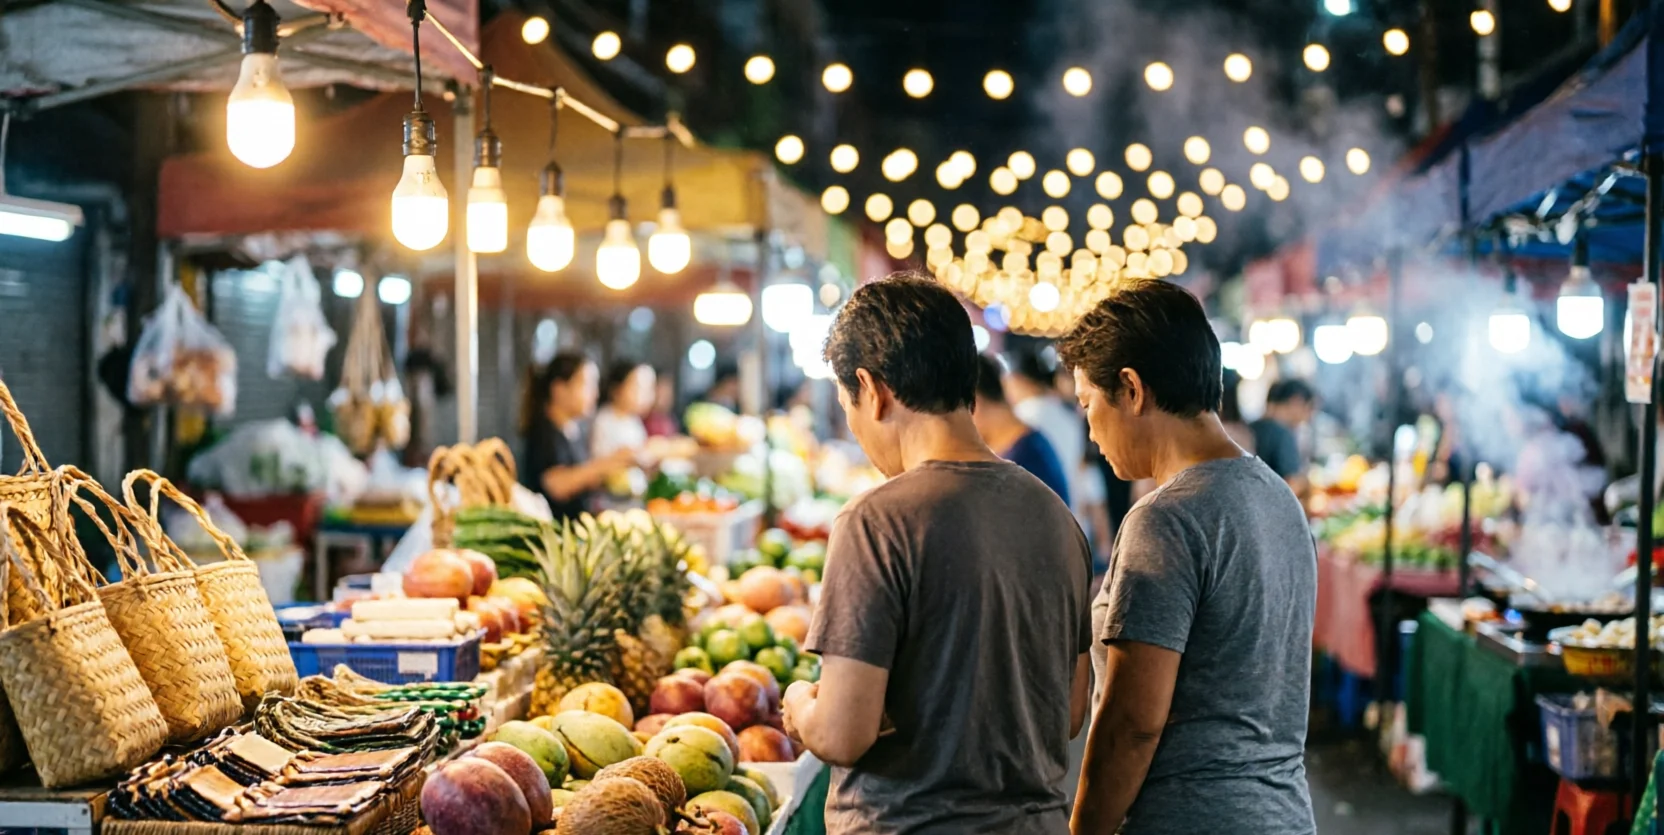
    Busy Thai market scene showing local commerce, cultural exchange, and everyday street-level spending in Thailand

    Street markets, food, and local commerce became part of Thailand’s practical value proposition when foreign purchasing power suddenly strengthened.

    If you want the companion angle on how transaction data and card-network partnerships strengthened this broader system, read Thailand Used Credit‑Card Data to Market Tourism in the 1990s. If you want the infrastructure layer underneath Thailand’s long tourism rise, read U.S. Military Bases in Thailand Became the Backbone of a $50B Tourism Economy.

    “Amazing Thailand”: How the 1997 Baht Crisis Built a Tourism Boom

    Thailand’s Crisis Was Financial. The Opportunity Was Relative Price.

    The Asian Financial Crisis is often told as a story of currency pressure, capital flight, IMF conditions, and institutional weakness. That framing is correct, but incomplete. Financial crises also reorganize relative prices. Once the baht fell, Thailand became dramatically cheaper for anyone earning and spending in stronger foreign currencies. Federal Reserve History: Asian Financial Crisis IMF: Thailand and the Asian Crisis

    For domestic borrowers with dollar-linked obligations, that repricing was brutal. For foreign visitors, it increased purchasing power immediately and sharply. The same hotel room, restaurant meal, taxi ride, beach holiday, or shopping trip could suddenly feel far cheaper in dollar, pound, yen, or deutsche mark terms, even though the local product itself had not been magically upgraded.

    That is the mechanism many weak-currency stories flatten into cliché. A cheaper country is not automatically a more successful tourism destination. Cheapness creates an opening. Someone still has to tell the market what changed, frame the opportunity credibly, and make sure the signal reaches travelers who are both willing and able to act on it.

    Thailand’s planners understood that with unusual speed. The Tourism Authority of Thailand was already preparing a major campaign linked to national milestones, including the 1998 Asian Games and the King’s 72nd birthday celebrations in 1999. Then the crisis hit, and the campaign’s role changed. The tourism authority repurposed what might have remained a conventional destination push into something more strategic: a way to attract foreign visitors and foreign spending while other parts of the economy were still under pressure. TAT annual report: Amazing Thailand years and economic context Phuket Island overview: campaign context

    The key point is not that Thailand invented tourism marketing during a downturn. It is that the country did not hide from the new economics. It recognized that exchange-rate weakness had altered the destination’s international value and decided to market into that reality instead of pretending it did not exist.

    Crisis Timeline

    July 1997: Thailand abandons the baht peg, accelerating the financial crisis. Federal Reserve History

    1998: “Amazing Thailand” becomes a more explicit tourism-led recovery instrument as authorities intensify promotion despite budget pressure. TAT annual report

    1998–2000: International arrivals keep rising even as the region absorbs the crisis. Thailand moves from roughly 7.29 million visitors in 1997 to about 9.58 million by 2000. Nomura Foundation paper: arrivals and receipts

    Long tail: “Amazing Thailand” does not disappear with the recovery. It evolves into a durable master brand. Tourism Authority of Thailand

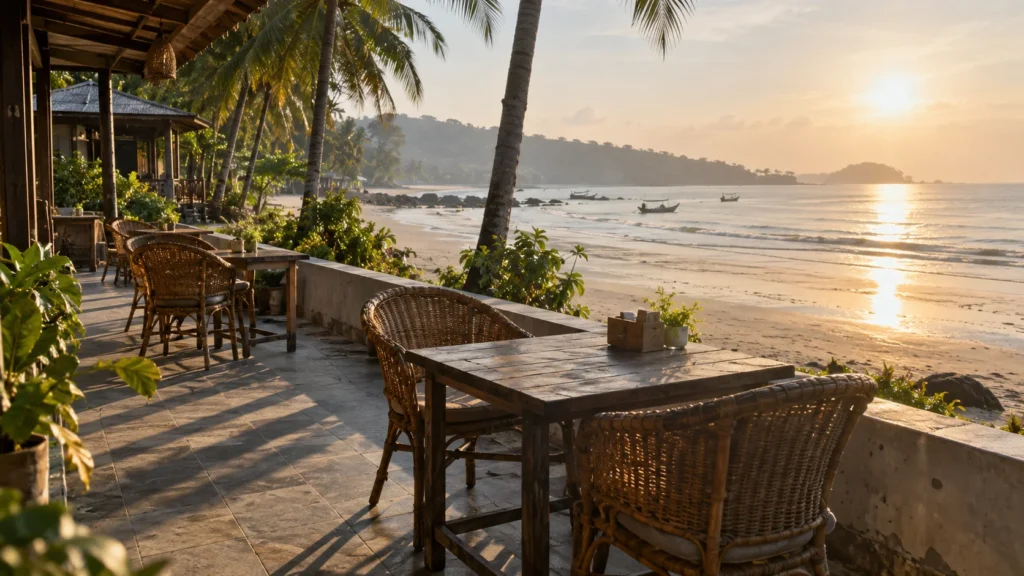
    Early morning light on an empty beachfront hotel terrace in Thailand with rattan chairs and palm shadows

    Why “Amazing Thailand” Was More Than a Slogan

    Most national tourism campaigns are publicity wrappers. They signal mood. They give marketing departments a tag line, a logo system, and a reason to buy media. Nothing is wrong with that, but it rarely changes the economics of demand.

    Thailand’s campaign became more important because it aligned with a real market condition. The destination had just become better value for international visitors. A branding effort that translated that reality into global attention was not cosmetic. It was how the country monetized a new price position.

    The Tourism Authority of Thailand’s own framing supports that interpretation. In its reporting on the period, the authority framed the “Amazing Thailand” years of 1998 and 1999 as part of a broader effort to help alleviate the country’s economic plight. That wording matters. It shows that Thailand was treating tourism promotion as a practical economic lever rather than a pure image exercise. TAT annual report

    This is what separates a serious campaign from decorative state branding. The campaign did not ask the market to ignore the crisis. It reframed one consequence of the crisis as a reason to come: lower foreign-currency prices. That is sharper than generic destination advertising because it connects message to mechanism.

    The approach also let Thailand do something many governments fail to do under stress: move faster than its own institutional caution. In plenty of countries, a financial crisis would have made tourism promotion look politically frivolous. Thailand did the opposite and treated international demand as something worth competing for harder, not less.

    Distribution Was the Hidden Force Multiplier

    A value proposition is not enough. A weak currency only becomes a tourism strategy when the message reaches people likely to act on it. Thailand benefited from traditional travel-distribution channels, but it also leaned on more targeted partnerships, especially with financial networks and related travel ecosystems. That part matters because it improved audience quality, not just message reach.

    We go deeper on that in the companion article on credit-card distribution and spending signals. The short version: Thailand used travel-adjacent infrastructure that already sat close to internationally mobile consumers. That gave the campaign more leverage than a generic awareness push.

    The archived campaign material around card partnerships is unusually revealing. It shows the tourism authorities understood that premium mailing lists, in-house publications, and traveler databases were not just nice add-ons. They were distribution channels to people statistically more likely to travel and spend. Travel Impact Newswire archive: campaign material and card data

    That distribution logic is why the campaign still reads intelligently. Thailand did not simply shout “visit us.” It used channels that were structurally closer to purchasing behavior. In modern language, that sounds obvious. In the late 1990s, it was much less common.

    Did the Numbers Support the Story?

    If the campaign had been little more than patriotic marketing, the rebound would have looked much weaker. Instead, the basic arrival figures point in the right direction. Thailand recorded about 7.293 million international arrivals in 1997, then 7.842 million in 1998, 8.651 million in 1999, and 9.578 million in 2000. Nomura Foundation paper

    Those numbers do not mean tourism alone “saved” Thailand. That would be careless. Thailand’s recovery was shaped by financial stabilization, export performance, restructuring, and broader macroeconomic changes. But tourism brought spending into the country faster than most other sectors could manage.

    That matters especially because receipts can be misunderstood during currency turbulence. Dollar-denominated tourism revenue may not capture the full domestic effect when a weaker local currency amplifies the baht value of foreign spending. A destination can generate meaningful local purchasing power even while its receipts, counted in foreign currency, look messier. Thai academic summary: tourism revenue in baht

    Editorial-style image representing tourism spending and foreign currency flowing into Bangkok during Thailand’s late-1990s recovery

    Tourism mattered because it brought outside spending into Thailand quickly while much of the economy was still under pressure.

    Tourism did not replace broader recovery policy, but it gave Thailand a relatively fast demand engine that could exploit the country’s new price advantage. That made it strategically valuable in a way soft branding campaigns almost never are.

    Why the Brand Survived While Most Tourism Campaigns Die

    Most destination slogans disappear because they are built around shallow novelty. They capture a moment, then start sounding dated as soon as the market moves on.

    “Amazing Thailand” lasted because it evolved into something broader than a campaign. It became a flexible brand architecture that could absorb new themes, markets, and travel trends without forcing Thailand to rebuild its tourism identity from scratch every few years. Tourism Authority of Thailand Amazing Thailand: Amazing New Chapters Amazing Thailand: Your Stories Never End

    This is an underrated sign of strategic competence. Countries usually rebrand because the original idea was too narrow. Thailand’s framework proved flexible enough to keep pointing at beaches, cities, food, festivals, retail, wellness, and long-stay lifestyles without losing recognition.

    That endurance also says something about why the 1998 campaign worked in the first place. It was not pinned to a single emotional claim. It was anchored in a broad commercial truth: Thailand offered a compelling mix of value, accessibility, and diversity of experience. Crisis conditions amplified that truth rather than inventing it.

    The campaign survived because the underlying proposition survived. Once the economy recovered, the brand still had enough elasticity to keep carrying new growth cycles. That is rare.

    The Business Lesson Is About Turning Price Shifts Into Demand

    The most useful lesson here is not nostalgic admiration for a smart government campaign. It is the much colder commercial point underneath it. Exchange-rate shifts change relative value. The winners are usually the actors who recognize that change early, frame it cleanly, and route the message through channels that already touch high-probability demand.

    That principle works beyond tourism. Exporters, service firms, relocation businesses, and logistics operators all live with versions of the same question: when market conditions change the economics of buying from you, can you explain the new value before someone else captures the demand?

    That question is worth turning into a checklist you actually run, not just a rhetorical prompt. Three things have to be true at once for the opportunity to be real: the price shift has to be genuine, not a temporary blip you’d be wrong to build a message around; you need a channel that already reaches people primed to act, not one you’d have to build from scratch; and the message has to be honest about why the value changed, not a rebrand that papers over the reason. Miss any one of the three and the campaign, or the pricing move, or the relocation decision, is a bet dressed up as an insight.

    Thailand did that unusually well in the late 1990s. It did not pretend the crisis was good. It simply recognized that some foreign consumers now had more buying power in Thailand and moved to capture that advantage before it decayed.

    That is one reason the country stayed sticky in the international imagination. Travelers who first encountered Thailand as a strong-value destination often returned for different reasons later, and some eventually became longer-term residents, investors, or repeat seasonal visitors. Tourism familiarity creates a pipeline. It makes a later move psychologically cheaper.

    What This Means for Moving to Thailand Today

    For someone planning a move today, the lesson is not that a tourism slogan matters. It is that Thailand has a long record of understanding how international purchasing power shapes demand. That matters because relocation costs are also exposed to exchange-rate timing, local-price structures, and service ecosystems.

    If you are moving household goods, evaluating shipping modes, or trying to understand customs friction, the same underlying logic shows up in a different form. Thailand can feel dramatically different in cost and usability depending on currency conditions, shipping choices, and timing. That is why practical pages like The Complete Thailand Relocation Guide 2026, How Thai Customs Decides What’s “Used” vs. “New”, and Air Freight vs. Sea Freight to Thailand are worth reading alongside this history.

    For a practical overview of what shipping household goods to Thailand actually costs and involves today, see how the Thailand shipping process works at Swift Cargo.

    Two people browse a fruit stand piled with pineapples and mangoes at a warmly lit night market.

    Why Arrivals Matter Less Than Most Headlines Suggest

    A lot of tourism commentary gets lazy the moment it finds an arrivals chart moving in the right direction. Visitor numbers rise, and the story instantly becomes one of uncomplicated success. That is not how recovery economics works.

    Arrivals tell you that people came. They do not tell you whether the country captured high-quality demand, whether spending per visitor held up, whether tourism businesses gained pricing power, or whether the foreign-currency value of those visits translated cleanly into domestic resilience. Thailand’s own late-1990s numbers show why that distinction matters. Visitor growth was real, but receipts and value capture did not move as neatly as a tourism-brochure version of history would like to claim. Bank of Thailand annual report 1998

    That is not a contradiction. It is normal. In a weak-currency phase, a destination can become dramatically more attractive to foreign travelers while average spending per visitor still shifts unpredictably. Some travelers come because the place suddenly feels cheaper. Some trade up into experiences they would not normally buy. Others treat the destination as a value market and keep spending tight. The macro signal can therefore be positive while the quality mix remains uneven.

    Thailand still benefited because it converted higher foreign purchasing power into sustained demand and longer-term market confidence. But the more useful lesson is analytical discipline: do not confuse volume with value. If you want to understand why a campaign mattered economically, you have to ask what kind of demand it attracted, not just how many passports showed up.

    This is one more reason the “Amazing Thailand” case still matters. It was not strong because it created a magical surge in visitors alone. It was strong because it kept tourism economically relevant while the wider economy was still trying to regain balance.

    “Amazing Thailand”: How the 1997 Baht Crisis Built a Tourism Boom: What Thailand Really Built Was Tourism Statecraft

    What Thailand Really Built Was Tourism Statecraft

    The phrase “tourism campaign” can make this whole episode sound smaller than it was. A campaign sounds like advertising. Tourism statecraft is closer to what Thailand was actually practicing.

    Tourism statecraft means treating destination demand as something that can be shaped with intent, not merely advertised to once it already exists. It means recognizing that exchange rates, air access, events, media, infrastructure, card networks, and hospitality capacity all form part of one system. Thailand’s advantage was not just beaches and culture. Plenty of countries have those. It was that Thailand got unusually good at turning those raw assets into an organized global offer.

    The late-1990s crisis sharpened that capability. Under pressure, the country learned to coordinate message, value, and distribution more aggressively. That coordination explains why Thailand stayed resilient as an international destination even as regional competition intensified. A country that has already learned how to sell a shock can usually sell a boom more effectively too.

    Inside a mid-sized regional Thai airport arrivals hall, morning light streams through tall windows onto a modestly busy but orderly floor, a handful of travelers with

    How Thailand Captured Value Instead of Just Chasing Footfall

    The more serious version of this story is not “Thailand got more tourists after a currency collapse.” Lots of countries can post a short-term arrivals bump when they suddenly get cheaper. The stronger question is whether the country captures useful value from that demand.

    Value capture in tourism is harder than most political rhetoric suggests. A destination can get crowded and still underperform economically. Visitors may cluster in a few cheap zones, spend less than expected, book through foreign-owned channels, or concentrate demand into low-margin segments. That is why a pure arrivals narrative can mislead policymakers. A country does not recover because more passports crossed the border. It recovers when foreign demand converts into meaningful receipts, broader business activity, and enough confidence to keep private operators investing. Bank of Thailand annual report 2000

    Thailand was unusually well positioned here because the country already had a relatively broad tourism product. Beach destinations, urban shopping, food, hospitality, domestic travel services, and cultural travel were already established. When the baht fell, foreigners did not just find one discounted product. They found a destination where a whole basket of experiences suddenly felt better value. That is one reason the tourism response had more room to compound than a simpler “cheap holiday” explanation allows.

    This also helps explain later Thailand demand outside leisure travel. Destinations that capture value well tend to create more than tourism receipts. They create familiarity, return visits, property interest, business scouting, and eventually relocation behavior.

    Seen that way, the “Amazing Thailand” years were not just a lucky tourism window. They trained the market to understand Thailand as a place where foreign money could go far without the experience feeling compromised. That reputation compounds much longer than a one-season discount story.

    A dusk skyline and river view shows illuminated boats passing between a city skyline and port cranes.

    What This Article Does Not Claim

    A few caveats make the argument stronger, not weaker.

    First, tourism alone did not repair Thailand’s economy. Claiming otherwise would be unserious. Recovery came from a wider mix of policy, stabilization, restructuring, and external demand.

    Second, the campaign did not invent modern performance marketing. The tools were much more limited, and attribution was much softer than what marketers expect today.

    Third, the useful claim is narrower: Thailand recognized earlier than many destinations that a currency shock had created a marketable change in relative value, and the state tourism apparatus worked to turn that into tangible demand.

    Thailand Did Not Waste the Shock

    Plenty of countries live through exchange-rate trauma. Far fewer manage to transform part of that trauma into a coherent external offer. Thailand did.

    Thailand did not become more beautiful in 1998. It became more affordable to foreigners, and then it marketed that reality with unusual discipline. That is the story worth remembering.

    Modern tourism boards now run versions of the same play with better software, richer analytics, and more channels. The strategic move underneath has not changed: when relative value shifts in your favor, make the market feel it quickly and clearly.

    There is a quieter legacy the receipts don’t capture. The hoteliers and tour operators who ran their businesses through 1997 learned something that stayed with them long after the baht recovered: demand can vanish in a single quarter, and the operators who survive are the ones carrying less debt and more slack than a spreadsheet says they need. Talk to a family-run resort in Krabi that opened before the crisis and you will often find a balance-sheet caution that looks irrational to a private-equity analyst: low leverage, cash held back for a bad season, a reluctance to over-build during the good years. That caution is not a business-school doctrine; it is a memory. When the 2020 pandemic erased Thai tourism far more completely than 1997 ever did, it hit that older generation of operators less brutally than it hit the ones who had only ever known growth. We doubt Thailand planned that resilience. It was paid for once, in 1997, and quietly banked by the people who lived through it.

    Related reading: AUD Volatility 2013–2020: What the Currency Cycle Means for Import Planning

    Frequently Asked Questions

    Was “Amazing Thailand” created only because of the 1997 crisis?

    No. Elements of the campaign were already tied to major national events, but the crisis changed its role and made tourism promotion part of a broader recovery strategy.

    Why did the weaker baht help tourism?

    Because it made Thailand cheaper for foreign visitors paying in stronger currencies, which raised their real purchasing power inside the country. IMF: Thailand and the Asian Crisis

    Did arrivals actually rise after the crisis?

    Yes. Arrival figures rose from about 7.29 million in 1997 to roughly 9.58 million by 2000, even though the wider regional crisis was severe. Nomura Foundation paper

    Why is this relevant on Swift Cargo?

    Because Thailand’s ability to attract international movement is part of the same wider system that later supports relocation, trade, and household-goods demand.

    What made the campaign different from a normal slogan?

    It aligned with a real economic mechanism. The campaign did not invent value; it translated a newly improved foreign purchasing-power position into demand.

  • Moving from Canada to China: Customs, Shipping Costs and Timelines

    Moving from Canada to China: Customs, Shipping Costs and Timelines

    Moving from Canada to China is a layered, months-long process, and the choices you make in the early stages will shape every step that follows. A two-bedroom Canadian apartment typically holds between 2,000 and 4,000 pounds of household goods. Shipping that much internationally requires forethought, paperwork, and the right partners from the start.
    Understanding why you are moving also shapes how you should move. A temporary two-year assignment calls for a different strategy than a permanent relocation.


    Moving from Canada to China: Customs, Shipping Costs and Timelines

    Why Canadians Are Moving to China

    The flow of people between Canada and China has always been significant, but the reasons behind these moves have shifted. Ten years ago, corporate assignments drove most relocations: multinationals sending senior staff to Shanghai or Beijing for two- or three-year stints. Today, the picture is more varied.

    Entrepreneurs are heading to cities like Shenzhen and Guangzhou to be closer to manufacturing supply chains. Canadian university graduates of Chinese heritage are returning to care for aging parents. Remote workers are choosing lower living costs and proximity to family. And a growing number of Canadians are discovering that a modest Canadian pension stretches further in China’s tier-2 and tier-3 cities.


    Your Planning Timeline: Start Earlier Than You Think

    People planning an international move most often start too late. For a Canada-to-China relocation, a comfortable minimum runway is three to four months from the moment you commit to moving. Six months is better.

    Four to Six Months Before Your Move Date

    • Collect quotes from moving services with verified international shipping experience
    • Research Chinese visa requirements for your specific situation (work visa, family reunion visa, retirement visa)
    • Start decluttering aggressively, because every kilogram you don’t ship saves you money
    • Research housing options in your destination city and confirm your arrival timeline
    • Notify your bank and financial institutions about the move

    Two to Three Months Before

    • Book your moving company and confirm shipping method (sea freight vs. air freight)
    • Gather documents: passport, residency records, proof of ownership for high-value items
    • Decide what goes into long-term storage and arrange storage for items staying in Canada
    • Research the specific customs rules for your destination province in China; regulations can vary by port of entry
    • Arrange for someone to handle your Canadian affairs while you are abroad (mail, taxes, property)

    Four to Six Weeks Before

    • Confirm your packing schedule with your moving company
    • Prepare your household inventory, since customs requires itemized lists with approximate values
    • Sort medications and confirm what is permitted to bring into China (some common Canadian prescriptions require special permits)
    • Back up all important documents digitally and store copies in at least two cloud locations

    Moving Week

    • Walk through the home one last time with your movers
    • Confirm your Chinese customs agent has all necessary documentation
    • Arrange temporary accommodation in China for the weeks before your container arrives

    This timeline assumes a smooth process. Real life complicates it: a visa delay, a shifted job start date, a landlord dispute. Build buffer wherever you can.


    Choosing the Right Moving Company for This Route

    Not every moving company in Canada is equipped to handle international relocations. A local move gone wrong is stressful. An international move gone wrong is a crisis, with your belongings stuck at a Chinese port because of missing paperwork.

    What to Look for

    When you compare companies for a Canada-to-China move, the checklist goes beyond price and availability. Ask specifically about:

    • International freight forwarding partnerships: do they work with established forwarders on the China side?
    • Customs expertise: can they prepare or review your customs documentation, or will you be left to navigate that alone?
    • Container options: do they offer both full container loads (FCL) and shared/groupage container loads (LCL)?
    • Insurance coverage: what is the claims process if something is damaged or lost at sea?
    • Destination services: can they arrange customs clearance and final delivery within China, or does their service end at the port?

    Red Flags to Watch For

    Be cautious of unusually low quotes for international moves. International freight has real costs: fuel surcharges, port handling fees, customs brokerage, destination delivery. Quotes that seem too low often leave services out. Get itemized quotes and ask exactly what is covered.

    Also be wary of companies that cannot provide references for international moves specifically. Moving furniture across Canada demands a different skill set than coordinating a 20-foot container through the Port of Vancouver to Shanghai.


    Inline image, 16:9. A realistic scene of a household mid-packing for an international move: open moving boxes on a hardwood floor, a solid-wood furnit

    What to Ship, What to Store, and What to Leave Behind

    Generally Worth Shipping to China

    • High-quality furniture: particularly solid wood pieces that would cost much more to replace in China
    • Electronics: laptops, cameras, specialized equipment (check voltage compatibility)
    • Children’s items: toys, car seats, and strollers, since Canadian-market brands can be expensive in China
    • Sentimental and irreplaceable items: family photos, heirlooms, artwork
    • Specialty items: musical instruments, sports equipment, hobby gear with real replacement cost
    • Books and clothing: if you have a large wardrobe or substantial library, the weight-to-value ratio often works out

    Items to Consider Leaving or Selling in Canada

    • Flat-pack or budget furniture (cost of shipping often exceeds replacement cost)
    • Appliances (Chinese apartments typically come furnished, and voltage differences create compatibility issues)
    • Large garden equipment, snow blowers, ice fishing gear
    • Oversized sofas that will not fit in Chinese apartment elevators (measure carefully)
    • Perishables, soil, and most food products (prohibited by Chinese customs)

    Items to Put into Canada Storage

    Storage in Canada makes sense if you might return, or if you are not yet sure this move is permanent. Climate-controlled storage protects furniture, electronics, and valuables during extended absences without the cost of shipping them abroad and back.


    Moving from Canada to China: Customs, Shipping Costs and Timelines

    Canadian Export Rules and Chinese Customs: What Actually Matters

    Canadian Export Requirements

    Canada has relatively few restrictions on personal household goods leaving the country, but important steps still apply. Under the Reporting of Exported Goods Regulations, personal and household effects are exempt from export reporting to the Canada Border Services Agency (CBSA), but those of an emigrant are not. For a permanent move, ask your moving company or customs broker who will file the export report before the shipment leaves. The B4 and B4A forms sometimes mentioned for Canadian moves are import-side documents for goods coming into Canada, so they are not part of an export to China. If you later bring goods back, see Swift Cargo’s dedicated breakdown of Forms BSF186 and BSF186A.

    Certain items require export permits regardless of destination: firearms, some cultural property, controlled technology. If any of these apply to your household, flag them with your moving company early.

    Chinese Customs: The Key Rules

    China’s import rules for household goods are more specific than Canada’s export rules. Per the General Administration of Customs of China, the key points are:

    • Duty-free status applies to used personal effects being imported by someone establishing Chinese residency, but you will need to prove the items are genuinely used (not new in boxes)
    • New goods are subject to import duty, sometimes substantially. Avoid packing new, unopened items
    • Restricted items include fresh food, soil, certain seeds, firearms and ammunition, certain medications, satellite equipment, and religious materials in large quantities
    • High-value items like jewelry, watches, and electronics above certain thresholds require declaration and may be dutiable
    • Vehicles imported from Canada face substantial duties and a complex process; most people sell before leaving

    On this route, a specialist freight forwarder or customs broker is not optional. The paperwork requirements are precise, and mistakes cause delays, fines, or goods held at port. See what Chinese customs requires for household goods shipments before you finalize your inventory.


    Shipping Methods: Sea Freight vs. Air Freight vs. Courier

    You have three realistic options for getting your belongings from Canada to China. The right choice depends on volume, urgency, and budget, particularly when you are deciding between sea freight and air freight.

    Sea Freight (Container Shipping)

    This is the default method for most household moves. Sea freight from Canada to China runs through either the Port of Vancouver or the Port of Montreal. Vancouver is the faster of the two to Chinese ports.

    • Transit time: Approximately 4–6 weeks from the port, plus 1–2 weeks for customs clearance at both ends
    • Cost: Lower per kilogram than air freight for large volumes
    • Options: Full Container Load (FCL, where you fill a 20-foot or 40-foot container) or Less than Container Load (LCL, where your goods share a container with others). If you are not sure how much of a container your own household will fill, use our CBM size guide to check before you book
    • Best for: Anyone moving the majority of their household
    Ground crew load cargo into a plane's belly hold via a motorized loader on the tarmac at dusk.

    Air Freight

    • Transit time: 3–7 business days
    • Cost: 4–6× the cost of sea freight per kilogram
    • Best for: Essential items you need before your sea container arrives, or small volumes of high-value goods

    International Courier (DHL, FedEx, etc.)

    • Transit time: 3–5 business days
    • Cost: Highest per kilogram, but practical for small packages
    • Best for: Documents, a few clothing items, small electronics

    Most people combine methods: sea freight for the bulk of household goods, air freight or courier for the handful of items they need immediately upon arrival.


    Packing for International: Harder Than It Sounds

    Packing for a sea container is a different discipline than packing for a local move. Your belongings will endure vibration, stacking pressure, temperature fluctuations, and humidity changes over weeks at sea. The standards are higher.

    International movers typically use double-walled cartons, professional-grade wrapping materials, and wooden crating for fragile or high-value items. Furniture is blanket-wrapped and secured to prevent shifting. Electronics are packed in original boxes where possible. Customs inspectors in China are accustomed to this, and it can streamline inspection.

    Your Role in the Packing Process

    • Label every box with both English and Chinese content descriptions
    • Photograph the contents of each box before sealing, and photograph high-value items with serial numbers visible
    • Do not pack liquids in the same box as electronics or documents
    • Keep your “first week” essentials in your carry-on luggage rather than the container: important documents, a change of clothes, medications, and a laptop
    • Create an itemized master inventory with estimated replacement values for every item in the shipment, since customs requires it and insurance claims depend on it

    Settling In: The Life Admin Nobody Warns You About

    Residence Registration

    Within 24 hours of arriving at a new address in China, you are legally required to register with the local Public Security Bureau (PSB). If you are staying in a hotel or serviced apartment, they handle this for you. If you are renting directly, you and your landlord need to go to the PSB together. Not registering is a fine-able offense.

    Bank Account

    Opening a Chinese bank account typically requires your passport and your residence registration certificate, and some banks also ask for a local SIM card. Bank of China, ICBC, and China Construction Bank all have English-speaking staff at branches in major cities. A local account is not optional for daily life.

    In a small Chinese mobile phone shop's doorway, a newly arrived expat stands mid-conversation with a staff member, phone in hand but screen unreadable, city street life

    SIM Card and WeChat

    China’s digital payment infrastructure runs almost entirely through WeChat Pay and Alipay. Get a local SIM and set up WeChat immediately, because most food delivery, taxi apps, and social connections run through the same ecosystem.

    Healthcare

    Buy international health insurance that covers China. Canada’s provincial health plans cover only limited emergency care abroad. If you are employed in China, your work unit will likely provide some coverage, but you should supplement it with a private international plan.


    Moving a Business or Office from Canada to China

    Corporate and office moves to China face requirements that household moves do not. Equipment, inventory, and commercial goods are assessed differently for duty purposes than household items. You will need a licensed customs broker with commercial import experience on the China side.

    Technology export controls are also relevant: certain types of software, encryption technology, and specialized equipment may have to comply with the Canadian Export and Import Permits Act before they leave Canada. If your business handles any kind of controlled technology, get legal advice on export controls before packing anything.

    Planning a Business Move

    • Engage a customs broker in China early, ideally before you finalize what you are shipping
    • Determine whether your business assets will be imported as corporate property or personal property (the rules differ)
    • Expect your team to arrive in China weeks before your office equipment does, and plan interim setups
    • Review your insurance coverage: commercial marine insurance for business equipment differs from personal effects coverage

    International business moves turn on one question: does the freight company work directly with commercial customs brokers at Chinese ports, not just general freight forwarders? Ask it directly when you get quotes. Get a quote for corporate freight to China to compare your options.


    Spend an afternoon with the packing inventory for a Canada-to-China move and a quiet drama shows up in the columns. A winter parka declared at a few hundred dollars sits two lines above a rice cooker the owner nearly left behind and now cannot picture the new kitchen without. Chinese customs reads that list literally: each item carries a declared value, electronics are checked against serial numbers, and anything wooden can raise a quarantine question. The moves that clear cleanly tend to belong to people who treated the inventory as the working document it becomes the moment the container reaches Shanghai, not as a last-night chore. The list, in the end, is the shipment. The rest is the box it travels in.

    The choice between a two-year assignment and a permanent relocation changes almost every downstream decision. Most of the costly mistakes start when you treat that choice as a detail to sort out later instead of the first real bet you’re making. Shipping a full household on a temporary-assignment budget is a different wager than storing the bulk of it in Canada and shipping light. The right call depends on information you have at the planning stage: your contract length, your employer’s repatriation terms, and your attachment to your own furniture. Getting this wrong doesn’t always look wrong at the time. Take a family that ships everything for a two-year posting that turns into six months. They don’t find out the decision was miscalibrated until the shipping bill and the storage bill both land in the same month. Name the real bet before you book, and that outcome will not surprise you.

    Related reading: Moving from Canada to Thailand: Freight, Customs and Visa Guide

    Frequently Asked Questions

    How far in advance should I contact movers for a Canada-to-China move?

    Ideally, contact movers four to six months before your planned departure. International moving demands more coordination than a domestic move. Home surveys, customs documentation, container booking, freight forwarding arrangements, and destination-side coordination all take time. Most reputable moving companies handling international routes will want at least 8–10 weeks between booking and the pack date.

    Can I ship my car from Canada to China?

    Technically yes, but it is rarely practical. Importing a foreign-manufactured vehicle to China brings import duties that can equal or exceed the vehicle’s value, complex modifications to meet regulatory requirements, and long processing times. Most people moving from Canada to China sell their vehicle before leaving. If your car has significant sentimental value or is a specialty vehicle, consult a commercial customs broker who specializes in China imports before making any decisions.

    What does a door-to-door international move include?

    A door-to-door international move includes home packing in Canada, transportation to the export port, ocean freight to China, customs clearance at the Chinese port, and delivery to your new address in China. Not every moving company offers all of these services in-house. Some hand off to third-party agents after the container leaves Canada. When evaluating your options, ask specifically who is responsible for each stage and what happens if something goes wrong mid-transit.

    Are there items I cannot bring into China from Canada?

    Yes. Prohibited and restricted items include fresh food and produce, soil and plant material, firearms and ammunition, certain medications (including some common over-the-counter Canadian medications, so check the specific active ingredients), satellite receiving equipment, large quantities of religious materials, and goods that infringe Chinese intellectual property laws. Give your moving company a complete inventory so they can flag any potential customs issues before your shipment leaves Canada.

    How long does it take for my belongings to arrive in China after leaving Canada?

    Total door-to-door time typically runs 8–12 weeks. This breaks down roughly as 1–2 weeks for packing and ground transportation to the port; 4–5 weeks for ocean transit from Vancouver to major Chinese ports (Shanghai, Tianjin, Guangzhou); and 2–3 weeks for customs clearance and domestic delivery within China. These timelines can extend if your shipment is selected for physical customs inspection in China. An inspection adds 1–2 weeks. Plan your first month in China assuming your belongings will not be there yet. Ship essential items by air or bring them in checked baggage.

  • Thailand Used Credit-Card Data to Market Tourism in the 1990s

    Thailand Used Credit-Card Data to Market Tourism in the 1990s

    Modern travel marketing likes to pretend it was born when ad platforms, dashboards, and loyalty apps became sophisticated enough to track users at scale.

    Long before tourism boards had real-time ad attribution, Thailand had started moving toward a more intelligent version of destination marketing. The important shift was not that Thailand suddenly became creative. Thai tourism planners grasped something many destination marketers still miss: the most valuable travel marketing systems are built on distribution, behavioral proof, and economic timing, not on slogans alone.

    Thailand’s card-network partnerships in the late 1990s were not just sponsorships. They were an early bridge between audience access and spending intelligence. The Tourism Authority of Thailand was learning how to market a destination to travelers who were already more likely to spend. It was also getting better signals about whether those travelers created economic value once they arrived.

    The result was not a modern CRM stack in the software sense. It was cruder than that. But the commercial logic was close enough that the campaign reads as a precursor to modern tourism analytics. Thailand’s tourism planners used cardmember publications, mailing-list access, transaction data, and distribution partnerships to reach high-value travelers during a moment when exchange-rate conditions made the country especially attractive.

    This also explains why Thailand’s tourism statecraft kept working long after the 1997 crisis. The country learned to treat tourism less like generic promotion and more like a system. We looked at the macro side of that shift already in How “Amazing Thailand” Turned the 1997 Baht Crisis Into a Tourism Boom. We also traced the deeper infrastructure roots in U.S. Military Bases in Thailand Became the Backbone of a $50B Tourism Economy.

    Editorial-style image representing Thailand pioneering a more data-driven approach to destination marketing before the internet era

    Thailand’s tourism strategy in the late 1990s anticipated many of the targeting and measurement ideas that later became standard in travel marketing.

    Thailand Used Credit-Card Data to Market Tourism in the 1990s

    Travel Marketing Before the Internet Was Mostly Blind

    Before search engines, social media, and online booking funnels turned tourism into a measurable performance business, destination marketing was structurally blunt. Tourism boards could buy attention. They could influence travel agents. They could run campaigns in magazines, newspapers, airline channels, and trade publications. But they had limited visibility into what happened after the traveler arrived.

    Arrival data told them people came. Hotel occupancy suggested demand was improving or weakening. Trade feedback from tour operators hinted at which markets were responding. But those signals were all downstream, delayed, and incomplete. They described volume better than value.

    A destination can attract more visitors without materially improving the economic quality of demand. A country may fill rooms and still fail to maximize foreign-exchange inflows, retail spending, premium leisure spending, or the broader multiplier effects that policymakers actually care about. Counting arrivals is not the same thing as understanding economic performance.

    Travel agencies sat at the center of this older system. They were distribution chokepoints. Airlines and wholesalers also mattered because they controlled routes, packaged inventory, and consumer attention. Tourism authorities therefore had to work through intermediaries. That made distribution power essential, but it still did not solve the measurement problem.

    Vintage-style holiday imagery evoking how Thailand was marketed to international travelers before internet booking and digital advertising

    Before digital platforms reshaped travel demand, destinations depended on print, travel agents, airline partnerships, and slower feedback loops.

    At the same time, other industries were already learning how customer databases could outperform pure mass advertising. Airline loyalty programs, direct-mail systems, and early database marketing had proved a basic idea: if you know something about past behavior, you can market more efficiently than if you shout at everyone equally. Research on database marketing in travel and tourism was formalizing this logic. Airline loyalty systems demonstrated how customer records could create better targeting and stronger retention. Bournemouth University: Database Marketing in Travel and Tourism AAAI case study: frequent-flyer customer database

    Tourism boards, however, rarely owned that level of behavioral signal themselves. They needed a partner that could do two things at once: offer access to travelers likely to spend, and show how those travelers behaved economically inside the destination. Credit-card networks were well positioned to do both.

    The Real Insight Was Not “Data.” It Was Economic Visibility.

    People often reduce this story to the soft claim that Thailand “used data.” That is directionally true and still too lazy to be useful. More precisely: payment networks let tourism planners see economic behavior that ordinary tourism reporting could not show.

    Every international card transaction captures more than a sale. In aggregate, it becomes a map of traveler value: where people are spending, how much they are spending, which segments appear stronger, and whether a campaign is bringing in visitors who matter economically rather than just statistically. For a tourism authority trying to recover from a regional financial crisis, that kind of visibility is strategically different from simply knowing headcount.

    By the late 1990s, card companies had a structural advantage over tourism boards. They sat inside the payment layer of international travel. They could see activity in hotels, restaurants, retail, and experiences. Tourism boards could infer visitor significance. Card networks could observe spending behavior directly. UN Statistics presentation: Visa analytics and TAT

    That meant Thailand’s tourism planners were not just buying exposure when they worked with payment companies. They were also learning which travelers generated the strongest return. Once that frame is in place, the campaign reads differently. It stops looking like a patriotic branding push wrapped around a crisis. It starts looking like a destination-level effort to align message, distribution, and value capture.

    The campaign still feels modern in retrospect because it moved beyond demographics toward behavior. It cared not only about where a traveler came from, but about whether that traveler was part of a segment with observable spending power. Modern performance marketers would recognize the logic immediately.

    Card Networks Were Also a Distribution Machine

    Credit-card companies in the 1990s did not just process payments. They also published magazines, sent direct mail, maintained premium cardmember communications, and built trust-rich relationships with customers who were already affluent, internationally mobile, and comfortable transacting abroad. That is an unusually high-quality audience for a tourism campaign.

    Partnerships with financial networks let Thailand reach consumers who were more likely to travel internationally and more likely to spend meaningfully once they arrived. Instead of relying solely on broad destination promotion, the campaign could piggyback on a channel that already filtered for valuable behavior.

    Cardmember publications were not merely brand halo placements. They were highly targeted media environments before digital targeting made that commonplace. Premium travel offers, destination features, and curated editorial all sat inside a communication system designed for people with demonstrated purchasing power. Expression magazine for American Express cardmembers American Express publishing history

    Thai temple travel scene evoking the aspirational holiday imagery used to promote Thailand to overseas travelers in the pre-internet era

    Cardmember publications gave destination campaigns access to an affluent audience long before modern ad platforms made similar targeting routine.

    The Tourism Authority of Thailand was explicit that these relationships mattered. Card-network partnerships gave Thailand access to in-house publications and mailing-list channels that would otherwise have been difficult or expensive to replicate, according to contemporary campaign material and later archived reporting. Travel Impact Newswire archive: 1998 campaign materials and card data

    Spending Data Turned a Branding Campaign Into a Feedback Loop

    One of the hardest problems in destination marketing is proving whether a campaign changed anything economically meaningful. Branding campaigns are usually defended with soft proxies, selective anecdotes, or broad arrival growth that may have had multiple causes. Thailand’s card-network partnerships reduced that ambiguity.

    Tourism officials cited early signals from major card issuers showing that international spending activity was rising during the campaign period. The frequently cited figures included sharp growth in American Express cardmember spending and a reported rise in international Visa transactions in Thailand during 1997. Travel Impact Newswire archive: 1998 campaign materials and card data

    Those figures are not a modern attribution model. They do not prove that every dollar of spending came directly from one campaign message. But they narrow the gap between promotion and observed behavior. They show that tourism planners were at least trying to evaluate market response through spending signals instead of relying only on narrative.

    Thailand’s real innovation was not simply partnering with card companies. It was combining a demand shock, a targeted distribution channel, and a partial performance signal into one coherent marketing structure. That structure makes the campaign look ahead of its time.

    The Baht Crisis Created the Offer. The Data Helped Thailand Aim It.

    No account of the campaign is complete without the exchange-rate context. The 1997 crisis made Thailand dramatically cheaper for foreign visitors holding stronger currencies. That was the offer, whether stated explicitly or not. But offers do not convert themselves. They have to reach the right people, through the right channels, with the right framing.

    We already explored how Thailand turned crisis conditions into tourism opportunity in our analysis of the 1997 baht crisis and the Amazing Thailand response. The economic conditions made Thailand attractive, but the card-network partnerships put that message in front of consumers with demonstrated travel and spending power.

    Lots of countries experience depreciating currencies without turning that into a durable tourism advantage. Thailand’s comparative strength was distribution, branding discipline, and enough intelligence to use the opening well.

    You can see a similar logic in modern relocation and freight demand. Price dislocation attracts attention, but infrastructure, process clarity, and trusted channels turn attention into actual movement. That is part of why Thailand still matters for relocation today. It is also why pages like The Complete Thailand Relocation Guide 2026 and Air Freight vs. Sea Freight to Thailand sit naturally beside this historical analysis.

    A vintage mechanical card-imprinting machine and fanned stacks of punch-style transaction slips on a desk beside a period world map, evoking 1990s payment-data processing technology

    Why This Was an Early CRM Mindset, Not Just Clever Promotion

    Customer relationship management is often discussed as software. That framing is too narrow. At its core, CRM is a commercial logic: identify the audience segments that matter most, understand their behavior, communicate with them more intelligently, and optimize toward long-term value rather than generic reach.

    Thailand’s tourism planners were applying a version of that logic before modern marketing stacks became standard. They were implicitly prioritizing traveler segments with stronger spending potential, using partnerships that gave them direct access to those segments, and validating parts of the strategy through spending data rather than broad sentiment alone.

    That does not mean the Tourism Authority of Thailand had a modern segmentation engine in the SaaS sense. But the campaign was directionally closer to CRM than to classic top-down brand advertising. It cared about high-value audience quality. It used behavior-adjacent data. It relied on channels that could reach known spenders, not just mass-market dreamers.

    Traditional tourism promotion asks: how do we attract more tourists? A more advanced system asks: which visitors generate the most value, how do they behave, and how do we reach them efficiently? Thailand’s late-1990s strategy moved in that second direction.

    Thailand identified the commercial logic that modern destination marketing would later formalize: audience quality beats broad visibility when your goal is economic return.

    How the Model Evolved Into Modern Tourism Analytics

    What Thailand did in the 1990s through card-network partnerships later became easier, broader, and more measurable with digital systems. Today destination marketers use booking data, search data, airline demand signals, payment analytics, social engagement, and ad-platform reporting to understand where demand is forming and which travelers are most valuable.

    But the underlying logic did not change much. Modern tourism analytics still tries to answer the same questions:

    Which audiences are likely to travel?
    Which of those audiences spend the most?
    Which channels reach them efficiently?
    What evidence suggests the campaign is changing behavior?

    That also explains why Thailand is still widely treated as one of the world’s more capable tourism marketers. Its institutional edge did not come only from branding creativity. It came from treating tourism as a system of infrastructure, channels, value capture, and feedback. The same systems thinking shows up in how Thailand built and reused infrastructure over time. That thinking made its broader logistics and commercial relevance so durable. U.S. Military Bases in Thailand Became the Backbone of a $50B Tourism Economy

    Later presentations by Thai tourism intelligence teams explicitly referenced partnership-based analytics, including payment-network support, as part of a broader market-intelligence approach. UN Statistics presentation: Visa analytics and TAT That suggests the 1990s strategy was not a one-off gimmick. It was part of a longer evolution toward evidence-backed tourism management.

    What the Card Data Could Not Do: Thailand Used Credit-Card Data to Market Tourism in the 1990s

    What the Card Data Could Not Do

    Thailand’s use of card-network partnerships was strategically smart, but it was not omniscient. Payment data can show transactions. It cannot explain every motive behind a trip, every non-card purchase, or every future behavior that matters to a destination.

    Tourism economics is always messier than a dashboard makes it look. Cash spending still mattered heavily in the 1990s. Package-tour economics could hide parts of value capture. A successful tourism campaign’s most important effects often sit outside a neat transaction report: later repeat trips, brand familiarity, word of mouth, or eventual long-stay conversion. Card data therefore improved visibility, but it did not complete the picture.

    Even so, partial visibility can still be commercially decisive. Thailand did not need perfect information to outperform a blind campaign. It needed better information than most destination marketers had at the time, and better channels than a generic media buy could provide. Card networks offered both. They pointed toward where value lived, even if they could not explain every layer of why it lived there.

    Why Distribution Beat Publicity

    It is easy to underestimate distribution because modern marketers are trained to fetishize creative. Thailand’s advantage was not only a memorable campaign wrapper. That wrapper sat on top of channels with built-in commercial gravity.

    A tourism board can buy magazine space and hope readers remember it. A payment network, airline, or loyalty channel starts from a stronger position. It already owns a relationship with people who travel, transact, or aspire to premium travel behavior. That makes the message more than publicity. It becomes distribution into a pre-qualified market.

    That distinction carries over to relocation and logistics. Distribution into a high-intent audience usually beats generic awareness. A guide that reaches people already researching a Thailand move is more commercially useful than a broad lifestyle article shown to readers who will never act. Thailand’s late-1990s tourism partnerships show that serious operators understood this principle long before today’s content and performance-marketing language made it fashionable.

    Why High-Value Travelers Mattered More Than Big Crowds: Thailand Used Credit-Card Data to Market Tourism in the 1990s

    Why High-Value Travelers Mattered More Than Big Crowds

    Tourism authorities often talk publicly as if every additional traveler is equally good news. That is politically convenient and analytically weak. The deeper question is about value density: which travelers stay longer, spend more broadly, and generate stronger economic effects once they arrive.

    That is why the card-network layer matters so much in Thailand’s case. Premium traveler ecosystems are not just audience lists. They are proxies for spending power, travel frequency, and behavior that a destination can monetize more effectively than generic mass awareness. For a tourism authority operating in a recovery context, that quality difference outweighs another vague promise of bigger reach.

    Research on travel database marketing keeps returning to the same principle: richer behavioral information improves audience quality, not just audience size. Thailand’s late-1990s strategy therefore reads as an early quality-of-demand play, not merely a visibility play. Bournemouth University: Database Marketing in Travel and Tourism

    What Thailand Kept After the Campaign Moment

    The late 1990s matter partly because the crisis created urgency, but more because Thailand did not discard what it learned once the urgency eased.

    Many governments run one strong campaign under pressure and then slide back into generic promotion. Thailand’s record looks different. Over time, the country kept building tourism intelligence, kept investing in destination positioning, and kept working through channels that linked demand generation to practical market information. UN Statistics presentation: Visa analytics and TAT

    That continuity shows the card-network phase was not an isolated curiosity. It was part of a longer pattern in which Thailand kept getting better at understanding who came, what they spent, and how a tourism system should be tuned around value rather than noise.

    Why This Matters for Swift Cargo Readers

    For people moving to Thailand, doing business with Thailand, or shipping goods into the country, this history explains why Thailand became unusually effective at absorbing international demand. Countries do not become relocation magnets only because they are cheap or beautiful. They become sticky because they build connective systems: transport, hospitality, administrative habits, service ecosystems, and a state or quasi-state ability to direct attention.

    Tourism was one of the channels through which Thailand learned to do that. Once a country gets good at attracting international flows, it often becomes better at serving the wider needs that follow those flows. Some people arrive as tourists and return as long-stay residents. Some businesses first encounter a market through travel and later build trade routes, supply relationships, or relocation plans around it.

    That is why Swift Cargo’s Thailand coverage goes beyond shipping paperwork. Pages such as The Complete Thailand Relocation Guide 2026, How Thai Customs Decides What’s “Used” vs. “New”, and The Forbidden Items List: 11 Things You Cannot Ship to Thailand make more sense as part of a larger Thailand demand system.

    For anyone planning a shipment or relocation to Thailand, Swift Cargo explains how international shipping to Thailand works, from LCL booking to Thai customs clearance.

    What the Thesis Does Not Claim: Thailand Used Credit-Card Data to Market Tourism in the 1990s

    What the Thesis Does Not Claim

    First, this was not modern programmatic advertising before programmatic advertising. The tools were much cruder. The targeting was narrower. The attribution was weaker. The point is not that Thailand had a hidden digital stack in 1998.

    Second, payment data did not fully explain tourism demand. Exchange rates, air connectivity, hotel supply, geopolitical context, and national branding all mattered. Card-network information improved visibility; it did not replace the rest of the system.

    Third, the available evidence often comes through campaign archives, official reporting, and secondary summaries rather than a modern measurement framework. The right standard is therefore defensible interpretation, not exaggerated certainty.

    Thailand Understood That the Best Marketing Channels Already Know Who Spends

    The best channels are not always the loudest. They are often the channels that already sit closest to behavior. Credit-card networks gave Thailand access to travelers with money, proof of spending, and communication systems built around trust-rich customer relationships. In the late 1990s, that combination was unusually powerful.

    Related reading: Retiring in Thailand: Visa, Healthcare, Costs and What to Expect

    Frequently Asked Questions

    Did Thailand really use credit-card partnerships in tourism marketing during the 1990s?

    Yes. Tourism Authority of Thailand campaign material and later archived reporting describe partnerships with card companies that provided access to publications, mailing channels, and spending-related intelligence.

    The partnerships did more than put a logo on a campaign. They helped Thailand reach affluent international travelers through channels that were already trusted and behaviorally relevant. Travel Impact Newswire archive: 1998 campaign materials and card data

    Was this early tourism CRM?

    In logic, yes. In software terms, no.

    Thailand was not using a modern CRM platform, but it was applying a CRM-like idea: focus on higher-value travelers, use behavior-adjacent signals, and improve marketing efficiency by reaching people already likely to spend.

    Why did credit-card networks matter so much to destination marketing?

    They combined audience access and economic visibility.

    Most tourism boards could estimate arrivals but not easily observe how visitors spent money after arrival. Payment networks could supply a much better view into actual purchase behavior while also offering premium communication channels to cardholders. UN Statistics presentation: Visa analytics and TAT

    Did the weak baht alone create Thailand’s tourism advantage?

    No. The currency shock created an opening, but distribution and execution helped Thailand capitalize on it.

    Many destinations benefit temporarily from exchange-rate moves. Thailand stood out because it had stronger tourism branding and distribution partnerships, and because it turned favorable economics into actual demand more effectively.

    What is the difference between publicity and distribution in this case?

    Publicity creates awareness. Distribution puts the message inside channels that already have trusted access to likely spenders.

    That difference is why the card-network partnerships mattered. They were not only media placements. They gave Thailand access to traveler audiences that were already transaction-capable and easier to monetize than a generic mass audience.

    Why is this relevant on a logistics and relocation site?

    Tourism strength often sits upstream of broader international movement.

    Countries that become better at attracting international visitors often build supporting infrastructure, service capacity, and market familiarity that later shape relocation, trade, and freight demand too. That is part of Thailand’s broader international advantage.

  • Moving to Australia Duty-Free: How the UPE Concession Works

    Moving to Australia Duty-Free: How the UPE Concession Works

    One of the most misunderstood phrases in Australia household-goods shipping is “Unaccompanied Personal Effects concession.” People hear the word concession and assume it means the shipment is automatically duty free and automatically simple. That is not how it works.

    Wooden crates or moving cartons labeled Personal Effects being unloaded at an Australian port, with an Australian customs form or B534 declaration visible in frame

    The UPE concession can change the customs-duty and GST picture for qualifying household and personal goods arriving separately from the traveller. But it does not turn the shipment into a compliance-free event, and it does not remove Australia’s separate biosecurity controls.

    That distinction is where a lot of costly confusion begins. A shipment can be customs-favourable and still be operationally difficult. It can qualify on the customs side and still need inspection, treatment, or extra handling because of what is actually inside the consignment.

    The useful question is not just “do I get the concession?” It is “what does the concession actually cover, what does it not cover, and how do I avoid mistaking customs relief for total clearance relief?”

    What the UPE Concession Actually Is

    The Unaccompanied Personal Effects concession is part of the customs treatment for certain personal and household goods that arrive separately from the traveller. It exists because people relocating internationally often do not carry all of their belongings with them as accompanied baggage. Some items move later by sea or air cargo.

    That customs distinction matters. ABF separates accompanied traveller concessions from unaccompanied goods, and the rules are not identical. A shipment arriving later is not automatically treated the same way as items in your luggage just because they are yours. ABF: Duty free concessions

    The concession can allow qualifying goods to clear without the full duty-and-tax burden that would otherwise apply in a standard import scenario. But it is a concession with conditions, not a blanket exemption for anything labelled “household goods.”

    Who It Is Designed to Help

    The concession is designed for genuine personal relocation, not for disguised commercial imports. DAFF’s moving-to-Australia guidance describes personal effects and household goods as unaccompanied items transported into Australia by a returning resident or a new resident via sea or air freight. DAFF: Moving to Australia or importing personal effects

    The underlying purpose is clear: this pathway is for people moving their own belongings, not for using a personal-effects classification to avoid normal commercial treatment on goods that do not belong in that category.

    ABF’s compliance material clarifies that the UPE concession is an area where misuse matters. Incorrect use can lead to non-payment of duties, taxes, and charges, and the agency treats that seriously. ABF: Trade and goods compliance

    Why Ownership and Use History Matter

    One of the biggest practical filters is ownership and use history. ABF’s duty-free guidance explains that unaccompanied goods do not automatically receive the same concession treatment as accompanied baggage and may still be subject to duty and tax unless they have been owned and used overseas for the relevant period. ABF: Duty free concessions

    ABF’s moving-to-Australia guidance specifies that to qualify, household effects must have been owned and used by the traveller overseas for at least 12 months before the move to Australia. Goods purchased specifically for the relocation, regardless of where, generally do not qualify for the concession and attract full duty and GST at the applicable rates. ABF: Moving to Australia

    Many movers unintentionally mix different categories together. Long-owned personal furniture may sit in the same container as newer purchases, replacement appliances, recent online buys, decorative items never really used, or goods that look closer to commercial inventory than lived-in household effects.

    Once that happens, the concession picture becomes less clean. The question stops being whether the container belongs to a relocating family and starts being a more granular question about which specific goods qualify and how the shipment is being presented.

    “Owned and used overseas for at least 12 months” is not just technical wording. It is the main filter that separates a qualifying personal-effects shipment from a cargo mix that may need duty-and-tax assessment on some or all items.

    Customs officer cross-checking a printed declaration form against an itemized packing list at a warehouse table, with boxes on pallets in the background

    What the Concession Does Not Remove

    The most common misconception is that customs relief means total relief. It does not. DAFF clarifies that personal effects and household goods are still subject to biosecurity control because they can carry pests, disease risk, soil, plant matter, animal-origin material, and contamination hidden inside normal household items. DAFF: Personal effects and household goods

    A mover can be told the shipment is eligible for a customs concession and still face inspection, treatment, or destruction/export decisions on specific items, each of which adds days to how long clearance takes at the border. Biosecurity does not disappear just because the goods are personal.

    The concession also does not remove the need to consult BICON where relevant. DAFF’s guidance explicitly tells movers to check BICON if they are unsure whether goods can be brought in, whether they require treatment, or whether extra conditions apply. DAFF: Personal effects and household goods

    The concession can reduce duty and GST for qualifying goods, but it is not a substitute for preparing the goods for Australian inspection standards. Why Used Household Goods Get Inspected in Australia

    For a full picture of how Australia’s customs duty and GST charges work on qualifying and non-qualifying goods, see the Australia customs and import conditions overview.

    Why Paperwork and Packing Detail Still Matter

    The B534 form exists for a reason. Agencies are not just checking whether you say the shipment is personal. They are trying to understand what is actually in the consignment and what risks it creates.

    DAFF explains that it assesses the B534 form and packing list to decide how much of the consignment needs to be presented for inspection and whether goods of biosecurity concern are present. DAFF: Personal effects and household goods

    Accurate paperwork is commercially useful, not bureaucratic decoration. Vague labels such as “miscellaneous household goods” may feel convenient at origin, but they do not help a shipment clear cleanly in Australia if the actual contents include timber, outdoor gear, animal-related items, food-related utensils, or contamination-prone equipment.

    Good packing detail also separates what is likely to qualify cleanly from what may create questions. When that work is skipped, the concession discussion becomes less credible because the authorities cannot easily see what they are being asked to clear.

    The B534 and packing list are risk documents, not paperwork chores.

    If your inventory does not separate owned-and-used items clearly enough to satisfy an officer, that is worth fixing before the container is packed, not after.

    The Australia documents checklist

    The Common Mistakes People Make

    • Assuming every item in a relocation shipment automatically qualifies.
    • Confusing customs concession treatment with biosecurity clearance.
    • Mixing long-used personal goods with newer purchases and expecting one clean answer.
    • Treating the B534 and packing list as paperwork chores rather than risk documents.
    • Assuming “household goods” means low inspection risk even when the cargo contains timber, outdoor items, animal-related goods, or contamination-prone objects.

    Most of the pain around UPE concessions comes from over-simplification. The concession is real and useful. But it works best when the shipment is genuinely eligible, documented accurately, and prepared with the understanding that Australia’s border applies customs and biosecurity logic separately.

    If that separation is understood early, the move becomes far easier to plan. If it is misunderstood, the shipper is often surprised twice: first by the customs answer, and then by the biosecurity answer that still follows. Import Duty and GST Explained for Australia
    Read that list of mistakes closely and a pattern emerges worth stating plainly. Almost every one traces back to the same false belief: that the concession is a single door the whole shipment walks through. It is not. Customs and biosecurity read the same container through two separate lenses, and the shipper who prepared for one is repeatedly caught by the other. The detail that exposes this is usually tiny: one undeclared timber ornament, one bike with dried soil still on the tyres. Yet it reveals the larger truth that the concession relieves a tax, not an inspection. Those were never the same gate.

    Why the B534 Feels Harder Than It Is

    People routinely describe the B534 declaration as confusing, and it is worth asking why. The form itself is short. The difficulty is a mismatch of mental models. The person filling it in thinks in terms of their life: “this is my kitchen, these are my books, that is the bike I ride.” The border system reading it thinks in terms of risk categories: timber, soil contact, animal-origin material, ownership duration. The form is the narrow channel where those two ways of seeing the same boxes have to meet, and most frustration happens exactly there.

    The practical fix is to fill in the form from the border’s point of view rather than your own. Walk the inventory asking the system’s questions (how long owned, what is it made of, where has it been used) instead of describing your household the way you would to a friend. Movers who make that mental switch produce declarations that clear faster, and they are far less surprised by what happens at the arrival end of the shipping timeline. The form did not get easier. The model matched.

    The UPE Concession Is Valuable, but It Is Not a Shortcut Around the Border

    The B534 is one page; the packing list might run to twelve. The two sit side by side on a folding table at the depot. The inspector reads them the way a geologist reads rock layers, not for individual items, but for the pattern: a consistent vocabulary across both documents, room-by-room organisation, ages noted where they help, ownership history that does not need explaining. The shipments that flow through this step are the ones where the paperwork describes the cargo before anyone has to open a box. The shipments that pause are the ones where the inspector has to reconstruct the description from the goods themselves.

    Australia’s UPE concession can materially improve the customs position for qualifying household and personal goods. That makes it important. But the real value comes from understanding its limits as clearly as its benefits.

    A customs concession is not the same as a low-friction shipment. The cleanest moves are the ones where concession eligibility, documentation quality, and biosecurity preparation all line up together, including a BICON pre-check where the conditions exist (see our explainer on Australia’s Biosecurity Import Conditions database).

    The cleanest decision rule for UPE eligibility is to walk the inventory once with a single filter: “Have I personally owned and used this item for at least twelve months before shipment?” If yes, document it and it rides with the household effects. If the answer is “no”, “maybe”, or “I just bought it for the move”, set it aside and decide deliberately: ship at duty, sell or donate locally, or use it for twelve months before shipping if the timeline allows. The expensive UPE surprise is almost never the rule itself. It is mixed shipments where a small share of dutiable items contaminates the rest of the consignment because the inventory does not separate them clearly.
    Why the Concession Is Assessed Item by Item, Not Shipment by Line

    The concession does not apply to a shipment as a single decision. It applies to each item inside it separately. Take a container that includes twelve months of owned furniture, a newly purchased television bought the week before departure, and a set of tools intended for resale. It is not one eligible shipment or one ineligible one. It is three separate assessments, and the outcome for one item does not affect the outcome for another. This is the choice the concession makes, and it is worth naming directly: it exists to relieve duty on genuine relocation of a person’s own established possessions, not to relieve duty on a shipment merely because most of it qualifies.

    The practical failure mode is not dishonesty. It is deciding by shipment instead of by item. Consider an importer who lists “household goods” as a single line on the inventory, with a new appliance folded into the middle of a genuinely owned collection. They have not hidden anything, but they have made the officer’s job harder and their own claim weaker. If an inventory cannot show, item by item, which goods meet the ownership test, it invites a slower, more conservative read of the whole shipment. When an inventory separates owned-and-used items from anything bought in the last twelve months, priced and listed on its own line, it lets the concession do exactly what it was built to do, and nothing more.

    We plan your move around the customs test and the biosecurity one.

    Tell us what’s in the container and we help you sort owned-and-used from newly bought before you ship: fixed pricing, no hidden costs.

    Get your Australia estimate

    Related reading: DAFF Biosecurity Requirements for Australian Imports: By Product

    Frequently Asked Questions

    What is the Unaccompanied Personal Effects concession in Australia?

    It is a customs concession pathway for certain personal and household goods that arrive separately from the traveller, usually as sea or air cargo during a relocation move.

    Does the concession mean I pay no charges at all?

    No. It can improve the customs-duty and GST position for qualifying goods, but it does not remove possible biosecurity inspection, treatment, storage, or other operational costs.

    Do all household goods qualify automatically?

    No. Ownership and use history matter, and shipments that mix different categories of goods can create a more complex customs answer than people expect.

    Why does the B534 form matter so much?

    Because authorities use it, together with the packing list, to understand what is in the shipment and what customs or biosecurity response may be needed.

  • Best Time to Ship to Australia: BMSB, Cyclones and Customs

    Best Time to Ship to Australia: BMSB, Cyclones and Customs

    People often ask for the best month to ship to Australia as if there is a universal answer. There is not. Australia has several overlapping calendars, and the right shipping window depends on which of them affects your cargo most.

    One shipment is dominated by biosecurity season. Another is shaped by cyclone exposure, flood disruption, or the inland route after discharge. Another is driven by customs valuation timing, storage risk, or when a household is ready to receive the goods.

    That is why the practical question is less “what is the best time to ship?” than “what kind of delay or extra cost is this shipment most exposed to, and which window reduces that risk?”

    For Australia, the strongest planning decisions usually come from treating shipping as a timing problem across compliance, weather, and delivery, not just as a freight-booking problem.

    Best Time to Ship to Australia: BMSB, Cyclones and Customs

    Why There Is No Single Best Shipping Window

    “Shipping to Australia” covers very different shipment types, and that alone rules out a universal answer. Four cargo profiles do not face the same timing risks: a container of commercial stock, a family’s household goods, a machine with contamination exposure, and a time-sensitive consignment.

    Each of those shipments moves through a different mix of border logic, operational pressure, and delivery constraints. One importer wants to avoid seasonal biosecurity treatment exposure. Another cares more about storm-season uncertainty in northern Australia. Another needs to align arrival with lease start dates, warehouse availability, or internal inventory deadlines.

    So the best time is the window that gives your specific shipment the cleanest path through departure, transit, clearance, and delivery, not a fixed month on the calendar.

    When Biosecurity Season Becomes the Main Issue

    For many Australia-bound shipments, the biggest timing issue is biosecurity season, not weather. Brown Marmorated Stink Bug measures create a recurring compliance window from 1 September to 30 April, and that window can materially change how affected goods are handled. DAFF: BMSB risk season

    The same goods can therefore sit in a different compliance reality depending on when they are shipped, loaded, or exposed in transit. A shipment that looks ordinary on paper can become more expensive or more fragile operationally once it enters a seasonal control regime.

    So the answer to “best time to ship” often begins with a different question: is this cargo likely to fall into a more tightly managed seasonal pathway? If the goods are BMSB-exposed, machinery-related, vehicle-related, or otherwise sensitive to seasonal screening, the calendar can change the risk profile before the vessel even sails. Brown Marmorated Stink Bug Shipping Season Explained

    Biosecurity timing also matters outside BMSB. Australia’s broader biosecurity system covers household goods, timber items, outdoor equipment, and other contamination-prone cargo, and it is stricter than many movers assume. DAFF: Moving to Australia or importing personal effects

    When Weather and Disruption Calendars Matter More

    For some routes, climate and disruption risk become the more important timing factor. Australia’s tropical cyclone season runs from 1 November to 30 April, according to the Bureau of Meteorology. Cyclones concentrate in the north and north-west, and they affect coastal and inland conditions through wind, rain, flooding, and downstream disruption. BOM: Tropical cyclone season

    Shipping during cyclone season is not automatically a bad idea, but the risk buffer should change. Some shipments need more margin during those months than generic shipping calculators suggest: northern delivery corridors, remote destinations, time-sensitive final-mile legs, and project cargo with tight install windows.
    Seasonality also matters beyond cyclones. Flooding, heavy rainfall, and smoke-related disruption can all affect how predictable a move feels even when the vessel schedule itself still looks intact. The “best time” is often the period where your shipment has the fewest external variables stacked against it.

    This is one reason a southern-metro household move and a northern commercial delivery need different calendar advice. One may tolerate more seasonal uncertainty. The other may not.

    The practical gap shows up in delivery planning. Shipments that discharge at Darwin, Fremantle, or Townsville face a different risk calculation than a Sydney or Melbourne delivery, especially when the goods then move inland during cyclone season. Severe weather can add days or weeks to inland transit through road closures, flooding on inland routes, and port operational disruptions, independent of what happens at sea. Commercial shippers with installation deadlines or just-in-time stock needs should factor these inland variables into the departure window, not just the ocean leg. Bureau of Meteorology: cyclone tracking and forecasts

    Why Commercial Timing Can Differ From Household Timing

    Commercial cargo and household moves often want different timing windows because they are measured differently. A household move usually tries to minimize stress, border friction, and storage mismatch at destination. A commercial shipment tries to hit inventory cycles, avoid peak handling pressure, or manage landed-cost exposure.

    That last point carries more weight than importers usually expect. Customs value in foreign currency is converted at the rate prevailing on the day of export, not the day the goods arrive, according to ABF guidance. ABF: Customs value guidance

    That does not make exchange-rate timing the dominant issue in every move, but it does mean the calendar can affect the landed-cost picture in ways that are invisible if you only think about sailing dates. For some commercial importers, the best time to ship is partly a customs-timing question as well as a logistics question.

    Household shipments, by contrast, turn on concession eligibility, lease timing, and the odds of inspection or treatment on arrival. The “best” window differs because the objective differs. Importers claiming the Unaccompanied Personal Effects concession under Australian Customs Act provisions must also meet timing requirements tied to residency and the owner’s arrival date. Shipping too early or too late relative to that date can affect eligibility. Unaccompanied Personal Effects Concession Explained

    The Constraint Most Timing Guides Skip: The 30 June Deadline

    One form of inventory-cycle pressure is fixed to a date most shipping-timing guides never name: the end of the Australian financial year, 30 June. For any importer carrying stock for resale, goods still on the water at 30 June sit on the balance sheet as inventory rather than as a completed sale. That carries real consequences for tax timing, warehousing cost allocation, and how the year’s numbers read to a lender or an investor. This is a binding constraint in its own right, separate from the biosecurity and weather calendars covered above.

    Two importers can run an identical shipment profile, same goods, same origin, same freight budget, and still have very different years depending on which one worked backwards from that date. One counts backwards from 30 June, adds the realistic transit time for the route, and layers in the BMSB or cyclone-season buffer already covered above. That importer books in time to land before the deadline that actually matters to the business. The other tracks biosecurity and weather calendars but not the financial-year calendar. That importer discovers the EOFY problem in the last week of June, when the remaining options are all expensive and none of them are really solutions: paying for express re-routing, or accepting the inventory-timing hit and explaining it at reporting time instead of avoiding it. The constraint was never hidden. It just was not on the same calendar as the other two.

    How to Choose the Best Window for Your Shipment

    The strongest way to choose a shipping window is to work backwards from the real sources of friction:

    • Check whether the goods fall into a seasonal biosecurity regime.
    • Look at route exposure and destination exposure, not just the departure port.
    • For household moves, align the shipment with actual destination readiness rather than an optimistic arrival guess.
    • For commercial imports, assess whether landed-cost timing or stock timing matters as much as transit time.
    • Build buffer where the calendar creates predictable risk rather than hoping the border will be forgiving.

    In practice, the best time to ship to Australia is the moment when your cargo is least exposed to avoidable compliance pressure, seasonal disruption, and delivery mismatch. That answer is more nuanced than a blog list of “best months,” but it is also much more useful.

    If the move is flexible, use that flexibility deliberately. It gives you room to step around known stress windows instead of absorbing them. If the move is not flexible, the answer is better planning, not panic: cleaner documentation, stronger preparation, a more realistic timeline, and a route choice that respects Australia’s actual operating conditions. Shipping Timeline to Australia: What Actually Controls Delivery Time

    Swift Cargo’s Australia shipping peak months guide maps the key seasonal windows for importers and movers planning an Australia-bound shipment.

    Overlapping orange and blue risk-window bands illuminated across a hand-marked calendar chart pinned to a corkboard, representing layered seasonal shipping risk periods for Australia

    The Practical Way to Find Your Shipping Window

    Most importers try to optimise across biosecurity season, weather, and commercial timing simultaneously. That approach usually produces a window that satisfies none of them. The more reliable method is to identify which single constraint actually controls cost or risk in your specific shipment, and optimise against that one.

    If the goods are BMSB-affected or carry contamination risk, biosecurity is the binding constraint. The window is outside September–April, or you accept treatment cost and timeline uncertainty. If the route runs through a cyclone-exposed northern corridor and delivery timing matters, weather exposure is the binding constraint. Add two to three weeks of buffer between November and April. If the shipment is commercially driven (Q4 inventory needs, contract dates, stock-turn cycles), commercial timing is the binding constraint. The window is whatever your business calendar requires.

    The pre-booking step that most importers skip is reconstructing the full chain before confirming a vessel: which biosecurity window this cargo lands in, what the real arrival date is against the BMSB season, whether the inland delivery window is workable during the expected clearance period, and what happens if the vessel runs ten days late. That check takes around twenty minutes. It catches most of the timing errors that become expensive downstream.

    Some shipments do not fall neatly into any of the three categories above: biosecurity-driven, weather-driven, or commercially-driven. For those, optimise against biosecurity first. The September to April BMSB window is the most predictable recurring cost risk in Australia-bound shipping, and it is the one importers most often underestimate until they receive a treatment or re-inspection invoice. If the goods are not BMSB-exposed, the risk profile shifts, and weather or commercial timing can dominate instead. But starting with biosecurity and working outward is the more reliable planning sequence for most cargo categories. DAFF: BMSB industry advice for importers

    Not All Seasonal Risks Deserve Equal Weight

    Timing decisions improve when you replace vague worry with rough probabilities. A machinery consignment booked to arrive in October sits inside the BMSB window: for goods loaded in a target risk country, offshore treatment is close to a scheduled cost, and untreated cargo faces a realistic prospect of onshore intervention or re-export. Move the same consignment to a June arrival and the seasonal measure does not apply. Compare that with cyclone exposure on a Melbourne delivery: the season nominally runs November to April, but the odds are small that a tropical cyclone materially delays a southern-metro consignment in any given window.

    Many importers weight both risks equally because both appear under the same seasonal-risks heading. The two exposures are not equal. Sort each one into near-certain, plausible, or remote before booking, then spend your flexibility on the first group: a BMSB-window arrival for affected goods is a near-certain cost, while most weather risk south of Brisbane is remote.

    A shipper who books during peak season and gets lucky with a smooth clearance did not necessarily make a good decision. They made a risky bet that paid off, and treating the smooth outcome as proof that timing does not matter is the same reasoning error as blaming a bad outcome entirely on bad luck. The decision worth evaluating is what was knowable when the booking was made, not what happened to that one container. At booking, the biosecurity season load, the weather-disruption calendar, and the 30 June deadline pressure all combine to make some windows higher-variance than others, whatever any single shipment’s outcome ends up being. Judging the calendar by last year’s one lucky shipment is exactly the trap this decision keeps punishing quietly, one bad quarter at a time.

    Related reading: USA to Australia Shipping Times: Port-by-Port Timeline Guide · Shipping Routes to Australia: A Lane-by-Lane Guide

    Frequently Asked Questions

    What is the best month to ship to Australia?

    There is no single best month for every shipment. The right window depends on cargo type, route, destination, biosecurity exposure, and how much flexibility you have around departure and arrival.

    Does BMSB season affect the best shipping time?

    Yes. For affected goods, the BMSB window from 1 September to 30 April can change treatment, routing, timing, and clearance risk in ways that materially affect the shipment.

    Does cyclone season matter for Australia shipping?

    It can, especially for northern routes, exposed destinations, and time-sensitive deliveries. It matters less as a headline than as a reason to add timing buffer and route awareness.

    Is the cheapest freight month always the best month to ship?

    No. A cheaper booking window can still be a worse overall decision if it exposes the cargo to seasonal controls, disruption, or destination timing problems that create bigger downstream costs.