Author: Carl Ansama

  • Import Solar Panels from China to Australia: CEC, EESS, 0% Duty

    Import Solar Panels from China to Australia: CEC, EESS, 0% Duty

    Australia’s solar installation rate is among the highest per capita in the world, and the vast majority of panels, inverters, and battery storage systems installed here are manufactured in China. Chinese solar manufacturers have achieved a scale, cost structure, and product quality that no other country currently matches at volume. For Australian solar businesses, the supply chain runs through Jiangsu, Zhejiang, and Guangdong.
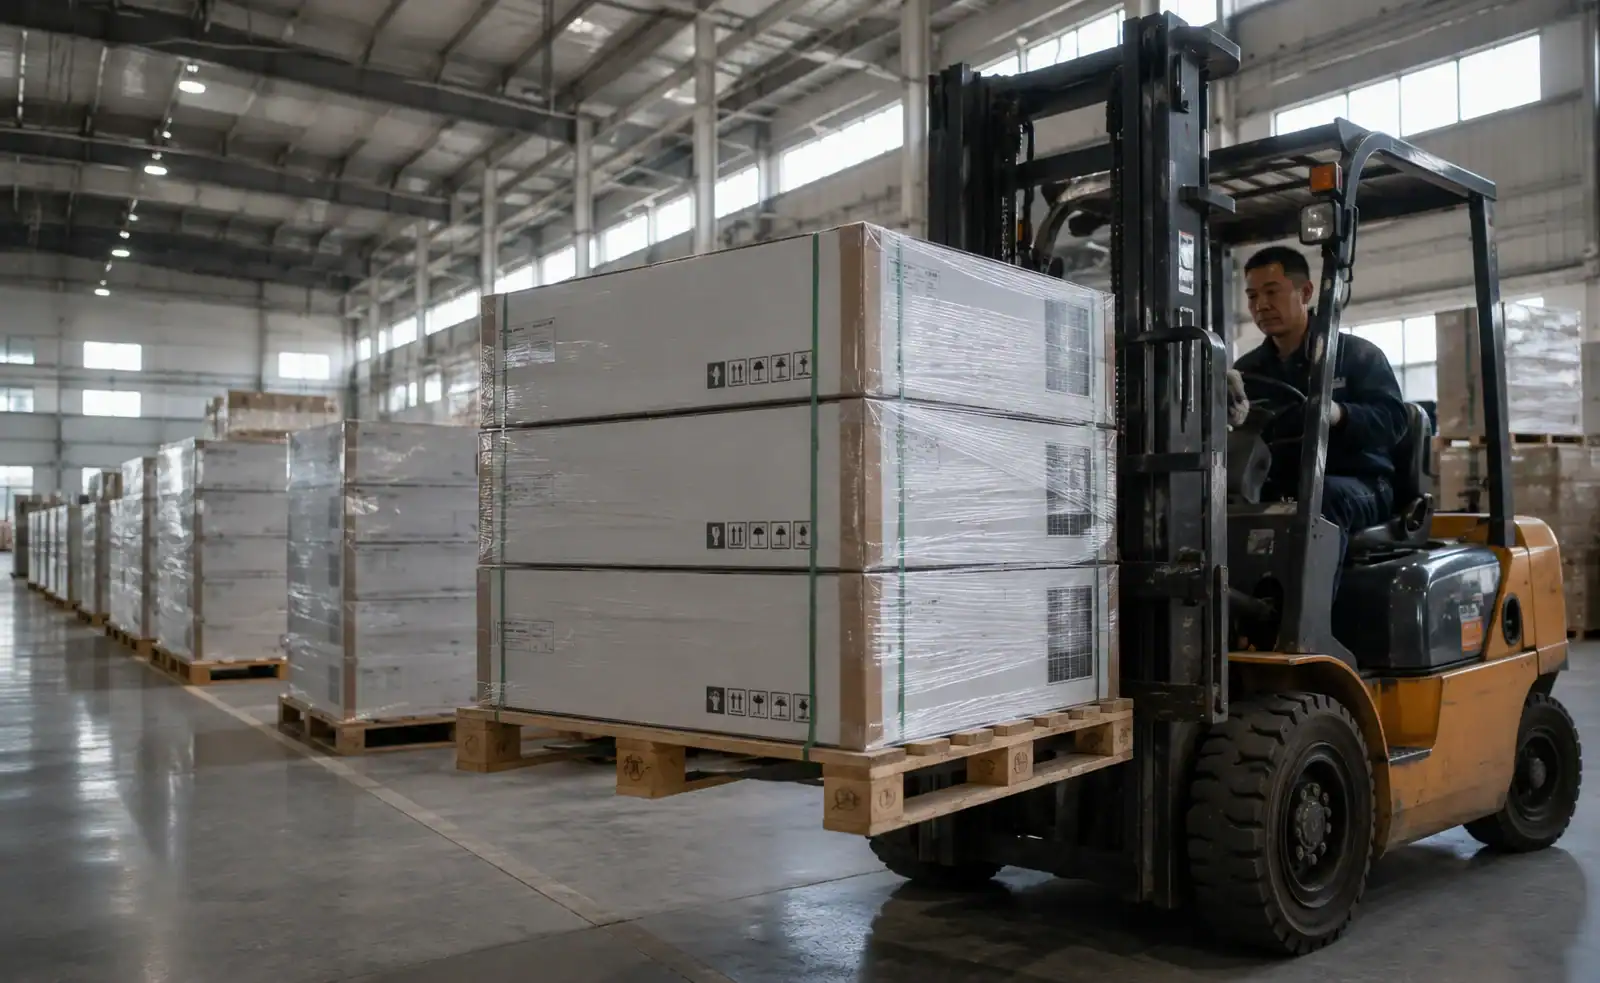
    Solar panels being loaded into a container at a Chinese factory or Jiangsu/Zhejiang port facility, with an Australian port (Port Botany or Melbourne) or rooftop

    Solar equipment sits at the intersection of customs, electrical safety regulation, energy policy, and biosecurity. Each has its own requirements, its own authority, and its own consequences for getting it wrong. Once the framework is understood, it is entirely navigable. And unlike the US market, Australia imposes no anti-dumping duties on Chinese solar, which keeps the economics straightforward.

    HS Codes: Get Classification Right Before Anything Else

    Solar equipment spans multiple HS chapters. The classification determines your duty rate, your ChAFTA eligibility, and whether any special import conditions apply.

    Product HS Code MFN Duty ChAFTA Rate
    Solar PV panels (photovoltaic cells) 8541.40 0% 0%
    Inverters (static converters) 8504.40 0% 0%
    Lithium-ion battery storage 8507.60 0% 0%
    Racking/mounting (steel) 7308.90 5% 0% with CoO
    Racking/mounting (aluminium) 8302.41 5% 0% with CoO

    Solar panels are classified as semiconductor devices (HS 8541), not generators or electrical machinery, which is why they attract 0% MFN duty. This classification is settled and consistent. Misclassification into HS 8501 (electric motors and generators) would attract a duty rate. Confirm with your customs broker and use the ABF Tariff Classification tool for each product category you import.

    For racking and mounting systems, the ChAFTA 0% rate requires a valid Certificate of Origin from an authorised Chinese issuing body (CCPIT or CIQ). The ChAFTA certificate process is the same mechanism used across electronics and other product categories. Request it before the vessel loads; it cannot be backdated.

    Put a number on what that certificate is worth. A container of steel racking valued at AUD 60,000 pays 5% MFN duty (AUD 3,000) if the Certificate of Origin isn’t in hand at clearance. The same shipment with a valid CoO pays zero. Because the certificate can’t be backdated, that AUD 3,000 isn’t a rate you negotiate after the fact; it’s locked in the moment the container clears without the paperwork, and no amount of explaining to the broker afterward recovers it. On a program running several racking containers a year, that’s the difference between a rounding error and a real line item, for one document requested at the wrong time.

    No Anti-Dumping Duties: A Genuine Australian Advantage

    Australia currently has no anti-dumping or countervailing duties on solar panels, inverters, or battery storage from China. This is a structural advantage for Australian solar importers compared to their US counterparts, who face tariff rates of 14.25% to 250%+ on Chinese solar depending on the manufacturer and applicable measures.

    The Clean Energy Regulator and Australian Border Force monitor solar import volumes and have mechanisms to initiate anti-dumping investigations if domestic manufacturing interests file a complaint, but no such measures are currently in force. Check the ABF anti-dumping register before any large volume contract. Conditions can change.

    CEC Approved Products List: What It Means and When It Matters

    The Clean Energy Council (CEC) Approved Products List is Australia’s industry-managed register of panels and inverters eligible for STC (Small-scale Technology Certificate) rebates under the Renewable Energy Target.

    CEC listing is not a customs import requirement. It does not affect whether you can legally import the goods. But it directly affects whether your products are commercially viable in the Australian residential and small commercial solar market. Australian solar installers accredited under the CEC can only use listed products for STC-eligible installations. Installations using non-listed products do not generate STCs. The customer cannot claim the rebate, so you cannot sell the product at competitive prices.

    How to get listed:

    1. The panel or inverter must hold current IEC certification (see below)
    2. The importer or manufacturer applies via the CEC Products Program, not the installer
    3. The CEC assesses the product and grants listing per model
    4. Listing must be renewed if the product specification changes materially

    Plan the CEC application process before or immediately after your first import. New models not yet listed cannot be used for STC-eligible installations. If you have not started early, your first shipment may sit in your warehouse while the listing is processed.

    IEC Certification: The Technical Compliance Layer

    CEC listing requires that panels and inverters hold current IEC (International Electrotechnical Commission) certification from an accredited testing laboratory.

    For solar panels:

    • IEC 61215: design qualification and type approval for crystalline silicon modules. Tests performance durability and degradation.
    • IEC 61730: safety qualification. From 1 May 2026, IEC 61730:2023 (the updated version) is mandatory for new CEC applications. Confirm with your Chinese supplier that their IEC 61730 certificates reference the 2023 standard. The CEC will not accept older editions for new listings.

    For inverters:

    • AS/NZS 4777.2: the Australian/NZ standard for grid connection of inverter energy systems. Updated version (2020) is the current requirement. Inverters must be tested and certified against this standard, not older versions.
    • AS/NZS 61000: electromagnetic compatibility (EMC) requirements.

    Request current, valid IEC and AS/NZS certificates from your Chinese supplier before placing an order. Certificates have expiry dates. A certificate that expired after the last production run creates a compliance problem for new batches.

    EESS Registration: Mandatory for Inverter Importers

    Australia’s Electrical Equipment Safety System (EESS) requires importers of prescribed electrical equipment to register as a Responsible Supplier before placing products on the Australian market. Grid-connected inverters are prescribed equipment.

    Registration requirements:

    • Register your business as a Responsible Supplier in the EESS database (eess.gov.au) with a valid ABN
    • Register each inverter model separately, with supporting technical documentation and test reports
    • The responsible supplier is legally accountable for compliance with the relevant Australian standard
    • Model registration must be current, not a historical registration for a discontinued product

    EESS registration is separate from CEC listing. A product can be EESS-registered without being CEC-listed (meaning it is safe to sell but not STC-eligible), and vice versa (though the latter scenario is unusual). Both are typically required for commercial viability in the Australian solar market.

    ACMA (Australian Communications and Media Authority) also has jurisdiction over grid-connected inverters for electromagnetic compatibility and radiocommunications compliance. Your EESS registration will require ACMA-compliant test reports.
    Shipping Solar Equipment: Handling, Container Choice, and Insurance

    Shipping Solar Equipment: Handling, Container Choice, and Insurance

    Solar panels are heavy, glass-faced, and fragile. How they are shipped matters as much as whether they are compliant.

    FCL is strongly preferred over LCL for panels. Co-loading in LCL means your panels are handled by forklift alongside other cargo, sometimes multiple times between Chinese port consolidation and Australian deconsolidation. Each handling event introduces breakage risk. A 40ft High Cube container holds approximately 1,500–2,000 residential panels (depending on wattage and manufacturer carton dimensions). For any order above 10–12 CBM, FCL is safer and typically cheaper on a per-panel basis.

    Packing specifications: Panels should be palletised in manufacturer cartons, in portrait orientation, with adequate corner protection. Require packing photos and packing lists with carton-level serial numbers from your Chinese supplier. This matters for two reasons: customs clearance at the Australian end (the CER requires serial number reporting for STC claims), and insurance claims if breakage occurs.

    Cargo insurance is essential. A marine all-risk policy covering breakage should be standard on panel shipments. Glass breakage is excluded from standard marine policies unless specifically endorsed. Confirm the policy wording with your insurer before the first shipment.

    Wooden packaging and ISPM 15: Solar panels are typically palletised on treated timber pallets. All wooden packaging must comply with ISPM 15, the international standard for heat treatment or fumigation of wooden packaging material. A fumigation certificate must accompany the shipment. Non-compliant packaging is treated at the importer’s cost on arrival or destroyed. Australia’s biosecurity import conditions apply to the packaging of all imported goods, not just the goods themselves.

    Chinese Manufacturing Hubs and Transit to Australia

    Main manufacturing regions:

    • Jiangsu and Zhejiang provinces: LONGi, JA Solar, Trina Solar, and Canadian Solar production facilities. Export primarily through Shanghai and Ningbo ports.
    • Guangdong province: BYD (battery storage and panels) and other Shenzhen-area manufacturers. Export through Yantian (Shenzhen) and Guangzhou (Nansha).

    Transit times to Australia:

    • Shanghai / Ningbo to Sydney or Melbourne: approximately 16–22 days FCL
    • Yantian (Shenzhen) to Sydney: approximately 14–18 days FCL
    • Add 2–5 business days for ABF customs clearance after vessel arrival

    Australian destination ports: Sydney (Port Botany) and Melbourne are the primary entry points for solar equipment. Brisbane, Adelaide, and Fremantle also handle significant volumes for state-level projects.

    GST of 10% applies to the customs value plus duty plus international freight and insurance. For 0% duty solar equipment, the GST base is essentially customs value plus freight costs. Model this correctly in your landed cost calculation.
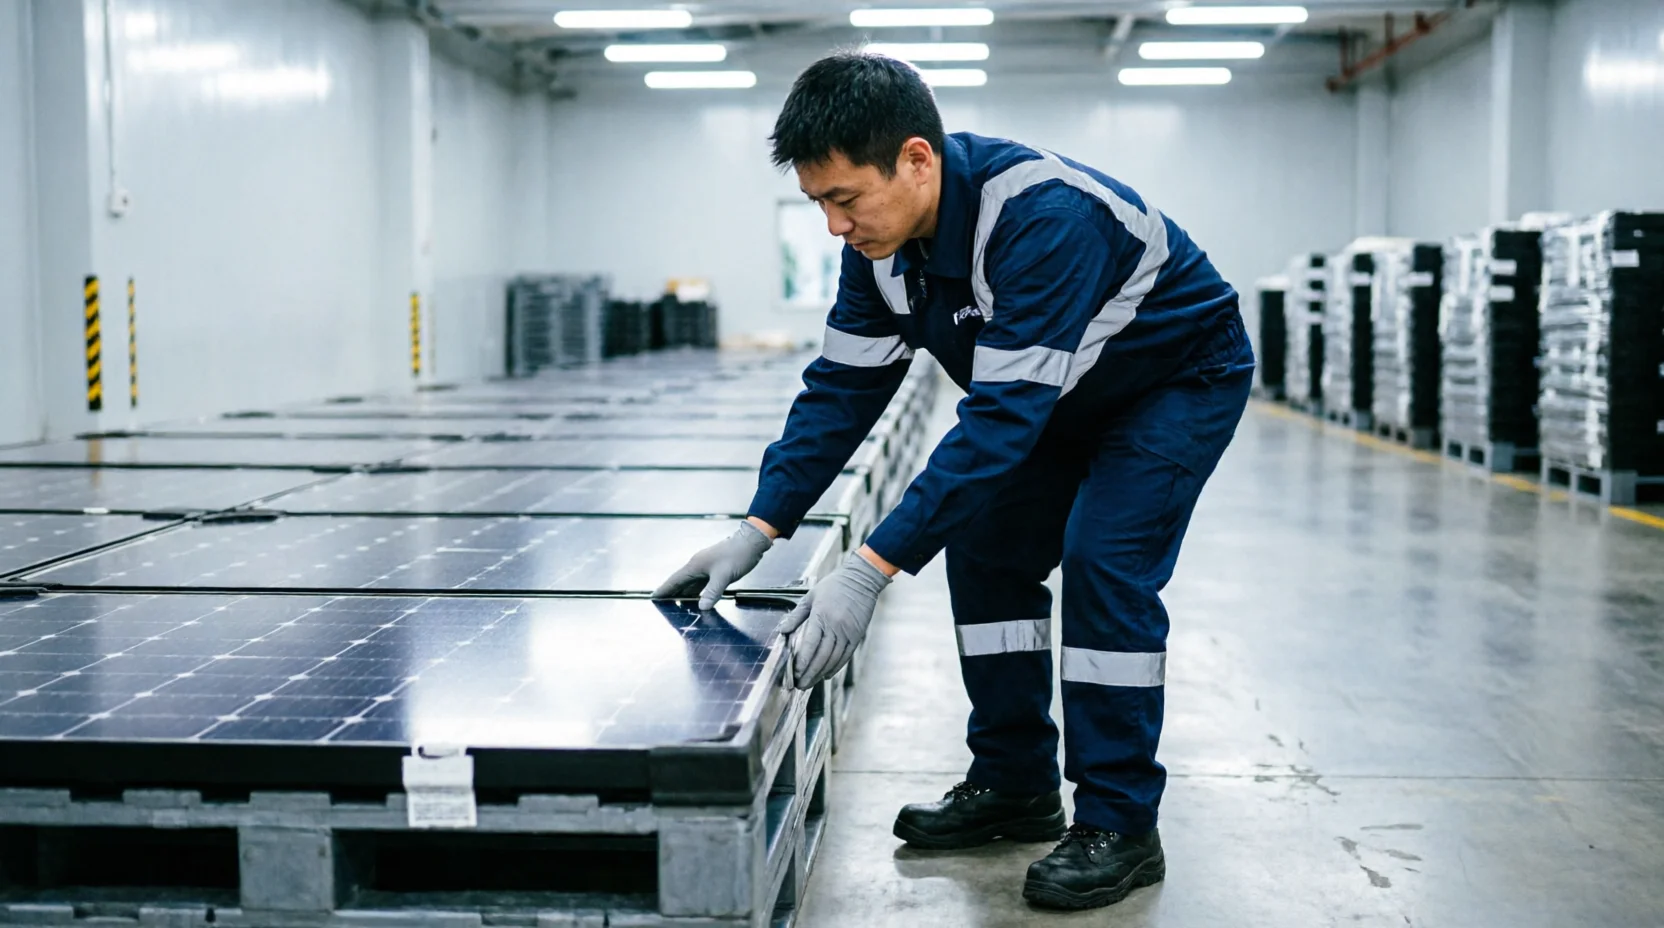
    A warehouse technician methodically checking each solar-panel pallet's protective corner guards along a row before shipment.

    The Import Compliance Checklist

    Requirement Authority When Required
    HS code confirmed ABF Before first import
    ChAFTA Certificate of Origin CCPIT / CIQ (China) Each shipment; for racking at 5% MFN rate
    IEC 61215 + IEC 61730:2023 (panels) CEC / accredited lab Before CEC listing application
    AS/NZS 4777.2 (inverters) CEC / EESS Before EESS registration and CEC listing
    CEC Approved Products listing Clean Energy Council Before STC-eligible sales
    EESS Responsible Supplier registration EESS Before placing inverters on market
    ISPM 15 fumigation certificate (packaging) DAFF Every shipment with timber pallets
    Serial number reporting to CER Clean Energy Regulator For each STC-eligible panel batch
    Marine cargo insurance (all-risk, breakage endorsed) Insurer Every shipment
    Import Declaration ABF (via customs broker) Every shipment above AUD $1,000

    Here is the contradiction worth sitting with. Australia runs anti-dumping cases against Chinese steel, aluminium and glass, yet waves Chinese solar panels in at zero duty. The obvious reading is inconsistency. The more useful reading is that trade policy here is not really about protecting local production. Australia barely makes panels. It is about a decarbonisation target that outranks the protectionist instinct. That tells you something about durability: a 0% duty defended by an emissions commitment is far harder to reverse than one defended by an industry lobby. Import on the assumption the policy holds, but understand exactly why it holds.

    Ready to Import Solar Equipment from China?

    Swift Cargo handles FCL and LCL freight from China to Australian ports, with customs brokerage, ISPM 15 compliance coordination, and cargo insurance guidance. For importers setting up or scaling a solar program, request a freight assessment from Swift Cargo.

    Frequently Asked Questions

    What is the import duty on solar panels from China to Australia?

    Solar panels (HS 8541.40) are classified as semiconductor devices and attract 0% duty under both the general MFN rate and ChAFTA. Inverters (HS 8504.40) and lithium-ion battery storage (HS 8507.60) are also 0% under ChAFTA with a valid Certificate of Origin. GST of 10% applies regardless. Australia does not currently have anti-dumping measures on Chinese solar panels, unlike the United States.

    Do solar panels need to be on the CEC Approved Products List before I can import them?

    CEC listing is not required to import panels into Australia, but it is required for those panels to be eligible for STCs (Small-scale Technology Certificates) under Australia’s Renewable Energy Target. If your customers or installers rely on STC rebates, only CEC-listed panels qualify. Apply for listing via the Clean Energy Council before or immediately after your first import.

    What is EESS and do I need to register as an importer of solar inverters?

    EESS is the Electrical Equipment Safety System, Australia’s national framework for electrical equipment compliance. Importers of grid-connected inverters must register as a Responsible Supplier in the EESS database with a valid ABN and ensure each product model has current registration. Inverters must comply with AS/NZS 4777.2 (grid connection) and AS/NZS 61000 (EMC). Registration is required before the goods are placed on the market.

    Is FCL or LCL better for shipping solar panels from China?

    FCL (Full Container Load) is strongly preferred for solar panels. Panels are fragile: they are typically glass-faced and palletised in manufacturer cartons. Co-loading in LCL introduces additional handling by forklift and other cargo, which increases breakage risk. For any order above approximately 10–12 CBM, FCL is safer and often cheaper per panel. A 40ft HC container holds approximately 1,500–2,000 residential panels depending on wattage.

    Are there anti-dumping duties on Chinese solar panels in Australia?

    No. Australia currently has no anti-dumping or countervailing duties on solar panels from China. This is a meaningful difference from the United States, which applies tariff rates of 14.25–250%+ on Chinese solar imports depending on the manufacturer. Australian importers source Chinese solar equipment without the punitive tariff burden that affects US competitors.
  • HS Code Classification Comes First for Furniture Imports from China to Australia

    HS Code Classification Comes First for Furniture Imports from China to Australia

    China accounts for roughly 35–40% of global furniture exports by value. For Australian importers, that figure reflects something real: access to manufacturing scale, material range, and price points that no domestic supplier can match. Land a quality dining table from Guangdong in Sydney with full duty and freight paid, and it often costs less than the equivalent piece at wholesale in Australia.

    Workers in hi-vis uniforms loading wrapped furniture pieces into a shipping container at an Australian receiving warehouse.

    But the gap between a purchase order and goods in your warehouse is wider than most first-time importers expect. Importing furniture from China into Australia spans five distinct regulatory frameworks: customs classification, trade agreement compliance, biosecurity, environmental law, and product safety. Each has its own documentation requirements, its own penalties, and its own lead times. The good news is that none of it is arbitrary. Every requirement has a logic, and once you understand the system, you can work with it efficiently.

    How to Import Furniture from China to Australia: Business Guide

    HS Code Classification: Start Here

    Before your supplier quotes. Before you book freight. Before your customs broker prepares a declaration. Identify the correct HS code for your goods.

    Everything downstream depends on it: duty rate, biosecurity treatment requirements, BMSB inspection risk, applicable safety standards, and the rate your ChAFTA Certificate of Origin unlocks. Getting the code wrong at the start creates problems at every step after.

    Furniture is classified under Chapter 94 of the Australian Customs Tariff:

    • HS 9401 covers seats of all kinds: chairs, sofas, armchairs, stools, recliners, office chairs, bar stools
    • HS 9403 covers other furniture: tables, desks, cabinets, beds, wardrobes, bookshelves, shelving units
    • HS 9404 covers mattress supports, mattresses, sleeping bags, cushions and similar stuffed furnishings

    The 10-digit Australian tariff item codes within these headings determine the specific duty rate for your product. You can confirm the classification using the ABF Tariff Classification tool or ask your customs broker for a binding tariff ruling before your first shipment.

    ChAFTA Duty Rates: 5% Down to Zero

    The general MFN (most favoured nation) duty rate on Chapter 94 furniture imported into Australia is 5% of the customs value.

    Under the China-Australia Free Trade Agreement (ChAFTA), that rate drops to 0%, provided the goods originate in China and you present a valid Certificate of Origin with each shipment.

    On a $50,000 AUD furniture container, not using a ChAFTA Certificate of Origin costs you $2,500 in avoidable duty. Across a $200,000 annual import program, that’s $10,000 a year.

    To access the 0% ChAFTA rate:

    1. Your goods must meet the ChAFTA rules of origin criteria (broadly, goods wholly obtained or substantially transformed in China)
    2. Your Chinese supplier must obtain a Certificate of Origin from an authorised issuing body in China (typically the China Council for the Promotion of International Trade, CCPIT, or China Inspection and Quarantine, CIQ)
    3. The Certificate of Origin must accompany the import declaration lodged with Australian Border Force

    You can confirm the applicable rate for your specific HS code using the DFAT FTA Portal. The same ChAFTA mechanism applies to electronics imports from China. The certificate process is worth understanding as a routine if you’re sourcing across product categories.

    Don’t assume your supplier will automatically provide the certificate. Many Chinese manufacturers are not accustomed to the requirement or don’t know which Australian importers use FTA preference. Build the Certificate of Origin into your purchase order terms and request it before the vessel loads. It cannot be backdated after the fact.

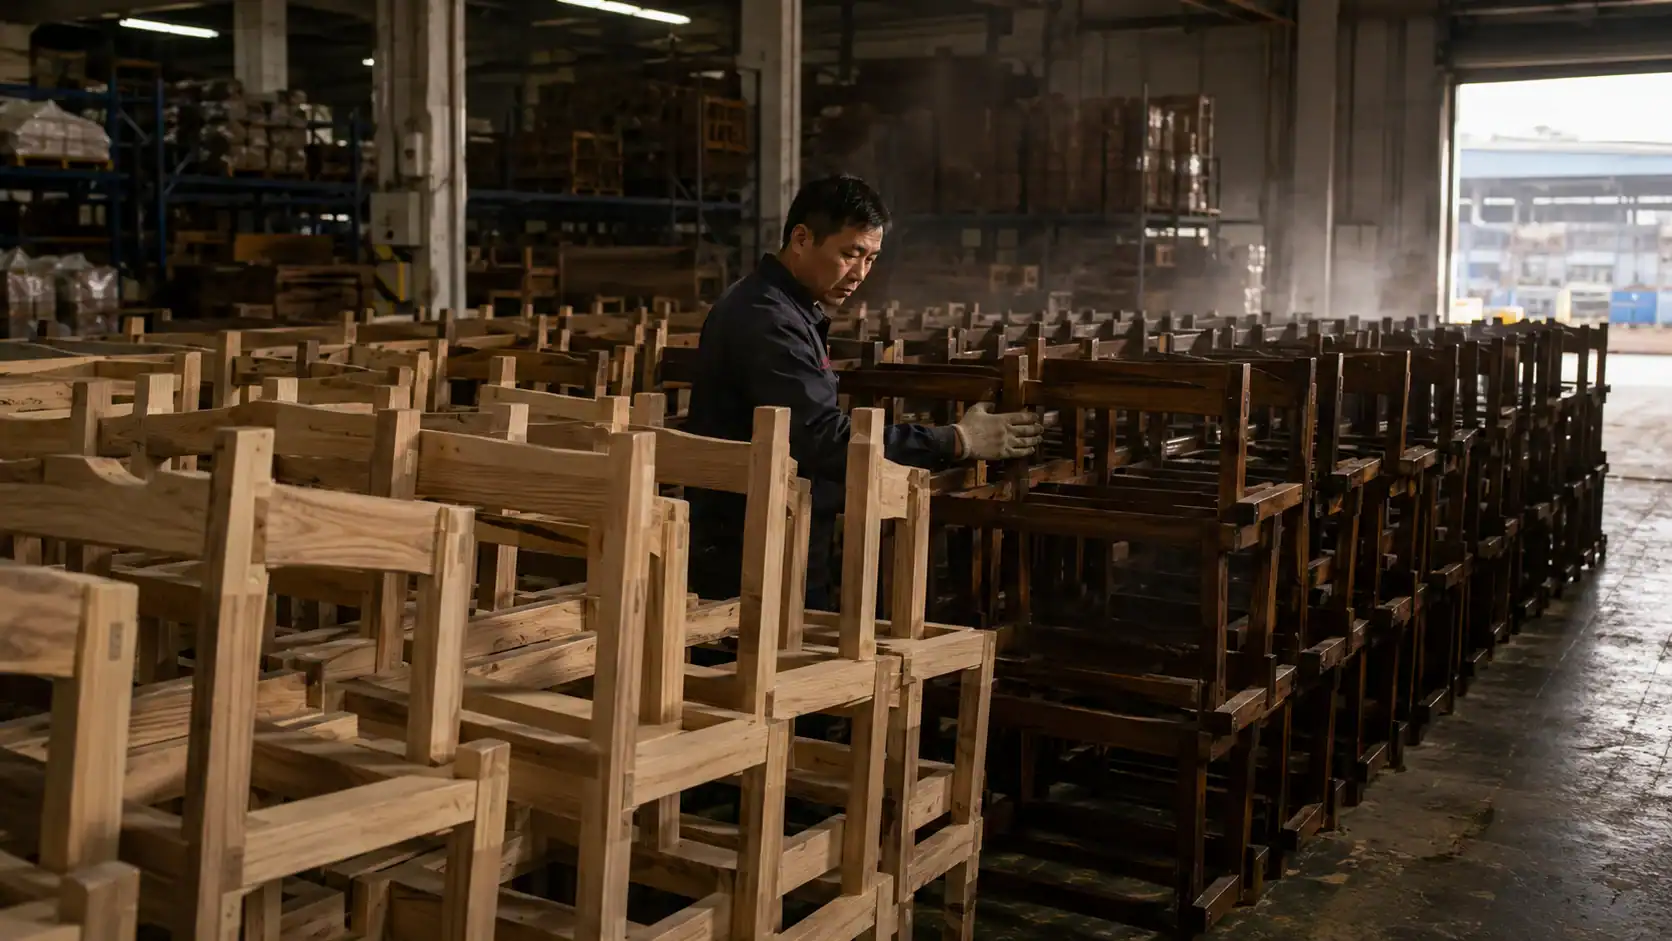
    Factory worker inspecting rows of raw and dark-stained timber chairs in a Chinese furniture warehouse

    Biosecurity Requirements by Material Type

    Biosecurity is the most complex part of importing furniture from China. Unlike duty, the requirements are not uniform: they depend entirely on what your furniture is made from. DAFF’s BICON system is the authoritative source for import conditions by commodity and material. Your broker should check it for your specific goods before the shipment is booked.

    Here is how the major furniture material types are treated at the Australian border.

    Solid Timber Furniture (Highest Biosecurity Risk)

    Solid timber carries the highest biosecurity risk of any furniture material. It may harbour timber borers, bark beetles, Asian longhorn beetles, and other wood-boring pests that would be catastrophic if established in Australian forests.

    Required treatment: heat treatment (core temperature ≥56°C held for 30 minutes), kiln drying to ≤10% moisture content, or methyl bromide fumigation. The treatment must be performed offshore, before the goods load, and documented on a Fumigation Certificate or Heat Treatment Certificate that accompanies the shipment.

    On arrival, DAFF may conduct a physical inspection regardless of the treatment certificate. If live pests are found, the goods are re-treated at the importer’s cost or re-exported.

    Plywood and Engineered Wood (MDF, Particleboard)

    MDF and particleboard carry lower biosecurity risk than solid timber. The manufacturing process destroys most pests. A Newly Manufactured Plywood Declaration is required for plywood: a document from the manufacturer confirming the product is newly manufactured and does not contain reclaimed or recycled timber components.

    Standard MDF and particleboard require a material declaration only. No fumigation certificate is required in most cases. Your broker can confirm the exact requirement for your product specification against BICON.

    Bamboo and Rattan

    Both are classified as plant material, not timber, for biosecurity purposes. A Phytosanitary Certificate issued by the Chinese National Plant Protection Organisation (NPPO) is required, certifying the goods are pest-free. This must be obtained before the goods ship. It cannot be issued retrospectively from Australia.

    Feathers and Down (Upholstery Fill)

    Feathers and down fall into a high pathogen risk category and require a health or treatment certificate. Commercial imports require specific clearance documentation from DAFF. Note that personal imports of feather-filled goods are limited to 10 items. Anything above that threshold requires commercial clearance documentation regardless of the importer’s intent.

    Metal, Glass, Synthetic Materials

    Metal, glass, and synthetic furniture requires no biosecurity treatment, only a standard customs declaration. That holds as long as the piece contains no timber, bamboo, rattan, or natural fill.

    Wooden Packaging: This Applies to Every Shipment

    Regardless of what your furniture is made from, if your goods arrive on timber pallets, in wooden crates, or with timber dunnage, that packaging must comply with ISPM 15, the international standard for treating wooden packaging material.

    Acceptable treatments: heat treatment, methyl bromide fumigation, dielectric heating, or sulfuryl fluoride fumigation. The ISPM 15 mark must be branded or stamped visibly on the packaging. A fumigation certificate must accompany the shipment. Non-compliant packaging is treated on arrival at the importer’s cost or destroyed.

    Australia’s biosecurity import conditions apply to every category of imported goods. BICON is the system to consult for any commodity you haven’t imported before.

    BMSB Seasonal Measures: The Current Window

    Brown Marmorated Stink Bug (BMSB) is an invasive agricultural and structural pest. DAFF has implemented mandatory seasonal treatment measures since 2018, covering the Northern Hemisphere autumn and winter, the period when BMSB populations congregate in goods heading for export.

    The BMSB season runs annually from 1 September to 30 April; the 2026-27 season runs 1 September 2026 to 30 April 2027. DAFF reconfirms the exact window and the approved treatment list each year before the season opens, so check current-season conditions before booking rather than relying on a prior year’s specifics.

    Two separate classifications decide what applies, and conflating them is the most common planning error on this lane. DAFF lists roughly 41 target risk countries, concentrated in Europe, North America and parts of the CIS. China is not one of them: China sits with Japan, the Republic of Korea and the United Kingdom on the emerging risk country list. That distinction decides your obligation. Goods from a target risk country that are on the target high risk goods list need mandatory offshore treatment before shipment. Goods from an emerging risk country do not. Chapters 39, 94 and 95 from emerging risk countries are subject to random onshore inspection instead, and that is the regime that actually applies to Chinese furniture. If a live BMSB specimen is found on arrival, the goods are treated at the importer’s cost or re-exported.

    Offshore treatment is optional on this lane rather than required, and it is worth costing against the delay risk: a container held for random inspection and then directed to on-arrival treatment loses time and money that pre-treatment would have avoided. If you do treat, do it before the goods load in China. Approved offshore treatments in recent seasons have included methyl bromide, sulfuryl fluoride, heat treatment, and ethyl formate. Confirm the current season’s approved list against the DAFF page below before treatment is arranged.

    Goods arriving with a compliant offshore treatment certificate are still subject to random inspection but carry lower risk of being directed to on-arrival treatment. On-arrival treatment delays the shipment and adds cost.

    Fumigation methodology matters: DAFF updated the Methyl Bromide Fumigation Methodology to Version 3.0, effective 1 May 2025, and certificates issued under the older v2.0 methodology stopped being accepted from 30 June 2025. If your supplier is fumigating goods now, confirm they are using v3.0. An outdated-methodology certificate will be rejected at the Australian border.

    Current season details: DAFF BMSB seasonal measures.

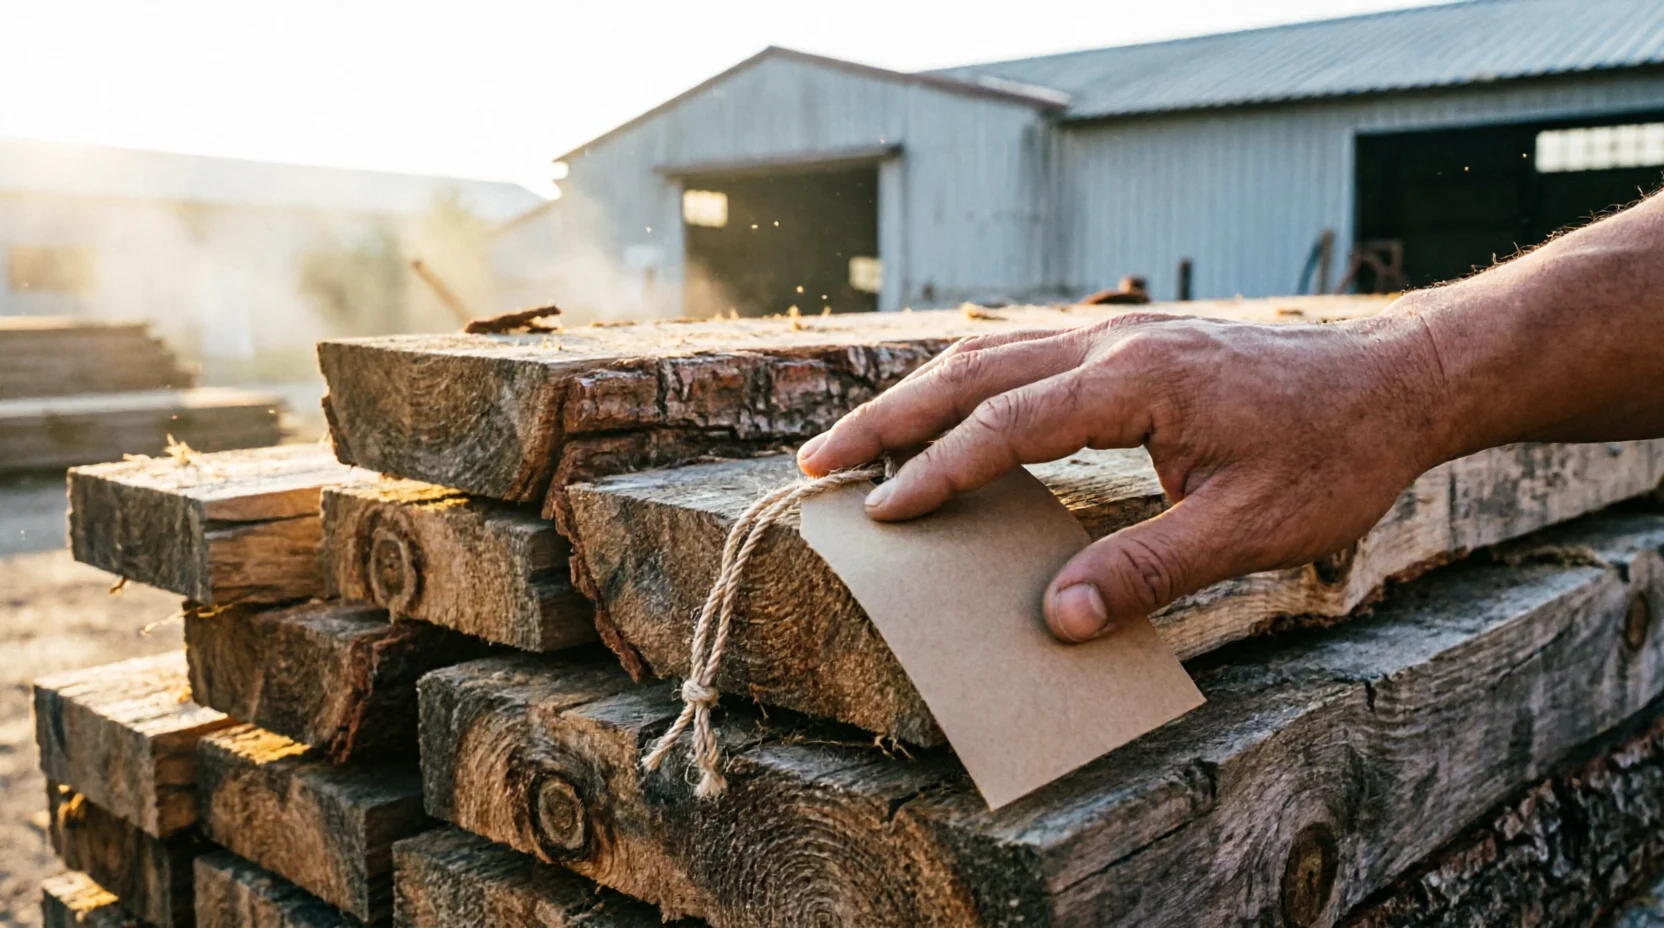
    A stack of raw timber furniture components in a Chinese factory yard, natural bark-edge grain visible on a few pieces, a quality officer's hand resting on a stamped tag tied to one bundle with the tag angled away from camera.

    Illegal Logging Prohibition Act: The Declaration You Cannot Skip

    Australia’s Illegal Logging Prohibition Act prohibits importing timber that was illegally logged. Any furniture containing timber is classified as a regulated timber product under the Act. That includes solid wood, plywood, particleboard, and bamboo.

    For each customs entry, your customs broker must lodge a due diligence declaration confirming that the importer has taken reasonable steps to verify the timber’s legal origin and that all timber components are covered by the declaration.

    The due diligence requirements were strengthened in March 2025. Importers who cannot demonstrate a verifiable timber supply chain face penalties of up to 5 years imprisonment and fines of up to 500 penalty units per offence.

    In practice: request from your Chinese supplier the documentation trail for their timber sourcing. Forestry Stewardship Council (FSC) or Programme for the Endorsement of Forest Certification (PEFC) certification is the clearest evidence of legal origin. Without it, your broker’s declaration relies on supplier statements alone, which carries legal exposure if DAFF investigates.

    Full guidance at: DAFF Illegal Logging Prohibition.

    ACCC Mandatory Safety Standards

    Some furniture categories are subject to mandatory Australian safety standards enforced by the ACCC under the Australian Consumer Law. If you’re importing these goods and they don’t comply, they cannot legally be sold in Australia, and they may be seized at the border or subject to mandatory recall after sale.

    Bunk Beds: AS/NZS 4220 (mandatory)
    Guardrails required on all four sides of the upper bunk. Minimum 260mm clearance between the top of the mattress and the top of the guardrail. Bed slats must be retained without displacement under load. Applies to bunk beds in residential use.

    Household Cots: AS/NZS 2172 (mandatory)
    Specific requirements covering cot dimensions, bar spacing (maximum 85mm), mattress fit, and structural integrity under dynamic load.

    Portable Folding Cots: AS/NZS 2195 (mandatory)
    A separate standard for travel and portable cots, covering folding mechanism safety and sleeping surface stability.

    Bean Bags: Child-Resistant Fastener (mandatory)
    Bean bags must have a child-resistant fastener on the fill opening. Small polystyrene beads pose a choking and suffocation hazard. The fastener must prevent a child under five from opening it without assistance.

    Beyond mandatory standards, all furniture sold in Australia must meet the general consumer guarantee obligations of the ACL: acceptable quality, fit for purpose, and matching its description. Formaldehyde emissions are not subject to mandatory limits in Australia (unlike the EU’s E0/E1 classification system), but pre-shipment formaldehyde testing is prudent for MDF and particleboard goods destined for enclosed residential spaces.

    Current mandatory standards: ACCC Product Safety portal.

    Documentation Checklist

    Your customs broker needs these documents before lodging the import declaration with ABF:

    Document Required when Notes
    Commercial Invoice Always CIF value, HS codes, exporter details
    Packing List Always Must match invoice exactly
    Bill of Lading / Air Waybill Always Original or express release
    Certificate of Origin ChAFTA claims From CCPIT or CIQ; reduces duty 5% → 0%
    Fumigation Certificate Solid timber goods; wooden packaging v3.0 methodology required for start date ≥ 1 May 2025
    Heat Treatment Certificate Solid timber goods (alternative to fumigation) Core temperature ≥56°C for 30 minutes
    Phytosanitary Certificate Bamboo, rattan, plant-based materials From Chinese NPPO before loading
    Newly Manufactured Plywood Declaration Plywood components From manufacturer
    BMSB Treatment Certificate September to April shipments Optional for China (emerging risk country); not mandatory
    Illegal Logging Due Diligence Declaration All timber-containing goods Prepared by your customs broker; importer signs
    Import Declaration Always (goods > AUD $1,000) Lodged by licensed customs broker with ABF

    The table is organised by condition, not by document type. That is a deliberate error-proofing design, not a formatting choice. Most shipment failures on this route don’t come from a document being filled in wrong; they come from a document nobody realised was required in the first place, because “solid timber” or “bamboo component” wasn’t flagged as a trigger condition until the container was already at the port. Read the table by scanning your own bill of materials against the “Required when” column before you book freight, not after your broker asks for a certificate you don’t have.

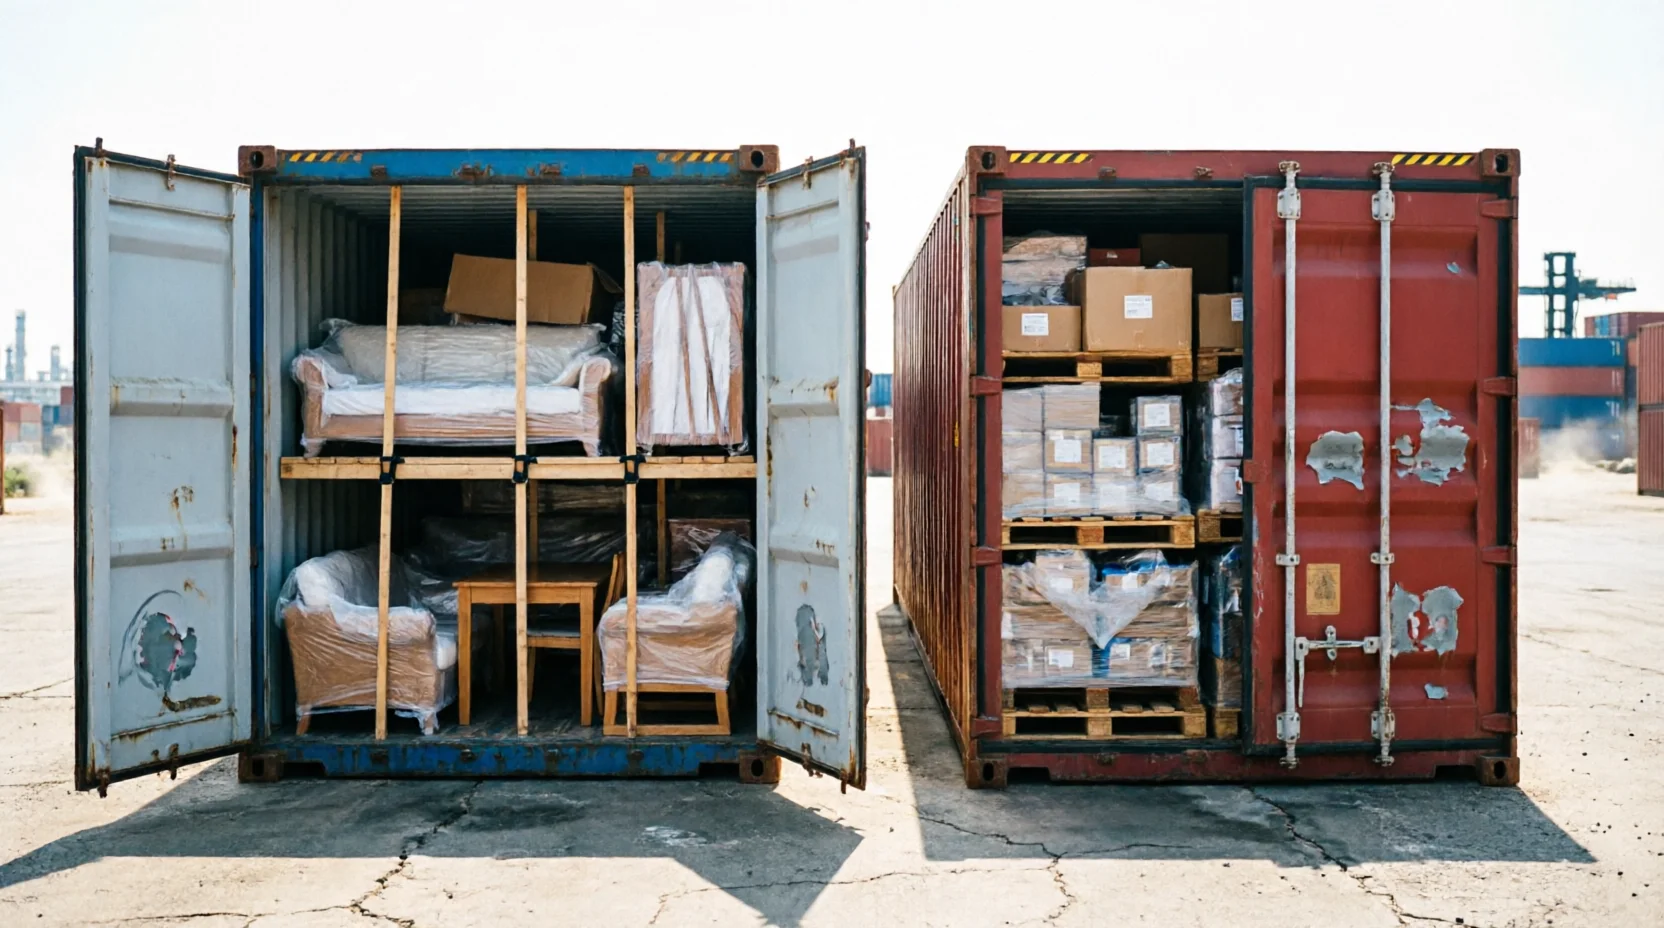
    Two shipping containers side by side at a Chinese export yard, one door open showing furniture pieces wrapped and braced floor to ceiling for a full container, the other partially visible with a shared LCL load of mixed pallets.

    FCL or LCL: Which Shipping Option for Furniture?

    Furniture is bulky. The choice between LCL (Less than Container Load) and FCL (Full Container Load) drives your landed cost per unit.

    LCL means your goods share a container with other importers’ shipments. Cost is charged per cubic metre (CBM). China-Australia LCL rates typically run USD $50–$150 per CBM depending on the port pair and current market rates. It suits shipments under 12–15 CBM.

    FCL 20ft holds approximately 25–28 CBM. FCL 40ft HC holds approximately 65–68 CBM. FCL rates are flat per container regardless of volume used. Current China-Australia FCL rates: approximately USD $1,300–$1,800 for a 20ft, $2,500–$3,000 for a 40ft HC (rates vary with market conditions; get current quotes from your freight forwarder).

    The break-even point where FCL becomes cheaper per CBM than LCL is typically 12–15 CBM. Above that threshold, FCL usually saves freight cost and arrives faster. FCL containers are not consolidated or deconsolidated at origin and destination, which cuts handling delays.

    Transit time, Guangdong ports to Sydney or Melbourne: 20–30 days FCL, 25–40 days LCL. The additional LCL time reflects consolidation and deconsolidation handling at each end.

    The full breakdown of China-to-Australia shipping timelines covers FCL and LCL transit across port pairs in detail.

    It helps to ask why the landed cost breaks down the way it does. A Chinese furniture factory quotes an ex-works price that looks cheap. The expensive parts of the transaction have been pushed downstream onto the importer: biosecurity treatment, ChAFTA documentation, and ACCC compliance testing. That is not an accident of pricing; it is how the supply chain allocates risk. The supplier keeps its quote legible and lets the border absorb the complexity. An importer who reads the quote as the real cost is measuring the wrong number, and the gap tends to surface at exactly the moment the container is already on the water.

    Frequently Asked Questions

    What is the duty rate on furniture from China?

    The general MFN duty rate is 5% on Chapter 94 furniture. With a valid ChAFTA Certificate of Origin, the rate drops to 0%. GST of 10% applies to the combined customs value plus duty plus international freight and insurance. The de minimis threshold is AUD $1,000 FOB value. Goods below this do not attract duty or GST at the border.

    Do I need to fumigate furniture from China?

    It depends on materials. Solid timber furniture requires a fumigation or heat treatment certificate. MDF and particleboard generally do not. All wooden packaging must comply with ISPM 15 regardless. During the BMSB season (September to April), Chinese-origin furniture faces random onshore inspection rather than mandatory offshore treatment, because China is an emerging risk country.

    What is BMSB and when does it apply to furniture?

    Brown Marmorated Stink Bug is an invasive pest. DAFF implements seasonal measures from September through April each year. China is an emerging risk country, not a target risk country, so mandatory offshore treatment does not apply. Chapters 39, 94 and 95 from emerging risk countries face random onshore inspection instead. If a live BMSB is found, the goods are treated at the importer’s cost or re-exported.

    Do I need a licensed customs broker to import furniture?

    For shipments above AUD $1,000 (the formal entry threshold), an import declaration must be lodged by a licensed customs broker. Your freight forwarder can typically arrange customs brokerage as part of the freight service.

    What happens if my timber supplier cannot provide FSC certification?

    Your customs broker can still lodge the Illegal Logging due diligence declaration based on other evidence: supplier statements, country-of-origin documentation, and supply chain records. The legal obligation sits with you as the importer. If DAFF investigates a suspected illegally logged shipment, you must demonstrate due diligence. Without supply chain documentation, that is a difficult position.

    How do I find the right HS code for my furniture?

    Use the ABF Tariff Classification Search or ask your customs broker for a binding tariff ruling. The main headings are 9401 (seats), 9403 (other furniture), and 9404 (mattresses, cushions). Getting this right before shipment avoids reclassification disputes and incorrect BMSB treatment triggers at the border.

    Ready to Import Furniture from China?

    Swift Cargo handles commercial furniture imports from China to Australia: FCL and LCL, with coordination of fumigation documentation, ChAFTA certificate compliance, customs brokerage, and BMSB treatment requirements during the seasonal window.

    Contact Swift Cargo for a freight assessment →

  • Electronics from China to Australia: Duties, EESS, Landed Cost

    Electronics from China to Australia: Duties, EESS, Landed Cost

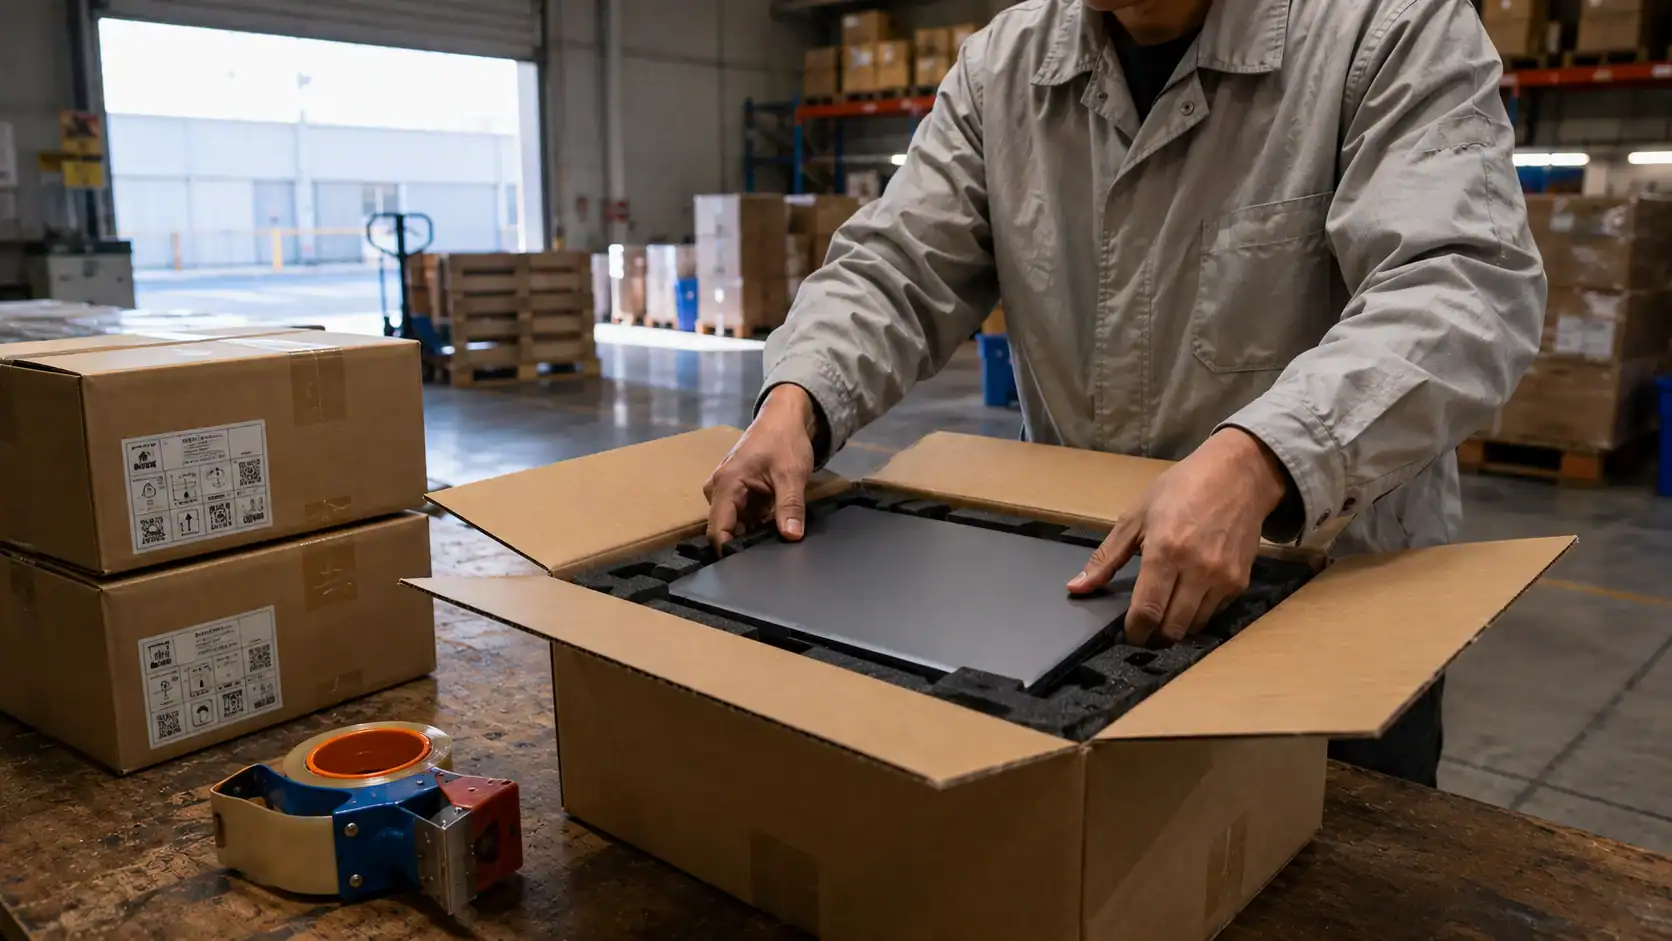
    Electronics (laptops, earbuds, smart devices) being packed into a shipping carton in a Chinese factory or warehouse, with Australian port dock or customs facility visible as a secondary element

    Most Australian importers who run into problems with electronics shipments from China are not caught by complicated regulations. They are caught by a small number of well-documented requirements they did not know applied to them: compliance marks they did not have, certificates of origin they did not request, or duty concessions they did not claim. To import electronics from China to Australia without those surprises, line up three things before the goods arrive: a ChAFTA Certificate of Origin, EESS registration for in-scope electrical equipment, and ACMA compliance for anything with Wi-Fi, Bluetooth or other radio functions.

    Electronics is one of the more straightforward import categories once you understand the compliance stack. Most electronics attract zero duty under the China–Australia Free Trade Agreement. The safety and telecommunications certification requirements are well-defined. The documentation is standard. The problems almost always trace back to doing the prep work after the goods have already shipped, rather than before.

    Key Takeaways

    • Most electronics from China attract 0% import duty under ChAFTA, but you must hold a valid Certificate of Origin from your supplier to claim the preferential rate.
    • GST at 10% applies to all imported electronics regardless of duty rate, calculated on the customs value plus freight and insurance.
    • Electrical equipment operating between 50V–1000V AC designed for household or personal use must be registered under the Electrical Equipment Safety Scheme (EESS) before it can be sold in Australia.
    • Telecommunications equipment requires ACMA compliance, typically demonstrated via the RCM (Regulatory Compliance Mark).
    • Most delays trace to one of four things: a missing Certificate of Origin, no EESS registration, an undeclared value, or an incorrect HS code.

    The Compliance Stack: Which Regulators Govern Electronics Imports

    Electronics imports into Australia do not sit under one regulator. They sit under a stack of them, and different products trigger different layers. Work out which rules apply to your specific goods before you place a supplier order. That prevents most of the delays and rejections that hit importers who try to resolve compliance after the fact.

    The main layers are:

    Australian Border Force (ABF): Handles customs entry, import declaration, duty assessment, and GST collection at the border. Every commercial import above AUD 1,000 requires a formal Import Declaration lodged through the Integrated Cargo System (ICS). ABF assesses duty and GST based on the customs value: the transaction price plus freight and insurance to the Australian border. Source: ABF: Cost of importing goods

    Electrical Equipment Safety Scheme (EESS): Governs the sale of electrical equipment operating between 50V and 1000V AC (or 75V–1500V DC) designed for household, personal, or similar use. This captures most consumer electronics: chargers, cables, power adaptors, smart home devices, lighting, and most household appliances. Importers must register as a Responsible Supplier with the EESS national database before their goods can be sold in Australia. Level 2 and Level 3 equipment must be formally registered; Level 3 requires a Certificate of Conformity. Source: EESS: Steps for compliance

    Australian Communications and Media Authority (ACMA): Governs telecommunications and radio devices. Any product that transmits or receives radio frequency signals must comply with ACMA’s Radiocommunications Act requirements. That covers Wi-Fi devices, Bluetooth equipment, mobile phones, routers, and smart speakers. Compliance is typically demonstrated through the RCM (Regulatory Compliance Mark), which covers both electrical safety (EESS) and electromagnetic compatibility (EMC) in a single mark. Source: ACMA: Supplier labelling requirements

    Therapeutic Goods Administration (TGA): Applies when electronics have a medical or therapeutic function: blood pressure monitors, glucose meters, hearing devices, and CPAP machines. Medical electronics require TGA registration before import and sale, with significant lead time.

    Most business electronics importers sell consumer gadgets, accessories, smart home products, and computing equipment. For them, the relevant stack is ABF + EESS + ACMA. Confirm where your specific product sits in this stack before you ship. How ABF, EESS and ACMA interact with each other is its own topic, one our guide to Australia’s commercial import rules walks through in full.

    Sealed cartons of electronics palletised for import, the point at which duty and GST are calculated

    Duty and GST: What You Owe Under ChAFTA

    The China–Australia Free Trade Agreement (ChAFTA) entered into force in December 2015 and eliminated tariffs on most Chinese goods by 2020. How it applies to your goods determines whether you have a duty liability at all.

    0% duty: Most IT products, computing equipment, and high-technology devices qualify for zero duty under ChAFTA. This includes laptops, tablets, servers, networking equipment, phones, and most HTS Chapter 85 electronics. Australia also participates in the WTO Information Technology Agreement (ITA), which independently eliminates duties on a broad range of technology products. Source: DFAT: Guide to using ChAFTA

    5% duty: Non-IT consumer electronics may attract a 5% general tariff if they do not qualify under ChAFTA or the ITA. That group covers smart home devices, some appliances, and certain audio equipment. Check the specific HS code classification for your product before assuming zero duty applies.

    To claim the preferential ChAFTA rate: Your Chinese supplier must provide a valid Certificate of Origin (COO) confirming the goods were manufactured in China and meet ChAFTA rules of origin requirements. The COO must be issued by an authorised Chinese body, typically the China Council for the Promotion of International Trade (CCPIT) or China Customs. Without a valid COO on file, ABF will apply the general tariff rate rather than the preferential rate. This is one of the most common and most expensive mistakes importers make.

    GST: 10% GST applies to all imported goods regardless of duty rate, calculated on the customs value (transaction price) plus international freight and insurance. Even at 0% duty, a AUD 50,000 electronics shipment carries AUD 5,000 in GST at the border. GST-registered businesses recover this as an input tax credit, but it is a cash flow item that requires planning. Source: ATO: GST on imported goods

    Import Processing Charge (IPC): A flat ABF processing charge applies to formal import declarations. Budget AUD 50–100 for most standard commercial shipments. Source: ABF: Import Processing Charges

    Duty and GST interact differently across import scenarios than many importers expect. Our guide to import duty and GST in Australia breaks down each one.

    Required Documentation for Customs Clearance

    A clean, complete document set separates a shipment that clears in 24 hours from one that sits in an ABF query for a week. For electronics imports from China, the standard set covers:

    Commercial Invoice: Must show the FOB (Free on Board) price, HS codes for each line item, country of origin (China), supplier and buyer details, and a clear description of the goods. Vague descriptions like “electronic components” slow clearance. Specific descriptions help ABF match goods to HS classifications quickly, for example “USB-C laptop charging cables, 65W, 1.8m, Model XYZ”.

    Packing List: Must show quantities, weights (gross and net), dimensions per carton, and a description consistent with the commercial invoice. Discrepancies between the invoice and packing list are a common flag at customs.

    Bill of Lading or Air Waybill: Issued by your freight carrier. The consignee details must match your import declaration exactly.

    Certificate of Origin: Required to claim the ChAFTA preferential rate. Request this from your supplier when you place the order, not when you are booking freight. Chinese suppliers can take 7–14 days to obtain a COO from the relevant authority. The certificate must also be valid at the time of import entry. Leaving it late is a common way to import electronics from China to Australia at the general tariff rate instead of 0%, or to pay port storage while the certificate catches up.

    EESS registration evidence: If you are importing in-scope electrical equipment, have your EESS responsible supplier registration in place before the goods arrive. ABF does not always check at the border. Registration is still required before the goods can legally be sold, and it is cleaner to resolve this before a shipment is sitting in a warehouse.

    Insurance certificate: Required for the customs value calculation if CIF (Cost, Insurance, Freight) terms are used. Recommended regardless. Electronics in transit carry material loss and damage risk.

    Air vs Sea Freight for Electronics from China

    Electronics from China move by both air and sea. The right choice depends on the value density of the goods, the urgency of the order, and the volume being shipped.

    Air freight is the default for high-value, low-volume electronics: phones, laptops, tablets, and precision components. Transit from Shenzhen, Shanghai, or Guangzhou to Sydney or Melbourne typically runs 3–7 days. For goods worth AUD 500 per kilogram or more, the freight cost as a percentage of value stays manageable. For lower-value goods in bulk, air freight economics deteriorate quickly.

    Sea freight is appropriate for larger volumes: bulk accessories, cables, audio equipment, smart home devices, and lighting. LCL (Less than Container Load) shipments run 18–28 days from China to Australian east-coast ports. FCL (Full Container Load) offers similar transit times and becomes relevant when you are consistently shipping enough volume to fill a container. Sea freight typically costs 80–90% less per kilogram than air, which matters for lower-value goods where freight is a large component of landed cost.

    For most business electronics importers starting out, LCL sea freight makes sense for bulk replenishment orders, and air freight for urgent or high-value lines. As volume grows, you move from LCL to FCL once your regular shipment weight exceeds the LCL break-even point, typically around 10–12 CBM. The timing and cost trade-offs across LCL, FCL and air are laid out in full in our guide to shipping timelines to Australia.

    Electronics-Specific Risks in Transit

    Electronics have specific vulnerabilities during sea freight that are worth accounting for in packaging and insurance decisions.

    Moisture and condensation: Ocean containers experience wide temperature swings over a 3–4 week transit, particularly through tropical shipping lanes. Condensation inside packaging can damage circuit boards and connectors. Desiccant packs inside cartons and moisture-barrier bags around individual units reduce this risk.

    Static discharge: Pack sensitive components in anti-static bags, not generic plastic packaging. This is standard practice for component importers but sometimes overlooked for finished consumer goods.

    Physical handling damage: Electronics packaged for retail display are often not packaged for freight. A full sea freight journey covers factory to port, loading, transit, unloading, port storage, customs, and delivery. Products need carton packaging robust enough for that repeated handling. Double-walled outer cartons and proper internal cushioning reduce damage rates.

    Cargo insurance is strongly recommended for electronics shipments. A standard all-risk marine cargo policy covers loss and damage during transit for a cost of roughly 0.3–0.5% of shipment value. For a consignment worth AUD 100,000, that is AUD 300–500 to protect the full shipment value.

    Warehouse worker scanning a barcode with a handheld scanner on stacked cartons on a pallet rack

    Worked Landed Cost Example

    The following example illustrates how to calculate what a shipment of electronics actually costs landed in an Australian warehouse.

    Scenario: 500 units of wireless earbuds, FOB Shenzhen price USD 28 per unit = USD 14,000 total. Shipped by sea freight LCL to Sydney.

    Cost ComponentCalculationAmount (AUD)
    FOB value (goods)USD 14,000 × 1.55 exchange rate (indicative)AUD 21,700
    International sea freight (LCL)Approx 2 CBM at AUD 180/CBM + surchargesAUD 650
    Cargo insurance (0.4%)0.4% × AUD 22,350AUD 89
    Customs value (CIF)Goods + freight + insuranceAUD 22,439
    Import duty0% (ChAFTA, with valid COO)AUD 0
    GST at 10%10% × AUD 22,439AUD 2,244
    Import Processing ChargeABF standard rateAUD 88
    Customs broker feeTypical broker rateAUD 180
    Sydney port charges + deliveryPort THC + last-mile to warehouseAUD 420
    Total landed costAUD 25,371
    Landed cost per unitAUD 25,371 ÷ 500AUD 50.74

    GST is recoverable as an input tax credit for GST-registered businesses. The effective landed cost for a registered importer is therefore AUD 23,127 (AUD 46.25 per unit) once the GST credit is applied.

    This example assumes you hold a valid ChAFTA COO. Without it, a 5% duty on AUD 22,439 adds AUD 1,122 to the cost, a meaningful difference at scale.

    Checking an imported electronic device against its compliance paperwork before it goes on sale

    Common Mistakes Australian Electronics Importers Make

    Not requesting the Certificate of Origin when you place the order. Importers forget the COO request while they focus on product specs and pricing. By the time the shipment is booked, it is too late to get a properly issued COO in time for the import entry. You then pay the general tariff rate rather than 0%, an avoidable cost.

    Assuming ChAFTA covers everything. Not all goods from China qualify. The rules of origin require that goods are manufactured in China and meet specific content or processing criteria. Goods assembled in China from third-country components may not qualify. When in doubt, ask your supplier for their COO supporting evidence before relying on the preferential rate.

    Ignoring EESS registration until after the goods arrive. EESS registration is a prerequisite for selling in-scope electrical equipment in Australia, not a post-arrival formality. If you start registering after the shipment has landed, the goods can sit in a warehouse for weeks before they can legally go on sale.

    Using vague HS codes to simplify the invoice. Some importers classify a mixed electronics consignment under a single broad HS code to reduce paperwork. That increases inspection risk, and ABF may assess the duty incorrectly. Each distinct product type should have its own HS code and its own invoice line.

    Underinsuring or not insuring at all. Electronics have high value-to-weight ratios and material transit damage risk. A single water-damaged carton on a sea freight shipment can be a significant loss. Cargo insurance at 0.3–0.5% of value is one of the lower-cost line items in a landed cost calculation.

    Not building freight time into inventory planning. Sea freight from China to Australia takes 18–28 days in transit plus port processing time at both ends. Importers who plan inventory on supplier lead time alone, without adding freight time, run into stockouts when shipping is delayed. See our guide to biosecurity clearance timelines for the additional buffer needed when goods require DAFF inspection on arrival.

    Swift Cargo handles electronics imports from China for Australian businesses: freight booking, customs documentation, EESS guidance, and delivery coordination. If you are planning your first electronics import or scaling an existing supply line, request a corporate freight quote for a freight assessment.

    The importers who get caught by Chinese electronics shipments almost never lose money on the things they expected to be hard. The duty rates are public, the ChAFTA preference rules are documented, the customs valuation logic is on the ABF website. They lose money on things that look easy until the shipment is already in transit: a model number that triggers a different tariff classification, a battery configuration that pulls the consignment into a dangerous-goods pathway, a brand that lands on a TGA or ACMA review list, an origin claim that needs documentation the supplier did not prepare. Every one of those problems is technically solvable before departure. After departure, the same problems cost ten to fifty times more.

    The pattern most electronics importers encounter on a first commercial shipment is not dramatic. A customs query arrives three days after the vessel docks. ABF is asking for the Certificate of Origin for a consignment of 500 wireless earbud units. The importer calls the Chinese supplier. The supplier says it will take ten days to obtain the COO from CCPIT. The customs entry cannot be finalised without it. The container sits in port storage at AUD 150 per day while the certificate travels. The importer paid nothing in duty under ChAFTA, but paid AUD 1,500 in storage and AUD 300 in redelivery fees to retrieve a cleared shipment they thought was straightforward. The goods were perfectly legitimate. The HS classification was correct. The EESS registration was in order. One document, requested twelve days too late, created costs that the landed cost spreadsheet had never anticipated. Every customs broker handling Chinese electronics imports knows this story in half a dozen variants. Once you have lived through that story, the COO request goes into the purchase order as a checkbox, not an afterthought. That lesson always costs more than the checkbox.

    The two kinds of importer handle the EESS and RCM side of this differently. Most treat compliance as an execution step: pick the cheapest supplier on unit price, then scramble to retrofit certificates once the goods are already on the water. The importers who rarely get held move the work upstream into supplier selection. Before a single carton ships, they ask whether the factory already holds RCM-recognised test reports for this exact model, who owns the responsible-supplier registration, and whether the SKU has been sold into Australia before. That is not extra diligence bolted onto sourcing; it is the sourcing decision. A supplier that cannot answer those three questions is not cheaper. It is a compliance project you have not priced yet.

    Most electronics importers describe their plan as ‘we bring in electronics from China,’ which is not a strategy so much as a market. A real choice names two things: which category you are actually competing in, and what makes your landed cost or your compliance record harder to copy than the next importer’s. An importer who commits to RCM-certified small appliances and builds a repeatable relationship with one compliant factory is choosing a narrower, more defensible position than one who chases whatever category is cheapest to source that quarter. The second importer’s margin depends on price alone, which any competitor with a phone can match. The first importer’s margin depends on a compliance relationship a competitor would need months to replicate. Choosing the category is the strategy; sourcing the cheapest container is just activity.

    What to Confirm Before You Import Electronics from China to Australia

    Confirm the HS code and duty treatment for each product line, request the Certificate of Origin with the purchase order, and have EESS registration and RCM evidence in place for in-scope products before the shipment lands. Then budget 10% GST on the customs value plus freight and insurance, and insure the consignment, which typically costs 0.3 to 0.5% of its value.

    Frequently Asked Questions

    What is the import duty rate for electronics from China to Australia?

    Most IT and high-technology electronics from China attract 0% import duty under the China-Australia Free Trade Agreement (ChAFTA). Some non-IT consumer electronics may attract a 5% general tariff. To claim the 0% preferential rate, you need a valid Certificate of Origin from your Chinese supplier confirming the goods meet ChAFTA’s rules of origin. GST at 10% applies regardless of duty rate.

    What is EESS and does it apply to my electronics import?

    EESS stands for the Electrical Equipment Safety Scheme. It applies to electrical equipment operating between 50V and 1000V AC designed for household, personal, or similar use, which covers most consumer electronics. Importers must register as a Responsible Supplier with the EESS national database before their goods can legally be sold in Australia. Some higher-risk categories (Level 3) also require a Certificate of Conformity before registration.

    Do I need ACMA certification for electronics from China?

    If your electronics transmit or receive radio frequency signals (Wi-Fi, Bluetooth, cellular, or other RF technologies), ACMA compliance is required. This is typically demonstrated through the RCM (Regulatory Compliance Mark), which covers both electrical safety and electromagnetic compatibility. Products without RCM cannot legally be supplied in Australia.

    How long does it take to ship electronics from China to Australia?

    Sea freight from major Chinese ports (Shenzhen, Shanghai, Guangzhou) to Australian east-coast ports typically takes 18 to 28 days in transit. Air freight from the same origins to Sydney or Melbourne runs 3 to 7 days. Port processing and customs clearance add 1 to 3 business days at the Australian end for straightforward shipments.

    What is the Certificate of Origin and why does it matter?

    A Certificate of Origin (COO) is a document issued by an authorised Chinese body confirming that the goods were manufactured in China and meet ChAFTA’s rules of origin. It is required to claim the 0% preferential duty rate at the Australian border. Without a valid COO, the general tariff rate applies. The COO should be requested from your supplier at the time of placing the order, as it can take 7 to 14 days to obtain.

  • AANZFTA Rules of Origin and Duty Claims: What Australian Importers Need

    AANZFTA Rules of Origin and Duty Claims: What Australian Importers Need

    Trade agreements attract a strange kind of wishful thinking. Importers hear that a deal exists between Australia, ASEAN and New Zealand, then assume the agreement itself will somehow make the shipment cheaper. In practice, AANZFTA is useful only when the goods, origin, and paperwork line up tightly enough for the preference to be claimed correctly.

    That is why AANZFTA should be understood less as a political headline and more as an operational instrument. The agreement can create a preferential-duty pathway, but it does not remove the need for correct classification, origin analysis, customs documentation, or biosecurity compliance. Importers who treat it as a broad promise often become frustrated. Importers who treat it as a document-sensitive customs tool usually get more value from it.

    For Australia-bound cargo, the practical question is not “does AANZFTA exist?” It is “can this shipment properly claim AANZFTA treatment, and what evidence will customs expect?”

    Cargo ship and customs documents representing an AANZFTA rules-of-origin certificate claim at an Australian port

    What AANZFTA Actually Does

    AANZFTA creates a framework under which qualifying goods can receive preferential tariff treatment when imported into Australia from participating economies. DFAT and ABF both frame the agreement operationally: it is about how importers claim preferences, how origin is established, and how the agreement works in the actual customs environment. DFAT: AANZFTA overview ABF: free trade agreements

    AANZFTA is not a universal discount on imports from Southeast Asia. It is a structured preference regime. The importer is still dealing with customs law, tariff treatment, and evidentiary expectations. The agreement creates an opportunity. It does not create an automatic entitlement.

    For commercially serious importers, that makes AANZFTA a planning tool. It changes sourcing and landed-cost decisions where the goods genuinely qualify. But it only becomes real value when the preference can be claimed cleanly, defended if questioned, and integrated into the rest of the import file.

    Why Rules of Origin Matter More Than Importers Expect

    Rules of origin are where many trade-agreement conversations stop being casual and start becoming technical. A product shipped from an AANZFTA country is not necessarily an originating good in the agreement sense. It may have been assembled there, repackaged there, or re-exported through that country without actually satisfying the origin criteria required for preferential treatment.

    Customs is not asking where the container boarded. Customs is asking whether the good qualifies as originating under the agreement. The applicable test depends on the product: production history, tariff-shift logic, regional value content, or a commodity-specific rule. Rules of Origin Facilitator: AANZFTA product-specific rules

    This is why importers should not use AANZFTA as a sales talking point before the origin analysis is done. If the commercial team starts budgeting around a preference that later cannot be substantiated, the landed-cost model will be wrong at exactly the moment it needs to be credible.

    The Origin Tests That Actually Decide Eligibility

    AANZFTA uses product-specific rules, which means eligibility is not determined at the agreement level but at the tariff heading level. For most goods, qualifying as ASEAN-origin requires satisfying one of three tests: wholly obtained (the good is produced within ASEAN member states with no non-ASEAN inputs), a tariff change rule (non-originating inputs must shift to a specified HS chapter or heading through processing in the ASEAN country), or a regional value content threshold (a minimum percentage of the good’s value must be added within the ASEAN region). DFAT: AANZFTA rules of origin

    For finished manufactured goods, the tariff change rule is the test most commonly in play. This means an importer needs to understand not just where the product was assembled but where the key input materials originated and whether the manufacturing process in the ASEAN country changes the tariff classification enough. A product assembled in Vietnam from Chinese components that remain in the same HS chapter as the finished good may not satisfy the tariff change rule, and therefore may not qualify for AANZFTA preference regardless of the country of export.

    Importers should not assume AANZFTA eligibility just because they source finished goods from ASEAN factories that draw heavily on Chinese upstream inputs. They should check the specific HS code against the relevant product-specific rule and confirm with the manufacturer what origin evidence is available to support the claim.

    The Specific Tests, Named

    It is worth naming the actual instruments, because the vaguer an importer is about them the more likely they are to accept a supplier’s word as if it were proof. A Product-Specific Rule (PSR) tied to the good’s tariff classification decides AANZFTA origin. For many goods the PSR offers a Regional Value Content test (commonly 40% RVC, meaning at least that share of the value must originate in the free-trade area) or a Change in Tariff Classification test, where the input materials shift HS classification through processing in the exporting country. The PSR schedule, not the exporter’s confidence, decides which test applies.

    The claim itself rests on a valid Certificate of Origin (the AANZ form) issued by an authorised body in the exporting country. The importer holds that certificate at the time they claim the duty preference. This is where accountability quietly shifts. The supplier prints “made in Vietnam” on the invoice. But if a Border Force audit finds the RVC arithmetic does not hold, it is the Australian importer who is pursued for the underpaid duty, penalties, and interest. The exporter who asserted the origin bears none of that exposure. That asymmetry explains why origin claims deserve verification rather than trust.

    Warehouse worker's hands checking a shipping label and packing document attached to a plastic-wrapped freight pallet

    Why Documentation Decides Whether the Claim Survives

    Even where goods genuinely qualify, the claim still lives or dies through documents. Customs needs documentary support that the origin claim is valid and that the importer is entitled to request preferential treatment.

    Invoices, origin declarations or certificates where relevant, product descriptions, tariff logic, and supporting commercial records all matter. If the file is vague, inconsistent, or too thin to explain why the preference is being claimed, the importer has created avoidable risk. The issue is not whether the agreement exists. The issue is whether the claim is documented strongly enough to survive scrutiny.

    Experienced importers treat preference documentation as part of the customs file, not as a side note for the procurement team. The agreement may save money, but only if the evidence is strong enough to make the claim operationally real. For the broader Australian customs framework that surrounds any preference claim, see Australian customs and import services.

    What AANZFTA Does Not Change

    AANZFTA does not dissolve the rest of the Australian border system. It does not remove the need for correct classification. It does not remove GST. It does not remove customs valuation rules. It does not remove DAFF biosecurity controls. It does not solve permit problems for regulated commodities. Australia’s Commercial Import Rules Explained Import Duty and GST Explained for Australia

    Trade-agreement logic belongs inside the bigger import system. A qualifying preference can still sit alongside inspections, treatment, valuation work, or compliance obligations that have nothing to do with the agreement itself. A preferential duty rate and a DAFF treatment order can arrive in the same shipment file. The agreement handles one; the importer still manages the other.

    How to Use AANZFTA Intelligently as an Importer

    • Confirm tariff classification first, because origin and preference logic become meaningless if the product is misclassified.
    • Check the actual origin rule for the goods (tariff change, regional value content, or wholly obtained) rather than relying on broad supplier assurances.
    • Make the preference file part of the customs file, not an isolated procurement note.
    • Model landed cost with and without the preference so the business understands the real exposure if the claim fails.
    • Keep the broader border system in view, especially for goods with biosecurity or regulator sensitivity.

    The classification step deserves particular attention. AANZFTA duty rates are set at the HS heading level, and the gap between two adjacent headings can mean the difference between a 5% rate and a 0% rate, or between a qualifying rate and an exclusion. Importers often delegate tariff classification entirely to their customs broker and never review the rationale. That leaves them exposed: if the classification has been generous in the past and customs disagrees, the preference claim falls with the classification dispute. Independently review the classification before the first shipment of a new product. It is the cheapest form of landed-cost risk management available.

    An independent classification review is cheap; a failed claim is not.

    If your AANZFTA eligibility has never been checked against the actual product-specific rule, that gap is worth closing before your next shipment books.

    Talk to our import team

    Origin Documentation as an Ongoing Capability

    Two competitors can import the same goods from the same ASEAN supplier and still end up with two different landed costs. The difference comes down to whether one company has invested in origin documentation as an ongoing capability and the other has not. Over time that gap compounds. The agreement is public; the discipline of using it well is the actual cost advantage.

    In practice this means maintaining a working HS-code map for your product range. It also means holding supplier origin certificates on file and reviewing them whenever suppliers change production inputs. And it means establishing a standard preference-claim checklist that travels with every shipment file. Some importers redo the origin analysis from scratch on every new SKU and re-request paperwork each time a shipment books. That importer is not using AANZFTA as an advantage. They are experiencing it as a compliance overhead.

    A version of this is worth saying to a customer or a procurement team, not just to yourself: “we claim AANZFTA preference on every eligible shipment, every time, because our origin documentation is standing infrastructure, not a scramble.” Most competitors cannot say that sentence honestly. The ones who redo the analysis from scratch each time either miss claims quietly or claim inconsistently, and inconsistency is the thing a sharp-eyed customer notices before the cost savings ever do. Treat the discipline as a story worth telling, not just a cost line worth capturing. That is what turns a compliance habit into something a buyer remembers you for.

    Calibrating Confidence in the Claim

    Most importers who are aware of AANZFTA believe their goods qualify for preferential duty. Importers tend to feel more confident about that belief than the evidence supports. The rules of origin under AANZFTA are product-specific. They specify transformation processes and regional value content thresholds that determine whether a product is ASEAN-origin for customs purposes. The margin for error is narrower than importers typically assume.

    A supplier asserting ASEAN origin on a commercial invoice has not determined rules of origin. A freight forwarder who has successfully claimed AANZFTA preference on similar goods does not guarantee eligibility on your specific product. The importer bears the risk of a disputed preference claim, not the supplier. The disciplined approach is to run the rules-of-origin analysis specifically for your product and hold your confidence in the claim at the level the analysis actually supports, not the level that makes the landed-cost projection look better on a spreadsheet.

    Readers working through regional sourcing strategy alongside preference claims should see RCEP and Australian Trade and Australia–ASEAN Logistics Strategy for the broader agreement context.

    AANZFTA Is Valuable Only When the Claim Is Real

    The agreement matters, but the real commercial value sits in the claim discipline around it.

    The teams who fail to claim AANZFTA preference are rarely the ones who do not know the agreement exists. What goes wrong is operational. Teams treat origin documentation as a one-shipment problem rather than a permanent capability. They redo it informally at every booking instead of building it once and keeping it current. None of those mistakes look catastrophic in the moment, but over an importer’s annual volume they become the difference between treating AANZFTA as a real edge and treating it as a tariff discount that someone else captures more reliably.

    The most straightforward way to close the gap is to build a one-page preference checklist for each product category: the HS code, the applicable product-specific rule, the required origin documentation from the supplier, and the last date that documentation was confirmed current. That document travels with the product’s purchase order template. It does not require a dedicated compliance team. It requires answering the origin question once and properly, then keeping it current rather than re-answering it informally at each booking.

    We treat your import as a system, not a one-off shipment.

    Most SMEs receive a detailed, all-inclusive quote within 24 hours, no hidden fees, so your landed cost is real before you commit.

    Price your Australia import

    “Our goods qualify for AANZFTA preference” stays an assumption until someone has actually run the rules-of-origin analysis on that specific product. A supplier’s assertion of ASEAN origin on an invoice isn’t a determination. A forwarder’s past success claiming preference on similar goods isn’t a guarantee on yours. The real decision hiding inside “we claim AANZFTA” is how much you’re willing to spend, in analysis time or in specialist fees, to convert a belief into a position you can actually defend if it’s challenged, and that’s a choice with a real cost of being wrong: proceed on an unverified claim and you may owe the duty back with penalties; verify every claim and you’re paying for certainty you sometimes didn’t need. Neither option is free.

    Frequently Asked Questions

    Does AANZFTA automatically reduce duty on goods from ASEAN countries?

    No. The goods still need to qualify under the agreement’s origin rules, and the importer needs to make the claim properly.

    Is the shipping country the same as the origin country under AANZFTA?

    Not necessarily. Customs is concerned with originating status under the agreement, not just where the goods were shipped from.

    Does AANZFTA remove GST or biosecurity requirements?

    No. It can affect tariff treatment, but it does not remove the rest of the customs, tax, or biosecurity framework.

    What is the biggest importer mistake with AANZFTA?

    The most common mistake is budgeting around preferential treatment before origin and documentation have been tested properly.

  • AUD Volatility 2013–2020: What the Currency Cycle Means for Import Planning

    AUD Volatility 2013–2020: What the Currency Cycle Means for Import Planning

    AUD coins or banknotes alongside a long-term currency chart spanning 2013-2020 with visible peaks and troughs

    Currency history matters when it teaches a durable planning lesson. One of those lessons is the Australian dollar’s path from the strong post-boom years into 2020 volatility. It shows that the currency can move through very different regimes depending on macro conditions, commodity drivers, risk sentiment, and crisis pressure. For importers, that matters because budgeting assumptions built in one regime often break badly in another.

    Our companion article on commodity prices and the AUD covers the structural relationship: why iron ore and coal export earnings drive the exchange rate, and what that means for import cost planning.

    Why the peak years created false confidence

    When the AUD was strong, it was easy to treat the currency as a stable backdrop for imports. That kind of period produces bad habits. Companies start assuming the budget environment is normal, they make supplier choices around those assumptions, and the idea that the exchange rate could deteriorate sharply begins to feel theoretical. The lesson of the later cycle is that those assumptions were softer than they looked.

    The post-float high for AUD/USD was approximately 1.10 in mid-2011, driven by the mining boom and strong Chinese commodity demand. By early 2013 the rate had pulled back to around 1.04, still well above long-run averages and still sufficient to make USD-denominated sourcing feel comfortable. The RBA’s exchange rate explainer documents the structural factors behind that strength: elevated terms of trade, high iron ore and coal prices, and a wide interest rate differential relative to the US and Europe.

    In that environment many Australian importers locked in supplier contracts and sourcing relationships priced around rates in the 0.95–1.05 range. The assumption embedded in those contracts was not always explicit; it rarely is. But when you quote a landed cost to a customer or set an internal budget without specifying a currency range, you are implicitly betting the rate stays close to where it is today. That is the soft assumption the later cycle exposed.

    The AUD descent: 2013 to 2020

    The AUD did not fall from 1.04 to 0.57 in a single move. It fell in phases, with partial recoveries between them, which is exactly what makes it a difficult planning problem. Each recovery tempts the importer back into complacency.

    The broad trajectory, drawing on RBA research on exchange rate drivers:

    • 2013–14: AUD falls through 0.90 as commodity prices soften and the US Federal Reserve signals tapering of quantitative easing.
    • 2015–16: AUD falls through 0.80, then 0.70. Iron ore prices drop sharply. The Reserve Bank cuts the cash rate.
    • 2017–19: Partial recovery to the 0.72–0.80 range. Commodity prices stabilise. Some importers treat this as a new floor.
    • March 2020: COVID-19 global risk shock. AUD/USD reaches approximately 0.57 on 19 March 2020, the lowest level since the early 2000s, before recovering sharply as commodity prices held up and global stimulus measures took hold.

    For a business that started budgeting at 1.04 in early 2013, a USD-denominated purchase costing AUD 100 at that rate cost approximately AUD 182 at the March 2020 low. That is not an unusual event in an asset class known for volatility. It is the normal operating range of the Australian dollar under stress.

    Why 2020 mattered so much

    The COVID shock mattered beyond its severity because of its speed. The AUD moved from around 0.66 in late February 2020 to 0.57 in roughly three weeks. Importers with shipments already at sea, with supplier invoices already issued in USD, had no practical hedge available at that point. The exposure had already been taken on.

    In practical terms, this means importers should stop treating exchange-rate stability as a default between shocks. Commodity conditions, global risk events, and local economic expectations can all move the AUD at once, and none of them announce themselves in advance.

    Once you accept that, landed-cost planning becomes more serious and less complacent. Customs value for duty purposes is assessed in AUD at the exchange rate applicable at the time of export, which means currency moves directly affect the duty bill, not just the supplier invoice. The ABF’s customs valuation framework spells this mechanism out.

    How this changes import thinking today

    The useful takeaway is not the chart. It is the range of outcomes the currency has already shown it can produce.

    If the AUD has already shown that it can move from around 1.04 to 0.57 in seven years, with a partial recovery in the middle, then any landed-cost model built on a single exchange rate assumption is thinner than it looks. Run the model at three rates: a base case at current spot (AUD/USD traded near 0.72 in August 2026, having ranged roughly 0.67 to 0.73 across that year), a stress case at the 2020 low of 0.57, and a favourable case at 0.78 to 0.80, a level last sustained in 2021. If the business only works at the base case, that is a risk position that needs to be named and managed, not hidden inside a budget line.

    The three-rate model is really a probability discipline in disguise. Most importers do not ignore the stress case because they think it impossible; they ignore it because they quietly price its probability at close to zero. That is the error. In early 2013 a fall to 0.57 would have looked like a one-in-fifty scenario, the kind of number that rounds to “won’t happen.” It happened inside seven years. Running the model at 0.57 is not an attempt to predict it. It is a refusal to assign a real, recurring outcome a probability of zero simply because it is inconvenient to budget for.

    Think of it the way an insurer prices a policy rather than the way a forecaster predicts weather. An insurer doesn’t claim to know whether your warehouse burns down next year; it prices the premium against the historical frequency of warehouse fires, whatever that frequency turns out to be. A three-rate landed-cost model does the same job for currency exposure: it isn’t a bet on where the AUD goes next, it’s a premium you pay upfront, in the form of slightly more conservative margins and contract terms, against a range the currency has already proven it can occupy. The businesses that struggled hardest through 2013-2020 weren’t the ones with bad luck on timing. They were the ones that had never priced the premium at all, because the stress case felt too unlikely to be worth the discomfort of planning for.

    That affects pricing discipline on customer quotes, the buffer you carry in supplier contracts, and how much value you place on customs timing or shipment flexibility when rates are moving.

    AUD Peak to Volatility 2013-2020: Building a currency buffer for Australia imports

    Building a currency buffer for Australia imports

    A practical buffer predicts nothing. It marks the range your unit economics can survive. The 2013–2020 history gives you a data point: the AUD sat at 1.04 in early 2013 and reached 0.57 in March 2020, a spread of 0.47 across seven years. Most ongoing import businesses need to survive at least one full cycle.

    A workable approach: build your base-case landed cost at current spot, then calculate the same landed cost at 0.68 (the 2015–16 low) and at 0.57 (the 2020 extreme). The gap between the base case and the 0.68 scenario gives you a defensible buffer to hold as margin headroom or to price into customer contracts. If that gap is larger than your current margin, you have a structural problem that no amount of freight optimisation will solve, but at least you can see it clearly.

    Put a number on it. An importer landing USD 100,000 of goods at a base-case spot of 0.72 pays roughly AUD 138,900. Re-run the same USD 100,000 invoice at the 0.68 buffer rate and the landed cost rises to about AUD 147,100. That is an AUD 8,200 swing on a single shipment before freight or duty even enter the calculation. Run it again at the 2020 extreme of 0.57 and the same invoice costs AUD 175,400, nearly AUD 36,500 more than the base case. That gap is not a rounding error to absorb quietly; it is the exact number a pricing model needs to survive, and most importers only discover it exists the year the rate actually gets there.

    The fix costs nothing but arithmetic done in advance. Run your own landed-cost model at 0.68 and at 0.57 before you sign the next supply contract, not after the rate has already moved against you. Price the difference into either your margin or your customer contracts while you still have the choice.

    The ABS international trade price indexes track how import prices move in AUD terms as the exchange rate shifts, which is useful for checking whether your specific import category behaves in line with the broader AUD pattern or diverges due to supplier pricing power or commodity inputs.

    Two things compound currency exposure for Australian importers in a way other import markets do not face. First, the AUD is a commodity-linked currency: it tends to fall hardest during global risk-off events, which are often the same moments when supply chains are under stress and freight costs are rising. So the three headwinds (weaker AUD, higher freight, disrupted supply) tend to arrive together. Second, Australian customs duty is calculated on the AUD customs value, which is the transaction value converted at the ABF ruling rate for the day of export. An importer cannot retrospectively choose a more favourable rate. The date the goods leave the origin port sets the exchange rate for the entire duty calculation. Two identical shipments therefore carry different duty bills if one left Shanghai on 19 March 2020, the day the AUD hit 0.57, and the other left two weeks earlier. Understanding that mechanism is not just historically interesting. It changes how you think about shipment timing when rates are moving fast.

    During periods of AUD weakness, accelerating or deferring shipment timing has genuine value if the rate is moving against you. That is not always possible, because production lead times, vessel schedules and inventory cycles impose their own constraints, but knowing the mechanism means you can at least model the cost of different timing choices before committing, rather than discovering the impact on the customs entry.

    What disciplined importers do with this history

    The right mental model for using a currency cycle is closer to a stress test than a forecast. Importers who try to predict the next AUD turn usually lose money. Importers who instead build pricing models for the full 0.60 to 0.80 AUD/USD range lose far less, far less often, and they do it without breaking margin discipline. Run your current landed-cost model against the historical extremes. If your unit economics fall apart at 0.62, or only hold together above 0.78, you have currency exposure dressed up as commercial strategy. Most teams do the opposite: take today’s rate, apply it forward twelve months, and call it planning. The 2013-to-2020 cycle is a worked example of how badly that habit breaks under stress.

    One more thing the headline number hides. Ask anyone who imported through the 2013 to 2020 window and they will say the dollar was weak, but that framing does unearned work. Against the USD the fall was severe; on a trade-weighted basis it was far milder; against the yuan the story changes again. The yuan is the rate that actually matters if you buy from China. If your supplier invoices in CNY, AUD/USD is a proxy you are using out of habit. The importers who priced most accurately through that window were not the ones who forecast the cycle better, but the ones who modelled the rate they actually paid in.

    Knowing the range makes timing tractable. Buying forward while the rate is temporarily strong, or accelerating a container departure as the AUD softens, both depend on knowing where spot sits inside the historical band: timing decisions on Australian freight shipments interact directly with that exposure.

    Importers planning Australia-bound freight can see how currency exposure fits into total shipment cost at Swift Cargo’s Australia shipping overview.

    Frequently Asked Questions

    Why does the 2013 to 2020 AUD cycle matter to importers?

    Because it shows how quickly the currency environment can move from strength to severe volatility, which directly affects import budgets.

    Is this mainly a macro story or a freight story?

    It is both. The macro cycle matters because it changes the cost environment inside which importers make freight and customs decisions.

    What is the practical lesson for importers?

    Do not assume a favourable currency regime is permanent. Build landed-cost plans that can survive sharper moves; the 2020 low of 0.57 is a useful stress-test floor.

    How does this connect to customs timing?

    Currency volatility becomes more operationally important when customs timing rules can lock in specific exchange-rate effects on shipment value.

  • Skilled Visa Settlement Patterns: Where Freight Demand Appears

    Skilled Visa Settlement Patterns: Where Freight Demand Appears

    The headline numbers are easy to find: 195,000 permanent skilled places in the 2023–24 program, and hundreds of thousands more temporary employer-sponsored visas active at any one time. What those totals hide is geography. Skilled migrants in Australia do not all move to Sydney. Most end up exactly where the visa structure told them to go. State nomination sends them to Adelaide and Perth. Regional sponsorship sends them to Ballarat and Toowoomba. Employer-sponsored visas track to wherever the sponsor operates. The freight demand that follows spreads unevenly in a way the headline number conceals.

    If a logistics planner reads only the national migration figure, they get the timing right and the geography wrong, which is the same as getting it wrong. The visa programme is a logistics signal disguised as immigration policy.

    Skilled Visa Settlement Patterns: Where Freight Demand Appears

    Visa structure and freight geography

    Australia’s SkillSelect system operates through expression of interest rounds. Nomination thresholds, occupation ceilings, and age cutoffs all vary by state. The design is deliberately regional. The federal government has used the program since 2012 to direct skilled migrants away from Sydney and Melbourne and toward states with specific workforce shortages.

    Settlement patterns are therefore structured, not random. South Australia’s nomination quota reached 3,060 places in 2023-24. A surge on that scale produces a predictable cluster of new households in and around Adelaide. A Western Australia occupation list that opens an engineering or healthcare category produces a Perth cluster on the same logic. Logistics businesses that treat Australia as one uniform demand zone miss these clusters entirely.

    Household moves, personal effects consignments, and relocation support follow the settlement geography the visa structure creates.

    Delivery driver in high-visibility workwear unloading a crate from a truck on a new-build Australian suburban street at dusk

    State nomination programs and their settlement effects

    The main skilled migration pathways that drive settlement patterns are the Skilled Nominated visa (subclass 190) and the Skilled Work Regional visa (subclass 491). Both require state or territory nomination. The 190 allows permanent residence in any part of Australia after a two-year commitment to the nominating state. The 491 requires five years in a regional area before permanent residence eligibility under the Permanent Residence (Skilled Regional) visa (subclass 191).

    The commitment periods matter for freight demand. A 190 holder arriving in South Australia will likely have household goods follow within 6–18 months of arrival. A 491 holder settling in a regional area such as Townsville, Geelong, or Darwin will have a similar household arrival profile but a different port and inland delivery requirement. Geelong is close enough to Melbourne port that the inland leg is manageable. Townsville is a different calculation.

    Picture the arithmetic from the receiving end. A container bound for a 491 holder in Ballarat comes off a ship at Melbourne, clears, and then travels a little over an hour northwest on the Western Freeway to a town that has been quietly absorbing regional-nomination families for years. The nurse or engineer who filled that container chose Ballarat because a nomination pointed there, not because a shipping line did. By the time the truck turns into the driveway, the visa decision made eighteen months earlier has become a physical thing: a pallet-load of a life, set down in a place the national migration totals never named.

    According to the Home Affairs migration program report for 2023–24, the state breakdown for skilled stream visas was led by Victoria and NSW but with allocation shifts toward South Australia, Western Australia, and Queensland compared to five years earlier. The distribution shifts every program year as state quotas are renegotiated.

    The employer-sponsored category (subclass 482 and 186) follows a different logic. Settlement tracks to the sponsor’s location. When a mining company sponsors engineers to Western Australia, those engineers arrive at Perth. When aged-care providers sponsor workers in Queensland, the demand follows that corridor. State economies have different sector compositions: mining in WA, agriculture and professional services in SA, construction in Queensland. Those compositions map fairly directly onto which origin countries and which household freight profiles are likely to follow.

    Which cohorts move full households

    Not all skilled migrants move full households, and the distinction matters for estimating freight volume against settlement data.

    The cohorts most likely to ship significant household goods are professionals arriving from established relocation source markets: the UK, Germany, South Africa, India (middle and senior managerial), and Southeast Asia returning expats. These arrivals tend to have 15–35 CBM of household contents, which requires LCL sea freight for smaller volumes and a 20ft container for larger moves.

    The cohorts least likely to ship in bulk are arrivals under working-holiday pathways, international students transitioning to permanent residence (they have been living in Australia for years already), and arrivals from origin markets where sending household goods by air in multiple small shipments is standard practice. These arrivals may generate demand for household goods biosecurity inspection when items do arrive, but the volumes are lower per consignment.

    The visa type does not determine household volume directly, but it correlates with arrival profile, income level at destination, and likelihood of sponsored family migration. Sponsored family migration is often the trigger for the full household shipment. A 482 holder who arrived solo will often ship household goods only once the partner and children follow, typically 6–24 months after initial arrival.

    Shipping container sits open at the kerb outside a suburban Australian home

    Origin country patterns and freight corridors

    The origin country mix of skilled migrants matters because it determines which shipping corridors carry the freight load and what the typical consignment profile looks like.

    India is consistently the largest source country for skilled migrants under the permanent program. Home Affairs data records over 30,000 grants in 2023–24 across skilled stream visas. Indian arrivals tend to ship household goods by sea, often from Chennai or Mumbai, with a mix of LCL consignments and full container moves for larger families. The Melbourne and Sydney corridors absorb most of this volume, though Perth has grown as Indian employer-sponsored arrivals in the resources sector increase.

    The UK remains a significant source, particularly for 190 and employer-sponsored arrivals in professional services and healthcare. UK-to-Australia moves are typically full-container or near-full-container moves. UK households are large, and UK movers are experienced in international relocation. The freight corridor is direct sea freight, typically via Felixstowe or Southampton to Sydney, Melbourne, or Adelaide.

    South Africa produces consistent demand on the Perth corridor, driven by the longstanding SA migration community in Perth and ongoing employer-sponsored arrivals in mining and engineering. South African moves often include vehicles, which adds complexity to the consignment and biosecurity inspection requirements.

    China and the Philippines are significant sources for temporary employer-sponsored visas (482), but they produce lower average household freight volume per arrival than the UK or South Africa cohorts. Two things explain that: the more recent arrival profiles, and the fact that many arrivals have already established a household in Australia through earlier visa stages.

    How settlement patterns become a logistics signal

    Translating migration data into a freight signal takes two steps: identifying where the settlement is going, and estimating the lag between visa grant and household arrival.

    The ABS overseas migration series and Home Affairs visa statistics both publish settlement data. Both carry a 12-month publication lag, so the data available now describes what happened 12 months ago. The forward signal comes from watching nomination quota announcements and occupation list changes, which precede actual arrivals by 18–36 months.

    The lag between visa grant and household goods arrival ranges from 3 to 18 months and varies by origin country and family status. Migrants arriving solo under temporary visas often wait until permanent residence is granted or until family migration is approved before shipping household goods. Arrivals under 190 or 186 (permanent from day one) tend to ship sooner, often within 6 months of settling into a property.

    Confidence layers in migration data

    National net-migration totals: high confidence. The ABS overseas migration series reports quarterly. The direction holds for 12–24 months and is reliable enough for medium-range planning.

    State-level settlement splits by visa category: medium confidence. Home Affairs publishes cohort data with a one-year lag, and the split shifts when policy changes. Regional nomination quotas have changed twice in the last five years. The state-level picture is directionally useful but not precise for quarter-specific planning.

    Quarter-specific city-level demand timing: low confidence. The three-to-eighteen-month grant-to-arrival gap already noted is too wide to pin demand to a particular quarter, and it varies by origin country and family status. An operator who treats all three layers as equally reliable ends up overconfident on timing and underprepared for geographic variance. The appropriate response is not more data. It is a clearer view of which layer is driving the planning decision.

    Logistics manager beside a regional map pinned with clustered colour markers

    What strong operators do with this information

    Strong operators align route focus, service readiness, and capacity planning around where migrants are actually going rather than where the business vaguely hopes demand will appear.

    In practical terms, this means tracking state nomination quota announcements (published each program year by Home Affairs), watching ABS regional population data for settlement trend confirmation, and building partner relationships in second-tier cities (the Adelaide, Perth, and Brisbane corridors) rather than assuming all volume funnels through Sydney and Melbourne port infrastructure.

    For incoming shipments to Australia, the relevant operational questions include timing against biosecurity inspection requirements and inland delivery to the actual settlement destination, which is often not the port city. A consignment arriving at Port of Melbourne for a migrant settling in Geelong has a different inland leg than one destined for Carlton. Settlement data makes that inland planning more honest.

    The gap compounds when a settlement cluster is discharge-side invisible. A state-nominated cohort settling in the Adelaide Hills, for instance, still clears at the same South Australian port as a Adelaide-CBD shipment on paper, but the actual last-mile leg runs materially longer and carries different access constraints for a large container than an inner-city delivery does. An operator planning capacity purely off port-level throughput sees no difference between those two consignments; an operator planning off settlement data sees the inland-leg gap coming months in advance, while there’s still time to price it and staff for it rather than absorb it as an unplanned cost on delivery day.

    For quotes and cost estimates on Australian inbound shipments, the Australian shipping cost overview provides current volume thresholds and price ranges by origin. For the full customs and biosecurity process, the Australian shipping process guide covers documentation requirements, inspection timelines, and port options.

    Settlement pattern data is only useful if it connects to a specific operational question. The ABS migration series, the Home Affairs visa grant breakdown, and the state-and-territory population release each answer a different question at a different level of resolution and lag. The ABS quarterly migration total answers “how many,” with a 12-month lag. The Home Affairs state breakdown answers “where,” with a 12–18 month lag. The nomination quota announcements, which precede arrivals by 18–36 months, answer “where it is going.” Using all three as if they answer the same question produces confident forecasts on the wrong time horizon. The correct use is sequential: quota announcements shape 2–3 year capacity planning; settlement data confirms or corrects 12-month corridor assumptions; current booking patterns calibrate the immediate quarter. The discipline is holding those three layers apart rather than collapsing them into a single “migration is strong” summary. A logistics business that manages that has what it needs to decide where to build capacity before the freight pressure appears.

    Frequently Asked Questions

    Why do skilled visa programs matter to logistics businesses?

    Because they determine where migrants settle, and settlement patterns shape relocation and freight demand. A national visa total tells you volume; state-level settlement data tells you geography.

    Does state nomination affect where freight demand appears?

    Yes. State nomination directs migrants to specific states, and the 2–5 year commitment periods mean those migrants will generate household freight demand in that state rather than in Sydney or Melbourne. The effect is predictable and observable in ABS data.

    Why is settlement data more useful than national migration headlines?

    Because it translates migration into actual geographic demand. National figures tell you the Australian market is growing. Settlement data tells you which ports, cities, and delivery corridors to prioritise.

    What is the biggest planning mistake with migration data?

    Treating demand as nationally uniform. Skilled migrant settlement is structured by visa design. It clusters in predictable locations based on nomination, employer, and regional program mechanics.

    How long is the lag between visa grant and household goods arrival?

    Typically 3–18 months, varying by visa type, family status, and origin country. Permanent residence visa holders (190, 186) ship sooner. Temporary visa holders (482) often wait until permanent residence is approved or family migration follows.

  • RCEP and Australian Trade: What Changes for Importers

    RCEP and Australian Trade: What Changes for Importers

    RCEP entered into force for Australia on 1 January 2023, bringing 14 Asia-Pacific trading partners under a single preferential framework: all ten ASEAN members plus China, Japan, South Korea, and New Zealand. Together those economies account for roughly 30% of global GDP. For Australian importers sourcing across that region, the agreement does not guarantee cheaper shipments. It changes the preference environment, the rules-of-origin logic, and the planning questions worth asking. For businesses buying regionally, RCEP is not just a geopolitical acronym. It is part of the operating context.

    RCEP works alongside AANZFTA for trade between ASEAN members and Australia. For the specific rules of origin mechanics, tariff schedules, and Form AANZ documentation under AANZFTA, see our detailed guide to AANZFTA rules of origin.

    RCEP and Australian Trade: What Changes for Importers

    What RCEP actually does

    RCEP standardises rules of origin across the bloc. Under most bilateral agreements, each pair of countries had its own origin test. Under RCEP, one standard test applies consistently across members: either 40% regional value content or a change in tariff classification. That matters because it enables cumulation: inputs from any RCEP member can count toward origin when calculating whether a product qualifies. A Vietnamese garment maker using Chinese fabric and South Korean thread can still produce goods that qualify for RCEP preference when exported to Australia, provided the combined value-add meets the threshold.

    Tariff elimination schedules vary by member and product category. For goods from China, most tariff lines phase to zero over schedules running 9 to 15 years, with some sensitive categories excluded. For ASEAN members with whom Australia already had AANZFTA coverage, RCEP often provides a parallel or overlapping preferential rate. Importers can choose which agreement to claim under on a shipment-by-shipment basis. The obligation is to select one and document it correctly, not to use RCEP exclusively.

    Claiming the preference requires a valid Certificate of Origin. Self-declaration is permitted for shipments below a threshold value; larger consignments require a CO issued by an approved body in the exporting country. The ABF free trade agreements guide sets out what Australian customs requires at the border to accept a preference claim.

    Why the agreement should not be romanticized

    Trade agreements are easiest to misunderstand when importers treat them as automatic commercial wins. RCEP is no exception. It can improve the preference environment and influence sourcing decisions, but the benefit is conditional. The goods have to qualify under the rules of origin. The documentation has to support the claim. The tariff line has to be one that RCEP covers at a rate better than the MFN rate. Importers who treat the agreement as a blanket cost reduction tend to overstate its value and then discover at customs that the claim cannot be supported. Importers who treat it as a structured opportunity tend to use it more effectively. They check qualification product by product and supplier by supplier.

    RCEP also does not simplify the wider compliance picture. Australian importers still face ABF duty assessments, GST, biosecurity requirements, and product-specific import conditions that operate independently of any trade agreement. The preference only affects the tariff rate on qualifying goods. RCEP status does not change anything else: total landed cost, biosecurity clearance, inland delivery.

    How RCEP changes sourcing logic

    The cumulation rules are the most strategically significant part of RCEP for Australian importers. Pre-RCEP, an importer sourcing components from multiple ASEAN countries might find that a finished product failed the origin test for bilateral agreements because inputs crossed too many borders. Under RCEP, inputs from any of the 15 members can count toward origin. That can change the economics of regional manufacturing: a supplier who previously failed the bilateral origin test for Australian preference might now qualify.

    That affects where importers should be sourcing and which suppliers are worth developing. If a Chinese manufacturer can incorporate ASEAN inputs and still hit the 40% regional value content threshold, the preference window opens. If a Vietnamese factory was previously excluded from preference because it used too much non-ASEAN input, that may now have changed. The practical implication is not that every supplier relationship needs restructuring immediately. It is that origin qualification is now worth re-examining for key product categories, particularly those with MFN rates above 5%.

    A pattern in RCEP adoption looks paradoxical until you understand the incentives. The companies most likely to benefit are often the slowest to actually claim preference: established importers running consistent regional sourcing programs. The companies that move fastest are smaller, newer entrants who have less to lose from getting the documentation wrong. Incumbent importers have existing broker relationships, fixed compliance workflows, and a quarterly cost target that nobody rewards them for disrupting. Restructuring origin documentation across hundreds of SKUs takes operational energy that nobody on the incumbent side has been told to spend. The smaller competitor has no legacy workflow to disrupt. Over five years that asymmetry compounds, and the incumbent finds itself paying a higher landed cost than newer rivals on the same SKUs from the same ASEAN suppliers. The agreement is public infrastructure. The cost of not using it is privately distributed.

    An Australian customs broker reviewing a preference-claim document at a warehouse office desk, a small stack of shipping folders beside a laptop with the screen and papers both angled away from camera, morning light through a window catching dust in the air.

    Why customs discipline still decides the outcome

    RCEP only matters commercially when the customs claim is real. Origin discipline, product classification, and documentary quality still decide whether the agreement changes the border outcome. The ABF applies the same scrutiny to RCEP preference claims as to any other preferential claim: the CO must be valid, the HS code must match, and the origin evidence must support the claim. An invalid claim results in duty assessed at the MFN rate plus potential penalties for misdeclaration.

    This is why RCEP belongs inside the customs and landed-cost model, not only inside a boardroom strategy slide. The practical value emerges only when the shipment file can support it. For most importers, that means three things: confirming HS classification before ordering rather than at clearance; requiring origin documentation from suppliers as a standing condition of purchase, not a last-minute request; and briefing the customs broker on RCEP eligibility for each product line so that preference claims are lodged consistently rather than opportunistically.

    Most importers treat trade agreement preferences as a one-time documentation exercise: submit the form, attach the certificate of origin, capture the reduced rate, move on. That is the first-order benefit. The compounding benefit is different. Some importers build systematic RCEP origin documentation, commodity by commodity and supplier by supplier. They end up with a preference-claim capability that a competitor entering the same markets five years later cannot easily replicate. Not because the agreement is complex, but because the operational muscle of doing it correctly for every consignment takes time to build: supplier relationships that include origin documentation as a standing requirement, internal classification work that happens before the purchase order rather than at clearance, broker briefings that cover preference eligibility as routine. The importer who treats RCEP as an ongoing capability rather than a per-shipment checklist ends up not just cheaper on individual shipments, but structurally harder to dislodge.

    What importers should do with this

    The starting point is a product-level preference audit. Pull the top 20 imported product lines by duty spend and check each one against the RCEP tariff schedule for its origin country. For lines above 5% MFN, confirm whether the goods qualify under RCEP rules of origin. If they do, quantify the annual duty saving, verify that the supplier can issue the required CO, and instruct the broker to claim from the next shipment. That is a two-to-four-week exercise that often produces measurable savings with no supply chain changes required.

    The next step is to compare RCEP rates against AANZFTA rates for the same goods. On some lines, AANZFTA gives a better rate; on others, RCEP does. Because importers can choose the agreement per consignment, there is no reason to default to one. The broker should be checking both schedules for any new product category.

    RCEP’s real value over time is not the headline tariff saving on any individual shipment. It is the way the agreement lets a disciplined importer treat the region as one planning surface rather than a patchwork of bilateral relationships. Some importers map origin qualification, regional value content, and CO documentation across a supplier base. They see the regional cost structure more clearly than those still working product-by-product through a series of bilateral agreements. That integrated view is where the structural competitive advantage lives: one origin map, one documentation discipline, one routing logic. The agreement is just paperwork. The advantage is in the operating model built around it.

    For context on how misdeclared preference claims are treated at the Australian border, see our guide to Australian import compliance mistakes and how to avoid them. For background on the agreement and Australia’s full tariff schedule, see DFAT: RCEP and the ABS international trade goods series for current trade flow data by origin country. For pricing and logistics on Australia inbound freight once goods are ready to ship, see Australian customs and import procedures.

    Forklift moving a plastic-wrapped freight pallet through a warehouse loading dock, with other wrapped pallets lined up along a row of dock doors

    The Six-Figure Line Item Nobody Wants to Own

    Here is the part that should bother more finance directors than it does. Take an importer bringing in AUD 2 million a year of a single product line from China at a 5% MFN rate. That is AUD 100,000 in duty, every year, sitting on the landed cost. If that line qualifies for RCEP or AANZFTA preference and the rate drops to zero, the whole AUD 100,000 disappears. The work to capture it is a two-to-four-week project for one competent person: classify the goods, confirm origin, get the supplier to issue the Certificate of Origin, brief the broker. Nobody would turn down six figures a year for a fortnight of admin. And yet importers do, constantly.

    The interesting question is not why this happens. Diffuse savings against concentrated effort explains most of corporate inertia. The interesting question is why RCEP specifically gets ignored more than other savings of the same size. My guess: it sounds bureaucratic, and bureaucratic-sounding things get filed under “someone else’s job” by default, even when the someone else does not exist. If a trade agreement matched the energy of a new sales channel, more finance directors would ask about it in the same meeting they ask about anything else that moves six figures. It doesn’t, so they don’t, and the money stays on the table for exactly as long as nobody reframes the question.

    Why? Because the saving is diffuse and the effort is concentrated, and no one’s bonus depends on it. The compliance analyst who could run the audit is busy clearing this week’s shipments. The procurement lead is measured on unit price, not duty recovered. The broker lodges what the client instructs and is not paid to volunteer a preference the client never asked about. So the money stays on the table, not because the agreement is hard, but because the org chart has no owner for it. Larger importers sourcing heavily from China are frequently the worst offenders, precisely because their volumes make the unclaimed duty largest.

    The importers who do capture it treat it as a standing line item, not a project. And the cumulation rules make the audit worth repeating: a Vietnamese supplier that failed a bilateral origin test on non-ASEAN inputs may now clear the RCEP threshold on the same bill of materials. Run the numbers once a year across the top duty-spend lines and the exercise pays for itself many times over. Skip it, and you are quietly subsidising your faster competitors.

    A Certificate of Origin costs nothing to request and takes one email to chase. That is the entire distance between a supplier’s invoice and a customs duty bill that drops to zero on a qualifying line. Most importers treat origin documentation like a formality the broker sorts out if there is time, rather than the one piece of paper standing between the MFN rate and the RCEP or AANZFTA rate. It is usually the cheapest request an importer will ever make relative to what it is worth. If the ask costs one email and the payoff is a permanent rate cut on every future shipment on that line, the only defensible default is to ask every time, on every eligible line, rather than treating the certificate as optional paperwork nobody quite owns.

    Frequently Asked Questions

    Does RCEP automatically lower import costs into Australia?

    No. Goods must qualify under RCEP rules of origin, and the preference claim must be supported by a valid Certificate of Origin. For qualifying goods, RCEP reduces or eliminates the tariff rate applied at the Australian border, but GST, biosecurity levies, and other charges are unaffected.

    Can Australian importers use RCEP and AANZFTA on the same goods?

    Not on the same shipment. You must claim under one agreement per consignment. You can compare the rates and choose the better one. Some product lines are more favourable under AANZFTA; others under RCEP.

    What is cumulation and why does it matter?

    RCEP cumulation means that inputs from any of the 15 RCEP members can count toward origin. This makes it easier for goods manufactured across multiple ASEAN countries to meet the origin threshold. That is more flexible than most bilateral agreements.

    What documentation does the ABF require to accept an RCEP preference claim?

    A valid Certificate of Origin from an approved issuing body in the exporting country, or a self-declaration for low-value shipments.

    Does RCEP cover services or only goods?

    RCEP includes chapters on services and investment, but the tariff preference mechanism applies to goods. Most Australian importers engaging with RCEP will be focused on the goods schedules and rules of origin.

  • Australia Migration and Freight Demand: Why Surges Reshape Shipping

    Australia Migration and Freight Demand: Why Surges Reshape Shipping

    Australia’s net overseas migration totals have run above 500,000 per year in recent peak cycles. That is enough to shift freight demand around relocation services, personal-effects shipments, and settlement logistics. Migration statistics can feel remote from shipping until you remember what a surge in arrivals actually means in physical terms: people moving households, businesses repositioning staff, students entering housing markets, and settlement corridors absorbing a sharp increase in move volume. That physical demand is where migration data becomes relevant to logistics operators.

    Australia Migration and Freight Demand: Why Surges Reshape Shipping

    Why Australia’s recent migration surges matter

    Australia’s recent migration numbers have been large enough that they should not be treated as background demographics. ABS data on net overseas migration shows that population inflows can accelerate sharply across consecutive quarters, and when they do, they affect more than housing headlines. They change how many people are trying to settle, how many goods are moving, and which metropolitan corridors feel the greatest pressure.

    The Home Affairs migration program report breaks down arrivals by visa category: skilled, family, and humanitarian. That breakdown matters because different visa cohorts produce different freight profiles. Skilled visa holders relocating from the UK, Europe, or North America tend to arrive with more household goods than student cohorts. Family stream arrivals often trigger secondary household consolidation moves. International students typically ship little or nothing on arrival, then move a modest personal-effects consignment when departing. Each category generates a different demand signature. Treat them as a single “migration” figure and the shape of demand comes out wrong, even when the headline total is accurate.

    The post-pandemic migration rebound produced one of the sharper freight-demand inflections on record for the Australia inbound corridor. Two things drove it: the skilled-visa backlog clearing and international student enrolments resuming. Household goods services reported material increases in lead times during 2022–2024 as that backlog cleared. That inflection was visible in ABS migration data twelve months before it fully showed up in freight booking volumes.

    How migration demand shows up physically

    Migration-driven freight demand does not arrive as uniform waves of container imports. It shows up in clustered forms: household moves, personal effects shipments, and time-sensitive settlement support, all concentrated around the cities and states where new arrivals are landing. Sydney and Melbourne absorb the majority of skilled-visa arrivals; Brisbane and Perth have grown as secondary corridors. The big national number matters less than where the pressure concentrates and what shipment type that concentration generates.

    For international relocation shipping to Australia, migration surges show up as tighter lead times, higher demand for LCL consolidation services, and port congestion at Botany and Fremantle during peak settlement periods. Those periods are typically Q3 and Q4, when a large share of skilled visa arrivals resolve their household goods decisions. Personal effects cleared under the ABF household goods concession add volume to this window without adding commercial cargo data. That is why the surge can feel sudden to operators who are not tracking migration data as a leading indicator.

    The ABF concession sets a hard timing requirement that migration surges interact with directly: to qualify for duty-free entry on used household goods, the importer must have owned and used the goods for at least 12 months prior to arrival, and must have permanently departed their previous country of residence. The biggest personal-effects freight demand from any migration cohort tends to lag the arrival date by six to twelve months. The shipment follows once people have settled an address, confirmed their residency status, and arranged the move. For operators, that lag creates a second wave of demand roughly one to two shipping seasons after the visible arrival surge.

    DAFF biosecurity inspection also becomes a bottleneck during migration surges. High-volume quarters at Botany and Fremantle mean longer inspection queues for used household goods, which carry higher biosecurity risk than new goods, so DAFF officers intervene more often. Operators who ship into peak migration settlement periods should account for extended DAFF biosecurity clearance times and for the higher probability that goods will be directed to a treatment facility rather than cleared on the dock.

    Australia Migration and Freight Demand: Why Surges Reshape Shipping: Which origin corridors generate the most freight demand

    Which origin corridors generate the most freight demand

    Not every origin country in Australia’s migration mix produces equivalent freight demand. The UK, India, China, and the Philippines consistently rank among the top source countries for permanent and long-term arrivals. UK and European arrivals typically generate the highest household goods volumes per person. They are more likely to be owner-occupiers with established households rather than younger skilled workers who have spent several years in furnished rentals. Indian and Chinese skilled migrants are the largest cohorts by number. Average shipment size per person is smaller, but the total freight volume those cohorts generate is substantial at scale.

    This is not a ranking of which nationalities move more. It is a description of which origin-to-Australia freight corridors carry the highest household goods volume per arrival. A surge in UK skilled-visa approvals translates more directly into Felixstowe–Botany LCL demand than a comparable surge in student visas from South-East Asia. Both matter to the Australia inbound corridor, but they show up differently: the UK cohort in household goods, the student cohort in personal parcel shipments at departure rather than arrival.

    Tracking Home Affairs visa grant data by country alongside ABS migration totals gives a more useful operational picture than either source alone. Visa grant data is published regularly and is leading: it shows approvals before arrivals occur. Three inputs are enough to build a 12-month forward demand view with reasonable confidence: visa grant data, the ABS quarterly release, and a simple model of household goods incidence by visa category.

    Why this matters for planning

    Logistics operators can treat migration waves as an early warning system for where relocation demand and settlement-related freight pressure are likely to intensify. This does not mean every migration surge produces the same freight outcome. The operator watching migration patterns can see why certain routes, services, or support categories are heating up. That visibility lets them respond before the congestion appears rather than after.

    Pre-booking freight capacity ahead of confirmed individual demand requires justifying a decision that looks wrong in the short run: committing resources to demand that has not yet arrived as a specific booking. The visible cost of pre-positioning is immediate. The cost of being under-capacity during a surge disperses across dozens of individual shipments and never appears on a single line of a freight P&L. That asymmetry between visible and invisible cost is a framing problem, not a data problem.

    State-level data sharpens the planning picture. ABS state and territory population figures show which corridors are absorbing arrivals fastest. When Victoria and Queensland both record above-trend migration, pressure on Melbourne and Brisbane freight capacity compounds. When NSW is the primary absorbing state, Botany-origin LCL services and Sydney-area removals operators are the first to feel it. Monitoring at the state level converts migration data from a background indicator into an operational input.

    What disciplined operators do differently

    Disciplined operators connect migration data to actual shipment categories and geography. They look at where arrivals are clustering, which visa cohorts are most likely to need freight support, what cargo categories those moves generate, and which service commitments will become harder to keep if pressure rises suddenly.

    In practice, this means keeping three layers apart: what is known with high confidence (ABS migration totals, published quarterly with small revisions), what can be inferred with moderate confidence (settlement corridor preferences, which correlate with historical patterns but shift when policy changes), and what is genuinely uncertain (which specific cities will see surge demand in the next two quarters). Collapsing those three layers into a single confident forecast is where planning errors originate.

    The cost of being wrong about settlement-driven freight demand is paid in surge pricing, last-minute capacity, and over-promised lead times. A migration-aware quarterly checklist costs an hour and removes most of those surprises. It cross-references the most recent ABS release against current booking patterns for the Australia inbound corridor.

    Migration policy and freight capacity planning run on the same timeline, but entirely separate teams watch them. Policy analysts track visa grant volumes; logistics operators track booking patterns and current lead times. Australia’s skilled visa intake is published quarterly with specific occupation-and-state breakdowns. That is enough granularity to map directly onto corridor and service categories for freight planning. The migration program is not just a demographic signal. It is a forward logistics commitment, expressed in visa grants before it ever becomes a booking. Most operators wait for the booking pressure to arrive. The ones who act twelve months earlier have already secured the capacity those operators will later be unable to find at any reasonable rate.

    Migration waves are old; the data advantage is new

    Australia has absorbed migration surges before. The post-war assisted-passage program moved more than a million migrants between 1945 and the early 1970s, and the ships that carried them also carried household freight in volumes the wharves of the era struggled to clear. The 1980s intake from Southeast Asia reshaped demand again, this time concentrated in Melbourne’s west and Sydney’s southwest rather than spread evenly across the capitals. Every wave has followed the same sequence: a policy decision, a visa pipeline, arrivals, and then a delayed surge of personal-effects freight. What has changed is visibility. A 1950s removals firm learned about an assisted-passage cohort when the ship docked. A 2026 operator can read the equivalent signal in a quarterly Home Affairs dataset a year ahead of the booking. The pattern is a century old; the lead time is the only genuinely new resource, and it remains largely unused.

    Why the Biggest Movers Are Often the Slowest to Respond to a Surge

    When a migration wave hits, the largest, most established relocation and freight operators are frequently the ones least able to respond quickly, not because they lack the trucks, the containers, or the staff, but because their entire operating model is built to run efficiently at a predictable, steady volume. A surge is precisely the kind of demand a steady-state model is designed to smooth away rather than absorb.

    A large operator optimises its scheduling, container allocation, and staffing roster around minimising idle capacity. Spare trucks and unbooked container slots are a cost on the books every day they sit unused, so the incentive is to run lean. That is the correct decision in a normal month. It becomes the wrong one the month a visa category expands and a wave of new arrivals all need shipping capacity inside the same eight-week window. The operator’s own success at running lean is exactly what leaves it unable to flex when flexing is what the market suddenly needs.

    The operators who do capture a genuine surge tend to be smaller or newer, not because they are better at the core logistics (the large operators usually still are), but because they were never big enough to optimise slack out of their model in the first place, or because they deliberately chose to hold some capacity in reserve and price it for exactly this kind of moment. Reading migration data early is only half the advantage. The other half is a capacity model built to use what the data is saying, instead of one engineered to run at its most efficient precisely in the months the surge is not happening.

    Migration demand does not arrive as a smooth trend a forecaster can extrapolate from last year’s average. It arrives as a policy announcement in a source country, a visa-class change, or a currency shock, and then a surge that shows up in booking data six to ten weeks later, all at once. A freight operator who plans capacity against a rolling average is planning for a world that migration does not actually produce. The operators who never seem caught out are the ones who treat every quiet quarter as a coiled spring rather than a stable baseline, and who keep spare capacity relationships in reserve specifically because the next surge, when it comes, will not look like the last one and will not give six months’ notice.

    Frequently Asked Questions

    Why does migration affect shipping demand?

    Because migration produces household moves, personal-effects shipments, and settlement-related freight demand concentrated around specific urban corridors. Different visa cohorts produce different freight volumes and timing profiles.

    Does every migration increase create the same freight effect?

    No. The impact depends on where arrivals cluster and what visa categories are involved. Skilled migrants relocating from Europe or North America generate materially different freight volumes and timing than student cohorts or family stream arrivals.

    Why should a logistics business watch migration data?

    Because it acts as a leading indicator of where relocation demand and delivery pressure may intensify. ABS releases migration figures quarterly. That gives operators 12–18 months of visible lead time, provided they read the figures at the state level and cross-reference visa grant data by country.

    What is the biggest planning mistake here?

    Treating migration as a demographic headline rather than translating it into freight geography and specific shipment categories. National totals are less useful than state-level corridor data broken down by visa cohort and adjusted for the typical six-to-twelve-month lag between arrival and personal-effects shipment.

  • Importing Medicines and Medical Devices into Australia: TGA Compliance and Logistics

    Importing Medicines and Medical Devices into Australia: TGA Compliance and Logistics

    Medicines and medical devices move through the same freight channels as any other cargo, but they sit inside a stricter regulatory layer: TGA therapeutic-goods rules, and in some cases additional licensing through the Office of Drug Control. A shipment that physically lands in Australia is not automatically usable. It is usable only if it lands under a pathway that makes it lawful to supply or use.

    Importing Medicines and Medical Devices into Australia: TGA Compliance and Logistics

    Why Therapeutic-Goods Imports Are Not Ordinary Freight Jobs

    The issue is not only that the goods are sensitive. It is that their lawful importation, supply, or use may depend on a regulatory position that has to be clear before the shipment is treated as routine. If the product is not in the right legal posture, fast logistics does not solve the problem. It only makes the problem arrive sooner.

    The distinction between personal importation and commercial importation matters here too. Under the TGA personal importation scheme, individuals can import a three-month supply of medicines for personal use without ARTG registration. Commercial importers do not have that option. Every supply pathway must be confirmed against the ARTG or an applicable exemption before the shipment moves. TGA: Personal Importation Scheme

    Why TGA Matters So Much

    For many therapeutic goods, the TGA governs how they can be imported, supplied, or handled within Australia. For importers, that means the freight plan cannot be the leading logic. Importers have to understand the regulatory position first. TGA: Importing Therapeutic Goods

    Central to that regulatory position is the Australian Register of Therapeutic Goods. Most medicines and medical devices intended for supply in Australia must be entered on the ARTG before they can be lawfully imported for commercial purposes. The importer’s first question should be whether the product has an ARTG entry, and if not, which exemption or approval pathway applies. TGA: Australian Register of Therapeutic Goods

    Therapeutic-goods shipments can be time-sensitive, and time pressure is exactly when sequencing gets skipped. The regulatory check then gets deferred past the point where it still protects the shipment.

    In some situations, additional controls outside the TGA layer matter too. The Office of Drug Control governs imports of drugs of dependence and other controlled substances. Those requirements sit alongside the TGA framework, not inside it. ODC: Import Requirements

    Importing Medicines and Medical Devices into Australia: Where Logistics Meets TGA Compliance: Why You Need an Australian Sponsor Before You Can Import

    A foreign manufacturer cannot put its own product on the ARTG and ship it to an Australian buyer without an intermediary step most first-time importers miss. Only a sponsor can apply to have a therapeutic good included on the ARTG. A sponsor is an individual or company resident or incorporated in Australia, and it carries legal accountability for the product’s quality once it is on the Australian market. Freight and customs guidance aimed at importers routinely skips this step because it sits upstream of the shipment itself, but ABF and TGA both expect it resolved before the goods move, not discovered at clearance. TGA: Role of the Sponsor

    For an overseas factory with no Australian entity, this means finding a local sponsor before the ARTG application can even be lodged, not after the goods are built. Some importers act as their own sponsor by incorporating in Australia; others engage a regulatory affairs consultancy that already holds sponsor status for multiple overseas manufacturers. Either way, the sponsor relationship has to be settled at the same stage as supplier selection, because the freight timeline cannot get ahead of a regulatory role nobody has assigned yet.

    Medical device importers and distributors carry a separate obligation on top of the sponsor question: a valid Medical Device Establishment Licence (MDEL) covering the specific activity of importing, distributing, or both. The MDEL sits alongside ARTG inclusion rather than replacing it; a business can hold a clean ARTG entry for the product and still be non-compliant if the entity actually moving the goods does not hold its own MDEL. The licence is entity-specific, not product-specific, so a change of importer or distributor partway through a supply relationship can mean reapplying even when nothing about the device itself has changed. TGA: Importing and Supplying Medical Devices

    The device’s own risk classification changes how much work the sponsor has to do before inclusion is even possible. The TGA classifies medical devices into Class I, IIa, IIb, III, and AIMD by risk and invasiveness. A Class I device typically needs only a manufacturer’s self-declaration of conformity. A Class IIb or Class III device needs conformity assessment certification for both the manufacturer and the specific device design before the ARTG will accept it. A shipment of Class III implants planned on a Class I timeline is a scheduling error built in from the start. TGA: Medical Device Classification

    A freight forwarder can move the shipment, but cannot act as the sponsor and should not be asked to. Confirm who holds sponsor responsibility and MDEL coverage before the booking is confirmed, not as a question that surfaces during customs clearance.

    Why Customs and TGA Logic Must Be Integrated

    A common error is to treat customs as the border layer and the TGA as something to think about later. The two have to cohere, and the customs classification is where that shows up first.

    Many medical devices attract a 0% duty rate under Schedule 3 of the Customs Tariff Act. Chapter 90 covers instruments and apparatus for medical, surgical, dental, or veterinary use, including several subheadings with preferential or nil rates. But the classification has to be correct. A mis-classified medical device may attract a higher duty rate and be flagged for inspection. ABF: Tariff Classification

    The cost of getting this wrong has real numbers attached to it, not just delay. Goods detained without a valid import authority give the importer 28 days to produce evidence of a lawful pathway before ABF can order them destroyed. A separate penalty of up to AUD 2,500 under the Customs Act 1901 applies to the unauthorised import itself. On the other side of the ledger, an ODC import permit for a controlled substance typically clears within 10 business days when the application is complete, occasionally extending toward the 20-day standard under heavier demand. That timeline fits inside normal production lead times if the application goes in when the purchase order is placed, not after the shipment has already landed.

    Why Documentation Quality Is Decisive

    Documentation matters here because therapeutic-goods imports are a category where vague language is especially dangerous. The file needs to reflect what the product actually is, what its regulatory status is, and what pathway supports the import. A weak file creates doubt where certainty is required.

    In regulated categories, documentation quality is not clerical polish. It is part of whether the product can move through the system without preventable friction. Import documents are a record of what you knew and when you knew it. Every permit, every TGA approval reference, every chain-of-custody declaration is part of that record. When something goes wrong at the border, the paper trail is what the ABF officer is going to read.

    What Strong Importers Do Differently

    Strong importers map the TGA position before the shipment moves, build the freight file around the regulatory reality, and use logistics providers who understand that urgency is not a substitute for a lawful, document-clean shipment.

    • Confirm the product’s regulatory footing before committing to freight urgency.
    • Ensure customs and therapeutic-goods documentation describe the same commercial reality.
    • Surface permit, licensing, or pathway issues early enough to influence the shipment plan.
    • Avoid vague paperwork on high-stakes goods.
    • Use urgency carefully. Speed is valuable only when the legal and documentary base is already clean.

    Internal coordination matters here too: the consignee side has to be ready for the goods under the same assumptions. A legally valid import plan can still become messy if the receiving side expects a different product status or handling pathway. That gap is rarely visible until the shipment is already in transit.

    For shipments involving Australian customs documentation requirements more broadly, the Australian customs documentation overview on the Swift Cargo service page covers the standard import file stack.

    A pattern stands out in who finds this category manageable. Established therapeutic-goods importers treat each consignment as cheap because the expensive work was paid for long ago and is reused on every shipment: TGA pathway mapping, documentation templates, broker relationships, sponsor arrangements. A newcomer faces all of that cost on consignment one, priced against the margin of a single order. The economics predict the behaviour: incumbents ship routinely while first-time importers either underprepare or walk away, and neither response is careless. Each is an answer to a different cost structure. The practical implication for a new entrant is to rent the incumbent’s infrastructure rather than rebuild it. An experienced broker and a forwarder who runs regulated freight lanes turn a fixed setup cost into a per-shipment fee, which is exactly the trade a low-volume importer should want.

    Readers who need the wider border-rule stack should move to Australia’s Commercial Import Rules Explained. Readers thinking about the cost side should see Import Duty and GST Explained for Australia. For urgency-sensitive consignments, How Airport Cargo Capacity Affects Urgent Shipments covers airfreight constraints that affect time-critical medical goods.

    Why TGA Problems Usually Surface Too Late to Fix Cheaply

    When you look at how these shipments actually go wrong, it’s rarely because nobody in the business knew the TGA rule existed. It’s because the person who knew the rule and the person who placed the order were two different people who never had the conversation before the purchase order was already signed.

    This is a familiar shape in any regulated function: procurement optimises for price and lead time, because that’s what they’re measured on. Compliance optimises for getting the paperwork right, because that’s what they’re measured on. Neither one is wrong to focus on their own number. The problem is that for therapeutic goods, the two decisions need to happen at the same moment, not in sequence: what to buy, and whether it’s legally importable in that specific form. Most businesses’ actual workflow puts them in sequence by default, and compliance finds out once the order already exists.

    The fix is a small process change, not a bigger compliance team. Before any purchase order for a medicine or medical device goes out, one question gets answered first: is this specific product, in this specific form, already on the ARTG, or does it qualify under a personal-importation or special-access pathway instead? That’s a five-minute check against a public TGA database. Asked five minutes before the order, it’s a formality. Asked five weeks after the shipment lands, once the goods are already sitting in a bonded warehouse while the business works out whether it can legally take delivery, it’s a genuine crisis. Same question, same database, wildly different cost depending only on when it gets asked. The businesses that get this right did not hire more compliance staff. They just moved the question earlier.

    The regulatory weight that makes therapeutic-goods imports slow also does the compliant importer a favour that is easy to miss. A low-margin competitor cannot simply undercut an established TGA sponsor on price, because the sponsor relationship, the ARTG listing, and the audit trail behind them take months to build and cannot be copied by matching a quoted rate. That is a genuine barrier to entry, not just red tape: it keeps a category that looks commodity-like from behaving like one. The importer who treats sponsorship and registration as sunk cost to get through, rather than as the asset that keeps casual competitors out, is undervaluing the one advantage this category actually offers. The friction is the moat, not a tax on it.

    Frequently Asked Questions

    Why are medicines and medical devices different from normal imports?

    Because they sit inside a therapeutic-goods regulatory framework that can add legal conditions beyond customs and freight requirements. The TGA determines whether the product can be lawfully imported and supplied. That determination has to precede the logistics decision.

    Can fast logistics solve a weak regulatory position?

    No. It can make the problem more expensive and more visible, but it does not resolve it. A shipment that arrives before the regulatory pathway is clear creates storage and compliance costs that move faster than the fix.

    Why does documentation matter so much here?

    Because customs and therapeutic-goods compliance both depend on accurate product identity and a clear legal pathway. Vague documents create doubt at exactly the point where the ABF and TGA processes require certainty.

    What is the biggest importer mistake in this category?

    Treating therapeutic goods as if they were ordinary freight with a more urgent delivery requirement. The regulatory layer is not an add-on to the logistics plan. It has to shape it from the start.

  • Australian Fresh Produce Exports: Market Access and Phytosanitary Rules

    Australian Fresh Produce Exports: Market Access and Phytosanitary Rules

    Fresh produce feels simple because it is physically familiar. Commercially and regulatorily, it is one of the least simple categories in trade. Freshness does not make a product export-ready. The shipment only becomes real when the destination market’s import conditions, phytosanitary expectations, and documentary pathway have been matched.

    That is why the strongest exporters treat fresh produce as a market-access system first and a freight job second. If the certificate route is weak, if the destination-market conditions are misunderstood, or if the timing sequence does not respect perishability, the cargo can be packed beautifully and still fail commercially.

    This is what makes produce different from slower, more forgiving categories. Mistakes are not only compliance mistakes. They are value-destruction mistakes. The product can lose saleability while the exporter is still trying to repair the paperwork.

    Australian Fresh Produce Exports: Market Access and Phytosanitary Rules

    Why Fresh-Produce Exports Are Really Market-Access Systems

    The common mistake is to think the product quality itself will carry the shipment. In reality, produce quality is only one part of the outcome. The export becomes commercially viable only when the destination market can admit the goods under the right official pathway.

    That is why produce exports are better understood as market-access systems rather than as cold-chain jobs with extra paperwork. The buyer may want the product. The freight provider may be able to move it. But if the market-access side is weak, the shipment is still vulnerable. That vulnerability usually appears too late, after time-sensitive cargo has already entered a countdown against freshness and shelf life.

    Strong exporters therefore build the lane around the destination-country rule set, not around optimism. They ask whether the market is open for the specific commodity, what phytosanitary conditions apply, what supporting documents are needed, and whether the inspection or certification sequence is compatible with the product’s physical lifespan.

    That sequence sounds strict because it has to be. Produce punishes loose planning faster than many other categories do.

    Why Phytosanitary Controls Dominate the Category

    Plant-health controls dominate fresh-produce exports because importing markets are not just buying fruit, vegetables, or horticultural goods. They are managing pest and disease risk. That is why phytosanitary certificates matter so much. They are not ornamental compliance. They are part of the official mechanism by which the importing market decides whether the shipment can enter. DAFF: Export Certification

    This matters because the certificate logic often determines what has to happen before the cargo moves. Inspection, treatment, declarations, and product-specific conditions can all influence how the job is built. If the exporter treats certification as a back-end admin step, the freight plan may already be undermining the pathway that the destination market expects.

    That is why produce exporters should treat plant-health compliance as part of the commercial design of the shipment. The produce does not become more export-ready just because it is fresh. It becomes export-ready when the destination market has enough official confidence to admit it. In practice, the specific condition varies by commodity: a cold-treatment protocol for fruit fly risk on citrus, a methyl bromide fumigation requirement on some stone fruit, or an orchard-level pest-monitoring record for table grapes. The paperwork is different for every commodity-destination pair. That is exactly why “the documentation was complete” is not the same claim as “the documentation matched what this market actually requires.”

    How MICOR and Destination Rules Shape Reality

    MICOR and related market-access tools matter because they record what the destination market requires. This is one of the clearest points where logistics can fail if requirement work is left too late. The exporter may have product, buyer demand, and freight access, but if the market conditions are misunderstood, the shipment is weak before it even leaves Australia. MICoR

    This is also where exporters need to be disciplined about detail. Destination rules can influence whether treatment is required, what inspection route is needed, what declarations must appear, and how the goods must be described in official paperwork. That means the destination-country requirement set is not merely a reference document. It is the commercial blueprint for the lane.

    When exporters ignore that blueprint, they often create false momentum. The cargo looks booked. The buyer thinks the process is moving. The warehouse may already be handling the goods. But one critical question remains unresolved: whether the destination market will admit the consignment under the planned pathway. That is not progress. It is hidden fragility.

    This is why requirement work has to happen early enough to influence the physical plan. If a market expects a certain treatment, inspection order, or official declaration set, the exporter cannot leave those questions until after the product is packed and the departure window is closing. In produce, late answers are often expensive answers.

    Why Timing and Perishability Raise the Stakes

    Produce raises the cost of mistakes because the goods are time-sensitive. A document error or requirement mismatch does not only create regulatory pain. It can destroy commercial value much faster than it would in slower-moving categories. This is why produce exporters have to make the regulatory and physical timelines fit each other.

    The issue is not simply “move fast.” Fast movement is useless if the certification path is weak. The real challenge is sequencing. The inspection, certificate, packing, cold-chain handling, and freight plan all have to support each other closely enough that the goods remain both admissible and saleable by the time they arrive.

    Perishability creates panic, and panic lets the freight booking dominate the planning logic instead of the market-access side. The more useful response is to treat the perishability constraint as the reason for earlier, stricter planning, not as an excuse to skip it.

    That discipline is commercially valuable because relatively short delays can damage produce margins. The goods do not wait patiently while the paperwork problem gets solved.

    That asymmetry is what makes produce such a demanding export category. A small administrative error can create a large commercial loss because the product keeps aging while the process stalls. In slower categories, the business may still have room to recover. In produce, the clock is much less forgiving.

    Exporting Fresh Produce from Australia: Phytosanitary Rules: What Strong Exporters Do Differently

    What Strong Exporters Do Differently

    Strong fresh-produce exporters usually do four things well. They define the destination-market requirements early. They build the phytosanitary path before the freight path. They sequence inspection, handling, and logistics so the goods stay commercially viable. And they treat documentation quality as part of product quality.

    In practice, that looks like a more disciplined workflow.

    • They start with destination acceptance, not with transport capacity. The lane has to be valid before it is fast.
    • They map the certificate path before they book the chain. If inspection or official documents drive the sequence, the freight plan has to respect that.
    • They coordinate perishability with compliance. The product’s physical life and the regulatory life of the file have to work together.
    • They build repeatability. A successful produce export process should become easier to run again, not be reinvented from scratch each time.
    • They communicate constraints early. Buyers, packers, and internal teams do better when the market-access pressure is clear before the shipment is rushed forward.

    This is what turns produce exports from hopeful shipments into repeatable export business.

    That repeatability matters commercially. A buyer gains more confidence when the exporter can show that the lane, documentation sequence, and product-handling logic are not improvised each time. The exporter also benefits because each successful consignment should reduce uncertainty on the next one. That is one of the quiet advantages of disciplined produce-export operators over competitors who are still discovering the process consignment by consignment.

    In that sense, process quality becomes part of the export product too.

    Fresh-produce export is one of those categories where capability compounds slowly and decays quickly. An exporter who runs three years of clean phytosanitary clearances builds something competitors cannot easily replicate: a track record with DAFF inspectors, established treatment-provider relationships, a packing crew that already knows the documentation cadence, and a customer base in the destination market that no longer prices in disruption risk. None of those individually look like a moat. Together they become one. Conversely, an exporter can let that capability lapse through a rushed harvest, a documentation shortcut, or an under-rehearsed treatment process. The cost is usually not the immediate consignment. It is the inspector memory, the buyer caution, and the freight-rate quote that gets less competitive next quarter. The discipline is the asset. The certificates are just the receipts.

    Look at why fresh-produce export so often goes wrong, and the answer is rarely the regulation itself. The rules for phytosanitary certification, MICOR pathway selection, and market-access compliance are documented, public, and reasonably stable. The friction lives in the gap between the regulator’s mental model and the exporter’s. The regulator thinks in terms of pest-risk pathways, treatment efficacy, and country-specific protocols. The exporter thinks in terms of harvest dates, container bookings, and delivery commitments. Both views are correct. Both are necessary. But the system does not align them automatically. The exporter has to align them, and most exporters either skip it or do it inconsistently. The exporters who consistently clear cleanly have built internal processes that translate from one mental model to the other. They run a pre-departure documentation review not because anyone asks them to, but because they understand the alignment problem and refuse to leave it to chance. Exporters who move the same product into nearby ASEAN destination markets season after season eventually learn the pathway before the harvest, not after. That head start is the quiet advantage a first-time exporter cannot buy.

    Australian produce exporters planning a commercial export program can review Australian export and customs requirements on the Swift Cargo Australia page or request a freight quote for a specific shipment.

    The Part Nobody Tells You Before Your First Export Shipment

    Here is the fear you are probably not saying out loud: the fruit is picked, the coolroom is full, the truck is booked for tomorrow morning, and the phytosanitary certificate still is not in your hand. You did not get into growing produce to become an expert in export paperwork, and now the paperwork feels like the only thing standing between a season’s work and a shipment that might not go at all.

    Here is what is actually true: that scenario is avoidable, but only if the process starts backwards from how it feels natural to start it. Most first-time exporters treat certification as the last step before the truck leaves, because that is when it feels urgent. It needs to be one of the first steps taken once you know what you are growing and where it is going. That means checking the MICOR conditions for that destination market before harvest, not during the week of it. A treatment requirement like fumigation, cold treatment, or a pre-export inspection window can take days a picked, perishable crop does not have to spare. A certificate that takes three working days to issue is not a problem when you start it a fortnight out. It is a genuine crisis when you start it the morning the truck is already loading.

    The honest version of the advice is this: you will probably still feel behind the first time, even doing everything right, because a first shipment always feels like it is happening to you rather than something you are running. That feeling fades by the second or third shipment, once the certification timeline is simply part of the harvest calendar instead of a scramble that starts after the fruit is already boxed. It is not about becoming a compliance expert overnight. It is about moving one conversation from the week of shipping to the week you plan the harvest: the conversation with your export documentation, whether that is your own research or a customs broker who already handles produce.

    A produce exporter who has cleared quarantine cleanly for two years is not necessarily safe. They are untested against the one protocol update that changes a treatment requirement for their specific destination market, and a smooth record simply means that update has not happened yet on their watch. The exporters who get burned worst are usually the ones with the longest clean history, because a long run of easy clearances teaches a business to stop checking MICOR before every shipment rather than after. The safer posture is the opposite of what feels safe: treat each shipment’s conditions as unverified until checked fresh, no matter how routine the last twenty were, because the protocol that finally changes will not announce itself in advance.

    Frequently Asked Questions

    Why is fresh produce export work so compliance-heavy?

    Because importing countries apply plant-health rules that require official certification and condition compliance before the goods are accepted.

    Does being perishable make export planning more important?

    Yes. Perishability increases the commercial cost of document mistakes, timing errors, and market-access delays because the value of the cargo can deteriorate quickly.

    What role does MICOR play?

    It helps exporters understand importing-country requirements and should be part of planning before the cargo moves.

    What is the biggest exporter mistake here?

    Treating produce quality and freight speed as enough while underestimating the market-access and certification system that actually decides whether the shipment can succeed.