Author: SwiftCargo Team

  • Retiring in Thailand: Visa, Healthcare, Costs and What to Expect

    Retiring in Thailand: Visa, Healthcare, Costs and What to Expect

    Updated: October 2026

    Yes, you can retire in Thailand at 50 or over, and in 2026 the route is well defined. You enter on a Non-Immigrant O or O-A retirement visa, show either 800,000 THB in a Thai bank or 65,000 THB a month in pension income, carry health insurance of at least USD 100,000 if you take the O-A, and confirm your address with immigration every 90 days. A single retiree lives comfortably on roughly $1,800 to $3,000 a month, a couple on $2,500 to $4,000, with rent the biggest variable. Private hospitals in Bangkok, Chiang Mai, Phuket and Hua Hin cover most needs at a fraction of Western out-of-pocket prices. The people who make it work rent first, keep the first year reversible, and ship belongings only once Thailand has proven itself.

    An older couple at a balcony table above a hazy riverside city, one writing in a notebook, planning a retirement move together

    The short answer: what retiring in Thailand takes in 2026

    Four things decide whether the move works: a visa you can keep renewing, a budget that survives a weak home currency, a healthcare plan for the one event that is not routine, and a reversible first year.

    • Visa: age 50 or over. Non-Immigrant O extended for retirement inside Thailand, or Non-Immigrant O-A from your home country. Financial test of 800,000 THB on deposit or 65,000 THB monthly income. The O-A also requires USD 100,000 (3,000,000 THB) of health insurance. Long-stay alternatives: LTR Wealthy Pensioner (USD 80,000 a year passive income, ten-year framework) and Thailand Privilege (paid membership).
    • Money: lean $1,200 to $1,800 a month single; comfortable $1,800 to $3,000 single or $2,500 to $4,000 couple; high comfort $3,000 to $5,500 or more. Couples spend 1.3 to 1.6 times a single budget, not double.
    • Healthcare: private consultations $30 to $80, bloodwork $50 to $200. Most retirees pay routine care out of pocket and hold insurance or a serious buffer for major events. Bangkok has the deepest hospital network; islands and Isaan mean travel for complex care.
    • Compliance: 90-day address reporting for as long as you stay, an annual extension, and a document folder with calendar reminders. Overstaying is the most common legal trouble retirees get into.
    • First 90 days: short lease, know your nearest private hospital, track real spending, one weekly activity for community, then decide whether to extend to twelve months.

    Thailand is not the cheapest retirement destination, and premium areas of Bangkok, Phuket and Koh Samui now price close to international levels. It still offers one of the strongest lifestyle-for-the-money equations available if you choose the location for your health and budget rather than for a holiday memory.

    Thailand Retirement Visa Options (2026): O, O-A, O-X, LTR, Elite

    Most retirees use the Non-Immigrant O or O-A. Both require age 50 or over and the same financial test: 800,000 THB in a Thai bank account or 65,000 THB a month in income. The difference is where you apply and whether insurance is mandatory. Consulates interpret the rules differently, so confirm the current checklist with the Thai embassy or consulate in your country. This is not legal advice.
    An older couple at a desk as a man in a suit holds up a form, showing the document checks behind a retirement visa application

    Non-Immigrant O (Retirement)

    Usually issued as a 90-day visa and extended inside Thailand once you meet the financial requirement: arrive, open the bank account, season the deposit, then apply for the one-year retirement extension at a local immigration office. There is no statutory insurance requirement on this route, so every hospital bill is yours unless you insure voluntarily. Expect to show proof of age and of funds or income, plus a medical certificate or police clearance depending on where you apply.

    Non-Immigrant O-A (One-year Retirement Visa)

    Applied for from your home country, renewed annually while you stay eligible, with financial proof, medical certificate, police clearance and mandatory health insurance. Under a 2021 Cabinet-approved amendment, O-A applicants need health insurance or equivalent social welfare covering not less than USD 100,000 (3,000,000 THB) for the full length of stay, including COVID-19 treatment. It applies to the first application and each in-country extension, and approved insurers are listed at longstay.tgia.org. Pages still quoting the pre-2021 40,000/400,000 THB minimum are out of date.

    Non-Immigrant O-X (Long-stay Retirement Visa)

    A longer retirement visa limited to certain nationalities, with a higher financial threshold and the same insurance, medical and police documentation. Far fewer retirees qualify or use it. Because availability differs by passport, confirm it through official consulate guidance before planning around it.

    LTR Wealthy Pensioner (Ten-year Program)

    Run through the Thailand Board of Investment, the Long-Term Resident program has a Wealthy Pensioner category for retirees who can document a pension or passive income of at least USD 80,000 a year, or USD 40,000 plus at least USD 250,000 invested in Thai government bonds, direct investment or property. Applicants also need one of three health safeguards: insurance covering at least USD 50,000, current receipt of social security benefits in Thailand, or at least USD 100,000 held in a bank account in their own name for no less than 12 months. The payoff is a ten-year framework with fewer annual renewals. The official LTR site sets out benefits and conditions.

    An illustrative case, not a record of a real client: a retiree has USD 55,000 a year in pension and dividends, plus USD 25,000 a year in consulting fees. On paper that is USD 80,000, but the Board of Investment’s LTR portal (checked October 2026) counts only unearned income, meaning pension, rental, realized capital gain, dividends and interest, and says earned income and salaries will not be considered. That leaves USD 55,000, inside the USD 40,000 to 80,000 band, so the retiree must also hold USD 250,000 of qualifying assets in their own name before applying: Thai government bonds with at least five years of remaining maturity, a direct investment in a Thai-registered company, or Thai property. The health safeguard sits on top, and every condition has to be maintained for the length of the visa. For a retiree who clears all of it, the portal lists a first stay of five years extendable by five, annual rather than 90-day reporting, and no re-entry permit. Before you plan around this route, split your own income into earned and unearned, and test only the second figure against the threshold.

    Thailand Privilege (Elite)

    A paid long-stay membership rather than an income-tested visa. You pay for the selected package, pass the program’s application and background screening, and receive a long-stay structure with supporting services. Retirees choose it to remove complexity. Packages and pricing change, so verify current terms with the program directly before committing.

    Destination Thailand Visa (DTV): a structured trial year

    Not a retirement visa, but useful for one. Official sources describe the DTV as a visa for stays of up to 180 days, extendable once for another 180 days, with proof of eligibility under your program category and proof of funds. For a retiree who has not yet committed, it buys a full year of seasons, hospital visits and rent cycles before formalising a retirement route.

    The ongoing obligations most retirees underestimate

    A visa is not a one-time event. Long-stay foreigners confirm their address with immigration every 90 days, extend annually, and keep proof of funds current. Put the reporting date and the extension date in your calendar together and keep each report receipt with your passport. Choose the visa you can meet financially and administratively every year, not the one that looks easiest today, and avoid anyone selling guaranteed outcomes or loopholes.

    Cost of Living: How Much It Costs to Retire in Thailand (2026)

    A comfortable retirement costs $1,800 to $3,000 a month for one person and $2,500 to $4,000 for a couple, in US dollars, assuming a settled rather than tourist lifestyle. Thailand is still strong value against most Western countries but it is not as cheap as a decade ago, and rent is the swing factor that moves a budget between tiers.
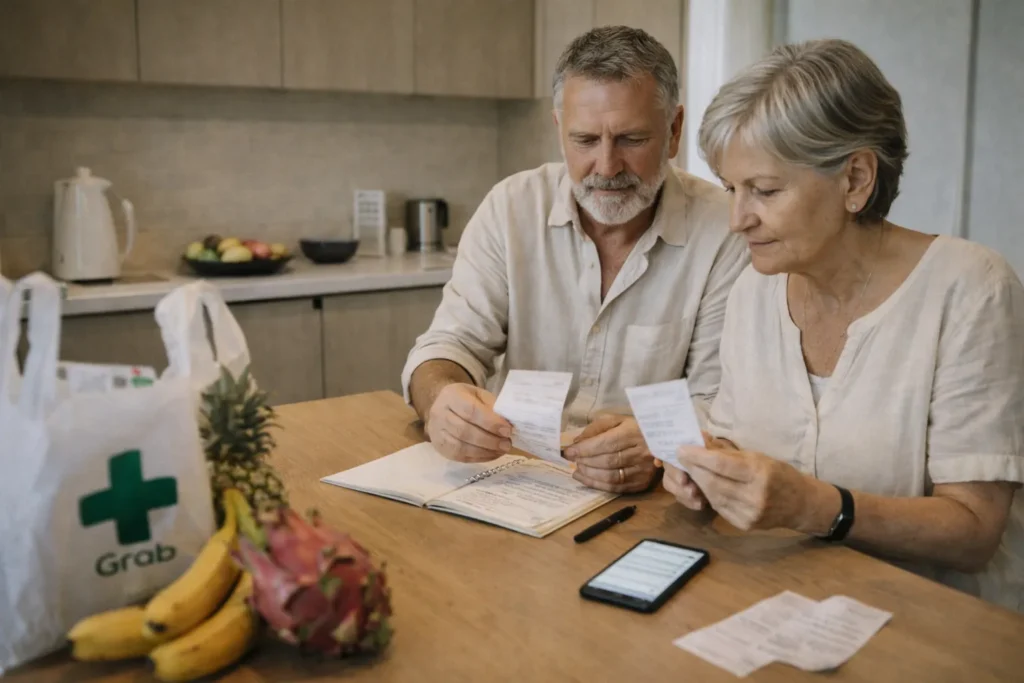
    An older couple going through receipts and a notebook at a kitchen table, showing how retirees track monthly spending

    The three lifestyle tiers

    • Lean and simple: $1,200 to $1,800 a month single, $1,800 to $2,700 couple. A modest fan-cooled or lightly air-conditioned flat away from the beach, markets over supermarkets, almost no imported shopping.
    • Comfortable (where most retirees land): $1,800 to $3,000 single, $2,500 to $4,000 couple. A modern one-bedroom condo with a pool, a mix of Thai and Western food, Grab rides, mid-tier health insurance.
    • High comfort or luxury: $3,000 to $5,500 or more single, $4,000 to $7,000 or more couple. Sea-view or premium Bangkok housing, imported groceries, a driver, top-tier insurance.

    These ranges hold in most retiree hubs. The exception is premium neighbourhoods of Bangkok and Phuket, where housing alone can push you into the high-comfort tier.

    Three budget snapshots

    Chiang Mai, single, comfortable: rent $450 to $850 for a one-bedroom condo, utilities and internet $80 to $170, food $300 to $600, transport $60 to $200, healthcare $80 to $250, lifestyle $250 to $600. Realistic total $1,700 to $2,700.

    Hua Hin, couple, comfortable: rent $650 to $1,200 for a condo or small house, utilities $100 to $220, food $500 to $900, transport $120 to $300, healthcare $150 to $400, lifestyle $400 to $900. Realistic total $2,500 to $3,900.

    Bangkok, single or couple, comfortable to high comfort: rent $700 to $1,600 or more for a modern one-bedroom, utilities $120 to $250, food $450 to $900, transport $100 to $300, healthcare $150 to $450, lifestyle $500 to $1,200. Realistic total $2,500 to $4,700 or more.

    The five costs that decide the budget

    Rent and location first: two retirees on the same income live very different lives depending on where they sign the lease. Lifestyle mix second: Thailand is affordable when you live like you are in Thailand, and expensive when most spending is imported groceries, wine and Western restaurants. Electricity third: air conditioning takes a bill from roughly $40 to $60 in cooler months to $120 to $250 or more in hot season. Healthcare strategy fourth, covered below. Flights home fifth: one or two round trips a year, or hosting family, is a real line item most first-year budgets miss.

    Hidden costs and the couples rule

    Long-stay administration adds up: visa extensions, 90-day reporting trips, agent fees if you use one. Your first six months usually run above your long-term average while you learn the local price of things. Couples rarely spend double; housing, utilities and transport are shared, so most couples land at 1.3 to 1.6 times a single budget.

    Stress-test the plan before you move

    Build the budget as if you were living in Bangkok or Phuket even if you plan somewhere cheaper. Add a healthcare buffer and one trip home a year. Add a currency buffer so a weaker home currency does not force a move. If the plan still works, Thailand will feel comfortable almost anywhere. Then rent for three months and track actual spending before you trust the numbers.

    Healthcare in Thailand for Retirees: Hospitals, Insurance, Planning

    Private consultations run $30 to $80, basic bloodwork $50 to $200, X-rays and ultrasounds $30 to $200, dental cleanings $30 to $100. An emergency-room visit with consultation and basic tests is usually in the low hundreds of dollars, and larger procedures move into the thousands or tens of thousands. That price structure is why most retirees pay routine care out of pocket and insure, or hold a serious buffer, for the one event that is not routine.
    A doctor with a stethoscope explaining a clipboard to an older man, showing the cost of private consultations for retirees

    Public vs private in plain English

    Foreign retirees overwhelmingly use private hospitals in Bangkok, Chiang Mai, Phuket, Hua Hin and Pattaya or Jomtien: same-day appointments for non-emergencies, diagnostics in one visit, prescriptions on site, and international departments with English-speaking staff. Public hospitals are far cheaper with excellent doctors, but mean longer waits, less English outside the cities and more administration. Most retirees pick a home hospital early, use a neighbourhood clinic for small issues and keep the public system as a backup.

    The three plans retirees actually use

    • Full private insurance. Predictable, protects against major bills. Premiums rise with age and pre-existing conditions affect pricing.
    • Hybrid. Routine care out of pocket, catastrophic cover for major events. The most common approach, and it needs discipline about keeping a savings buffer.
    • Self-insure. Only with strong savings and a realistic view of what one major procedure costs. It works until the first serious event.

    Insurance and your visa

    The O-A requires cover of at least USD 100,000 (3,000,000 THB), including COVID-19 treatment, for the full stay and at each annual extension. A Non-Immigrant O extended for retirement inside Thailand carries no statutory insurance requirement; you simply carry every bill yourself. Confirm the approved insurer list and documents through official sources before applying.

    Choose your address for the health you will have, not the health you have now

    Bangkok offers the deepest specialist network and the fastest route from a worrying scan to a cardiac or oncology ward. Chiang Mai, Phuket, Hua Hin and Pattaya have strong private hospitals for most needs, with the most complex cases referred to Bangkok. Koh Samui, Krabi and Isaan mean a ferry, a flight or a long drive for specialist care. A common pattern is to spend the first six to twelve months in Bangkok, learn the system, then move somewhere quieter with a known referral route.

    Make your healthcare portable before you fly

    Arrive with a written medical summary (conditions, surgeries, allergies), a prescription list using generic names and dosages, and recent test results. Confirm that any specialised medication is available and legal in Thailand before bringing large quantities. Keep a medical go folder, digital and offline, with passport and visa copies, insurance documents, emergency numbers and your home doctor’s contact details.

    A warning about long-term care

    Thailand is excellent for routine care and most medical needs. Assisted living and complex elder care do not mirror the systems in the United States, Australia or the United Kingdom. If you expect to need intensive long-term care later, research it early, keep a home-country safety net and a serious savings buffer, and be realistic about where you want to live in your later years.

    Best Places to Retire in Thailand (2026): Bangkok, Chiang Mai, Hua Hin, Phuket

    Choose by healthcare access first, community second, climate third, and cost last. Loneliness and inconvenient healthcare are the two most common reasons people leave. Neighbourhoods matter as much as cities: Bangkok near transit and hospitals is calm, Bangkok far from both is isolating.

    Rooftops, palms and a temple roof in a quiet Thai neighborhood, showing the local feel that matters when choosing where to settle
    • Bangkok. Best healthcare access, most convenience, most city intensity. Strong first-year base even if you move later. One-bedroom condo roughly $700 to $1,600 or more depending on transit proximity.
    • Chiang Mai. Strong value, walkable, culture, a large expat network. Smoke season is the real drawback; many retirees travel south for those months. One-bedroom roughly $450 to $850.
    • Hua Hin. The classic retiree town: coastal, calm, predictable, within reach of Bangkok for specialist care. Too quiet for some. One to two-bedroom condo or small house roughly $650 to $1,200.
    • Phuket. Developed island life with strong private hospitals, and one of the most expensive bases, with traffic and peak-season crowds. One-bedroom roughly $800 to $2,000 or more.
    • Pattaya and Jomtien. One of Thailand’s largest retiree communities, strong rental value, easy access to Bangkok and the airports. Neighbourhood choice decides everything. One-bedroom roughly $450 to $1,000.
    • Koh Samui. Calmer island life with real healthcare trade-offs; complex care means Bangkok. One-bedroom or small house roughly $700 to $1,500 or more by season.
    • Krabi. Quiet coast, fewer crowds, smaller expat infrastructure and limited specialist care. One-bedroom roughly $500 to $1,200.
    • Udon Thani and Isaan. Lowest cost, deeply local, less English, limited specialist access. Common for retirees with Thai family. Rent commonly $250 to $700.

    A shortlist method that works

    Pick one place strong for healthcare, usually Bangkok, and one that matches your lifestyle ideal. Spend weekdays in both, run normal errands, visit a hospital, sit through a hot afternoon and a rainy day, then rent in your favourite for three to six months.

    Who Thailand Suits, and the Honest Drawbacks

    Thailand fits retirees who want warmth, strong private healthcare on a realistic income, and are comfortable renting, adapting to a different bureaucracy and building a new routine. It is a poor fit if you need family within a short drive, strongly prefer four seasons, or expect public elder care to work the way it does at home. Many people solve the fit question with a hybrid: part of the year in Thailand, part at home, or a trial year before committing.

    The drawbacks are predictable. Heat and humidity are intense in hot season. Northern smoke season affects Chiang Mai for several months a year. Distance from children and grandchildren takes deliberate planning and a travel budget. Elder care is different, as above. Visas, reporting and banking are manageable only if you treat them as a system with a folder and calendar reminders. The cost of living is lower than much of the United States, Canada, the United Kingdom, Australia and Europe, but premium areas have become internationally priced and your lifestyle choices matter more than they did a decade ago.

    The seven fears retirees raise most often (running out of money, getting sick, loneliness, abandoning family, hating it after six months, bureaucracy, and Thailand changing) share one answer: move in stages. Thailand is changing, towards more structured long-stay rules and more international pricing in popular areas, and the staged approach lets you adapt rather than absorb that change.

    Rent First, Buy Later (or Never): The Trial Move Plan

    Rent for the first year. Foreigners can generally buy condominiums under specific rules but cannot own land outright, and the ownership structures promoted to foreigners (long leases, company structures, nominee arrangements) carry legal risk if handled badly. Most retirees never need to buy to live well, and those who eventually do still rent first. The regret stories are consistent: bought in a tourist area without seeing peak season, underestimated the climate, needed better hospital access, or wanted a different community. This guide does not provide legal advice; if you ever buy, use qualified legal support.
    An older couple viewing an empty apartment with an agent holding a folder, showing the scouting stage before committing to rent

    The four-stage trial move

    1. Scout for two to four weeks with a planning mindset: neighbourhoods you could live in, a hospital visit, rental listings at your price, weekday routines.
    2. Rent for three to six months and live normally. Track spending, test routines, see whether community is forming.
    3. Extend to twelve months if it is working. A full year covers hot season, wet season, smoke season in the north and peak tourist crowds.
    4. Commit only after the trial: full-time or part-time, ship more belongings or not, consider buying or not.

    What to do with your belongings during the trial

    Travel light and store everything at home for maximum flexibility, ship only essentials such as clothing and a few sentimental pieces, or store most items and ship more later once Thailand fits. The staged approach works because nothing has to be solved on day one.

    The same staged logic applies to shipping: storing now and pricing a full household move only once Thailand is confirmed keeps the decision reversible.

    Banking and Moving Money: The Two-Bank, Two-Card Setup

    Never rely on one bank or one card. Cards get blocked, accounts get flagged, apps fail at the worst moment. Experienced retirees run two of everything: a home-country account for income and reserves, a Thai account for local spending, a Thai debit card, a foreign debit card as backup, a foreign credit card for larger purchases and consumer protection, a second card in reserve, and two transfer methods.

    An older woman holding a bank card and looking at a laptop in a lamplit room, showing card and online banking tasks

    Opening a Thai bank account

    A Thai account simplifies rent, utilities and local payment apps, cuts foreign transaction fees, and supports the financial documentation some visa routes need. Policy varies by bank and by branch, and your visa type affects what is possible. Expect to show your passport, visa or entry stamp, proof of address and a local phone number, plus whatever the branch adds. Bangkok Bank, Kasikornbank (KBank), Siam Commercial Bank (SCB) and Krungsri are the names you will see most; the best bank is the one with a convenient branch and an app you can use.

    Moving money and handling the exchange rate

    SWIFT transfers suit large one-off moves where bank documentation helps. Services such as Wise are common for monthly transfers because fees and rates are more transparent. ATM withdrawals on foreign cards work during a trial move but fees add up long term. Keep pension or Social Security income flowing into your home account, transfer a predictable amount monthly or quarterly, and hold two to three months of living costs in Thailand plus a buffer for medical events, emergency travel and visa costs. Most problems come from a delayed transfer meeting an empty buffer, not from the transfer failing.

    Safety, Scams and Compliance: The Risks That Actually Matter

    The biggest day-to-day risk in Thailand is the road, not crime. Thailand has a high rate of road traffic injuries, and for retirees the danger point is scooters and unfamiliar motorbikes. If you are not an experienced rider, do not ride. Choose a walkable neighbourhood, use Grab or taxis, and if you drive, drive defensively and wear a seatbelt. In the main retiree hubs violent crime is rare in daily life; petty theft and nightlife areas are the exceptions, and normal common sense covers them.

    The scams that target retirees

    Rental deposit scams: unusually cheap listings, pressure to pay before viewing. Never send a deposit before you have seen the unit and confirmed the person has authority to rent it. Visa agent scams: guaranteed outcomes and secret shortcuts that create bigger problems later; use reputable providers and keep copies of everything submitted. Investment pitches: guaranteed condo returns and easy income for foreigners; ignore anything urgent or guaranteed. Romance scams: do not send money to someone you have not met and built trust with in person.

    The compliance mistakes that cause real trouble

    Overstaying a visa brings fines and potentially worse. Missing 90-day reporting creates unnecessary stress. Bringing medications that are controlled differently in Thailand can be a legal problem; confirm legality before carrying large quantities. One afternoon fixes most of this: a cloud folder with offline backup holding passport copies, visa pages, entry stamps, insurance, rental agreement, medical summary and prescription list, plus repeating calendar reminders for reporting and extension dates. Keep a small cash reserve at home, store bank and insurance emergency numbers offline, and know where your nearest embassy is.

    Community, Culture and Language: Avoiding the Loneliness Trap

    Loneliness is one of the most common reasons retirees leave Thailand, and it comes from three predictable choices: picking a cheap but isolated location, spending all your time with your partner, and waiting for community to happen. The fix is rhythm. Pick one weekly activity that matches your interests and show up every week. Pick one social space, a cafe, gym or club, and become a regular. Join one local online group for events and practical advice. Golf, walking and cycling groups, cooking classes, volunteering and expat club breakfasts work because they create repeated contact. If you arrive as a couple, both partners need independent outlets; one settling fast while the other feels isolated is a common pattern.

    Thailand is one of the more English-friendly countries in Southeast Asia. In Bangkok, Chiang Mai, Phuket, Hua Hin, Pattaya and Koh Samui you can handle most daily life in English, and hospitals are used to foreigners. Outside the hubs, and in local neighbourhoods inside them, English thins out. You do not need Thai to live here, but greetings, numbers, directions and food words change how you are treated and what you pay. Thai culture is polite, service-oriented and respectful towards older people; it also avoids direct confrontation, visible anger and public embarrassment, so a calm tone gets better outcomes than pressure.

    Shipping and Storage: What to Do With Your Belongings

    A Thai retirement visa does not carry the household-goods duty exemption. Thai Customs grants that relief against a one-year work permit, a confirmed one-year working period, permanent residence or a full Smart Visa, and the FIDI Global Alliance’s Thailand customs guide excludes holders of visa types O and O-A by name. Budget for import duty of 10-30% on CIF value plus 7% VAT rather than planning around a duty-free window. Our guide to what can and cannot be shipped duty-free on a Thai retirement visa sets out the detail before you finalise an inventory.

    Hands lifting a framed portrait and a carved wooden box out of an open wooden crate lined with bubble wrap, for packing keepsakes

    Three approaches, and the one most retirees should take

    Sell and start fresh suits people already downsizing with few sentimental items; household basics are easy to buy in every hub. Trial move first, ship later is the safest route for most retirees: three to six months of essentials in luggage, the rest stored at home, shipping only once Thailand feels right. Ship a full household once committed makes sense when you know your location long term. Across all three: ship what is meaningful, not what is replaceable, and leave bulky furniture and appliances that cost more to move than they are worth.

    The retirees who have shared their moves with us almost never regret what they left behind. They regret the opposite: the container they filled in a hurry, back home, before spending a single night in Chiang Mai or Hua Hin. One shipped a heavy oak dining set halfway around the world, then spent two years eating at the low rattan table he bought in his first week, because it suited the heat and the room better.

    Customs, paperwork and timing

    Household shipping is difficult because of the paperwork, not the transport. Requirements vary with what you ship, whether items are new or used, your visa status and how the shipment is declared, and most delays come from unclear item lists, incomplete documents, restricted goods or a shipment treated as commercial. A few months of renting tells you whether you want a condo or a house and whether you will stay in one region, which is worth knowing before you look at what shipping to Thailand costs.

    Storage that keeps the first year flexible

    Storing at origin is the most common trial-phase approach: it makes returning home easy and avoids paying for storage in two countries. If home is the United States, the returning-resident duty exemption on used household goods makes shipping back later a low-cost option; see our Thailand-to-USA shipping cost and customs guide. Storing in Thailand suits retirees moving between rentals or waiting for a long-term home. A hybrid keeps high-value or sentimental items at home and seasonal items in Thailand.

    When you do ship

    Get more than one quote. Ask for documentation requirements upfront. Confirm what is included, such as packing, insurance, customs handling, and final delivery. If you choose to work with Swift Cargo, we will always provide this to you upfront. Avoid vague pricing and unclear scope, plan timelines with a buffer, and do not ship everything until Thailand feels like home. Swift Cargo supports this kind of planning for retirees, especially those using a trial-move approach, with customs documentation and storage coordination at both ends. See how the Thailand shipping process works if you are ready to plan your belongings move.

    Timeline: From Twelve Months Out to Your First 90 Days

    Twelve months out: settle your budget tier, your likely visa route, a shortlist of two or three locations with their major hospitals, and what family connection will look like. Nine months out: the two-to-four-week scouting trip, ideally in a season that worries you, with a hospital visit, rental listings in your range, and one expat meetup. Six months out: choose a three-to-six-month first lease, decide what you will bring and what you will store, start insurance planning, and build the two-bank, two-card setup.

    Three months out: confirm visa documentation, finalise insurance if your route requires it, request your medical summary and prescription lists, set up a phone plan that survives two-factor authentication abroad, book the first short lease, book storage if needed through Swift Cargo Solutions, and delay major shipping decisions until after the trial. One month out: flights, accommodation, document copies, emergency contacts, medication, backup cards. Pack for 90 days; most retirees need less than they expected.

    First 90 days: know your nearest private hospital and register if needed; understand your reporting requirements and set reminders; track actual spending; pick a few weekly habits and attend social activities early; and at 60 to 90 days ask whether this feels like home. Months six to twelve: extend the rental, live through the other seasons, refine the budget, deepen social routines, and decide whether a longer visa structure, or buying, makes sense for you.

    FAQs (Real Questions People Google About Retiring in Thailand)

    How much money do you need to retire in Thailand in 2026?

    For most retirees, a comfortable lifestyle in Thailand in 2026 typically falls around:

    Single: $1,800–$3,000/month
    Couple: $2,500–$4,000/month

    You can live on less in lower-cost areas, and you can easily spend more in Bangkok, Phuket, or if you choose a highly Western lifestyle.
    The biggest cost variable is usually rent.

    If you want the lowest-risk plan, do a 3–6 month trial move, track real spending, then decide.

    Can you retire in Thailand on Social Security?

    Many retirees do. The key is whether your Social Security income covers your lifestyle tier and location. Thailand is often workable on Social Security if you choose housing carefully, live in a mid-cost city (Chiang Mai, Hua Hin, Pattaya/Jomtien), and keep a mostly local lifestyle.
    If you want a high-comfort lifestyle in Bangkok or Phuket, Social Security alone may be tight unless you have additional savings or pension income.

    What’s the best visa for retirees in Thailand?

    There is no single “best” visa. The best visa is the one that fits your age, finances, and risk tolerance.
    Most retirees choose one of these four:
    Non-Immigrant O (Retirement) if they are 50+ and plan to extend for retirement inside Thailand, a route with no statutory insurance requirement
    Non-Immigrant O-A (Retirement Visa) if they are 50+ and meet the financial requirement plus mandatory insurance of at least USD 100,000 (3,000,000 THB)
    LTR Wealthy Pensioner if they qualify and want a longer-term structure
    Thailand Privilege (Elite) if they prefer a paid convenience route

    If you are not ready to commit yet, many retirees start with a trial move strategy and then formalize a long-stay visa once they are sure.

    Do you need health insurance to retire in Thailand?

    It depends on your visa. The Non-Immigrant O-A requires health insurance covering at least USD 100,000 (3,000,000 THB) for your whole stay, including its annual extension in Thailand. A Non-Immigrant O visa extended for retirement inside Thailand carries no statutory insurance requirement.
    Even if you plan to pay out-of-pocket for routine care, insurance can protect you from major hospital costs.

    Most retirees use one of three strategies:
    – full private insurance
    – hybrid (out-of-pocket routine + catastrophic coverage)
    – self-insure (only if savings are strong)

    If you are planning a retirement visa, always confirm the current insurance requirements with official sources.

    Is Thailand safe for retirees?

    Thailand is generally considered safe for retirees in day-to-day life, particularly in established expat hubs.

    The biggest real-world risk is usually road safety, not crime.
    Basic precautions go a long way: avoid scooters if you are not experienced, and use taxis/Grab and walkable neighborhoods. Slow down on major financial decisions and avoid scams.

    What’s the best place to retire in Thailand?

    It depends on what you want.

    Here are the most common matches:
    – Bangkok: best healthcare access and city convenience
    – Hua Hin: calm coastal retiree hub
    – Chiang Mai: strong value + strong expat community
    – Phuket: beach lifestyle with modern infrastructure (higher cost)
    – Pattaya/Jomtien: large retiree community + affordability
    – Koh Samui: island life with some healthcare tradeoffs

    The best strategy is to rent first and choose your long-term base after living locally.

    Should you rent or buy in Thailand?

    Most retirees rent, and many who eventually buy still rent first.
    Buying can be complex for foreigners, and it’s rarely necessary to enjoy a great retirement lifestyle.
    Renting gives you flexibility, which is extremely valuable in your first year.
    If you ever decide to buy, wait until you’ve lived in Thailand long enough to be confident about location and long-term plans.

    Can foreigners own property in Thailand?

    Foreigners can generally buy condominiums under certain rules, but land ownership is different and property structures can be complex.
    If you consider purchasing property, always use qualified legal advice and avoid shortcuts.

    Will I be lonely retiring in Thailand?

    Loneliness is one of the most common challenges for retirees abroad, and one of the biggest reasons people return home.
    The good news is that Thailand is one of the easiest countries in Asia to build community, especially in expat hubs.
    The key is routine: join one or two groups early, commit to weekly activities, and build a small network in your first 90 days.
    If you take social life seriously early, retirement feels connected, not isolating.

    What’s the biggest mistake retirees make in Thailand?

    The biggest mistake is moving too fast.

    This often looks like:
    – committing to a long-term lease without testing the neighborhood
    – buying property early
    – shipping everything before confirming Thailand fits
    – underestimating visa paperwork and reporting

    The safest approach is staged:
    Visit → rent for 3–6 months → extend → commit later.

    How do I bring my belongings to Thailand?

    Most retirees choose one of three options:
    – sell most items and start fresh
    – trial move and store belongings at home
    – ship a household once committed

    The best approach for most people is:

    trial move first → store at home → ship later if needed.

    This keeps your move reversible and reduces regret.

    How long does it take to feel settled in Thailand?

    Most retirees report that the first 30–90 days are the adjustment phase.

    By 3 months, you usually:

    – understand daily routines
    – have a healthcare plan
    – have a basic social rhythm
    – feel confident navigating your neighborhood

    By 6–12 months, you usually know whether Thailand is a long-term fit. That’s why the trial move approach works so well.

    Is Thailand still affordable in 2026?

    Thailand is generally still affordable compared to most Western countries, but it’s not as cheap as it was a decade ago.
    Some parts of Bangkok and Phuket can now feel “international priced,” especially in premium areas.

    Thailand still offers strong value, particularly if you:
    – choose housing carefully
    – live in a mid-cost region
    – mix local and Western lifestyle habits

    What should I do first if I’m considering retiring in Thailand?

    Start with these three steps:

    1) Build a realistic budget range (lean / comfortable / high comfort)
    2) Research the most likely visa pathway for your situation
    3) Plan a 2–4 week scouting trip to test two or three locations

    From there, the best next move for most people is to rent for 3–6 months and make the decision with real experience.

    What is 90-day reporting in Thailand?

    Long-stay foreigners confirm their residential address with Thai immigration every 90 days. It is not a visa renewal, only an address confirmation, but it is ongoing for as long as you stay and missing it can bring penalties. Put the dates in your calendar next to your extension date and keep the receipt from each report with your passport.

    What is the difference between the O-A and O-X retirement visas?

    The O-A is the common route: a one-year retirement visa renewed annually while you stay eligible, with the 800,000 THB deposit or 65,000 THB monthly income test and mandatory health insurance. The O-X is a longer-stay retirement visa limited to certain nationalities, with a higher financial threshold, so far fewer retirees qualify or use it.

    Can you retire in Thailand on $1,500 per month?

    It is possible in lower-cost areas with a simpler lifestyle: modest rent, mostly Thai food, limited imported shopping and alcohol, and no premium beach location. It works best for a single retiree in stable health who does not need top-tier private insurance. Add electricity for air conditioning and at least one trip home a year before you decide the number holds.

    What is the LTR Wealthy Pensioner visa?

    Thailand’s Long-Term Resident program, run by the Board of Investment, has a Wealthy Pensioner category for retirees. It requires a pension or passive income of at least USD 80,000 a year, or USD 40,000 plus at least USD 250,000 invested in Thai government bonds, direct investment or property. It is a ten-year framework, so it suits retirees who want a longer structure than annual extensions.

    Is Thailand cheaper than Europe for retirees?

    Usually, for housing, dining and personal services, and the gap feels largest if you come from a high-cost European city and live a mostly local lifestyle. It narrows quickly with imported groceries, premium housing in Bangkok or Phuket, and frequent flights home. Compare your real monthly spend, not headline averages.

    Your next steps

    At SwiftCargo, we help people relocate internationally with a staged approach, including support with customs documentation and storage options at both ends. If you want advice or quotes when the time is right, contact us through the site.
    A gloved mover latching a blue shipping container beside a house with boxes waiting, showing a household shipment sealed

    We support the staged approach: store now, ship once confirmed.

    The form takes about 60 seconds. We help with customs documentation and storage at both ends, with fixed pricing and no hidden costs.

    Store or ship to Thailand

    Retiring in Thailand Sources (Updated October 2026)

    Thai Consulate-General in Chicago: Non-Immigrant Long Stay Visa (O-A / O-X)

    Thailand Board of Investment (BOI): Long-Term Resident (LTR) Visa Portal

    Thailand Privilege Card (Official): Membership Package Comparison

    Thai Customs Department: Household Effects / Duty Exemption Guidance

    Thailand.go.th (Government Portal): Criteria for Duty Exemption on Used Household Effects

    World Health Organization (WHO): Thailand Road Safety

    U.S. Department of State: Thailand Travel Advisory

    UK Government (FCDO): Thailand Travel Advice

    Thai General Insurance Association (TGIA): O-A Health Insurance Guidelines

    FIDI Global Alliance: Thailand Import Customs Guide (last updated 7 September 2024; copy hosted by Asian Tigers Group)

    Reuters: Thailand to Impose 10% Duty on Low-Cost Imports (Jan 1, 2026)

    Budget & Cost-of-Living Sources (Used in Cost of Living, Best Places to Retire, and FAQs)

    Numbeo: Cost of Living in Thailand (Updated Dec 2025)

    Exiap: Cost of Living in Thailand (Based on Numbeo Data)

    Thailand Insider Guide: Cost of Living in Thailand (2025/2026)

    Healthcare & Hospital Cost Sources (Used in Healthcare in Thailand for Retirees and FAQs)

    Bangkok Hospital Headquarters: Pricing & Payment

    Bumrungrad International Hospital: Patient Finance & Insurance Information

    Samitivej Hospital: Patient Resources / Accommodations & Charges (Official)

    ExpatDen: Cost of Healthcare in Thailand (Full Breakdown)

    The Thaiger: Doctor Consultation Costs in Thailand
  • The Best Countries for Crypto Holders in 2026, Ranked by Safety

    The Best Countries for Crypto Holders in 2026, Ranked by Safety

    A comparative guide to crypto-friendly countries for long-term residency, safety, and banking stability.

    Dark world map with glowing hubs joined by thin arcs, illustrating how settlement options are compared across regions

    A practical map for people planning a life, not a weekend

    Today, crypto holders planning to live abroad long term are not optimizing for conference density or social noise. They are optimizing for safety, residency durability, dependable banking rails, and a government that does not rewrite the deal mid-cycle. The questions are less ideological now, more administrative, and the answers have become sharply unequal across countries.


    The Crypto Long-Term Settlement Index

    The Crypto Long-Term Settlement Index is designed to be boring on purpose, because the risks it measures are boring until the day they are catastrophic.

    It does not rank which country “loves crypto.” It ranks where a foreigner can settle, comply, and function, while keeping the option to on-ramp and off-ramp without improvisation.

    What the columns mean

    We score each jurisdiction across five dimensions, then normalize results on a 0 to 100 scale.

    1) Safety

    We use the Global Peace Index as a core benchmark and treat it as a proxy for daily-life risk rather than geopolitics alone.

    2) Nomad-to-Residency Velocity

    How quickly a visitor can become a resident in a way that survives renewals, compliance checks, and the tightening that tends to arrive after a country becomes popular.

    3) Crypto to Fiat Rails

    Not whether crypto is “allowed,” but whether foreigners can move between crypto and local banking without recurring account closures, frozen transfers, or policy-by-rumor. Licensing clarity matters, and bank behavior matters more.

    4) English Penetration

    Not bar conversation English. Life-admin English. Banking support, leases, utilities, immigration correspondence.

    5) Rule Persistence

    Weighted heaviest, at 30 percent. It measures the likelihood that the other four variables survive an election, a cabinet reshuffle, or a regulatory backlash. This is where “good on paper” jurisdictions often fail in real life.

    How to understand the top and lowest scorers

    A country above 80 tends to be a place you can plan around. A country below 30 tends to be a place where friction is structural, not accidental, even if the tax rate looks seductive. The middle band is where most “nice places” live, workable for a season, risky for long-term commitments.

    How the index evolved over the last 10 years

    In the mid-2010s, most governments ignored crypto, which meant many places functioned as accidental havens. Then adoption moved from hobby to capital flow, and capitals formed task forces, regulators published positions, and banks began treating “crypto” as a risk category that demanded a written rationale.

    The world split into two approaches. A smaller set decided to compete for mobile capital, writing clearer statutes and building regulated rails. A larger set chose containment through ambiguity, soft restrictions, or episodic enforcement. The result is a wider spread than early adopters remember, and a sharper cliff between “spendable” and “settleable.”

    MetaMask, Visa rails, and why settlement is still different from spending

    Wallet-to-card products are real progress. They reduce friction for day-to-day purchases and make cross-border life feel more fluid. They do not solve settlement.

    Landlords want local guarantees, not blockchain proof. Notaries want documented source-of-funds evidence before property changes hands. Banks want jurisdictional clarity before issuing mortgages, leases, or even ordinary accounts for residents with complex histories. Until those institutions accept crypto-native proofs as first-class documents, the Index still matters because it separates “you can pay” from “you can live.”


    Editor’s Picks

    Aerial view of a lit harbour city at dusk with a ship at the quay, as a setting for a long-term residency pick

    Five jurisdictions that survive real life in 2026

    Each of the five offers at least one credible long-term residency path, functioning crypto-to-fiat rails, and a political environment where rule reversals are slow and telegraphed.

    1) Portugal

    Why it wins: EU durability plus a finite citizenship clock.

    Portugal remains the cleanest long-term gateway into the European Union for crypto holders who value legal continuity over tax arbitrage. The D8 pathway is slow, documented, and bureaucratic, which is precisely why it survives scrutiny. The 2023 introduction of a 28 percent tax on short-term crypto gains clarified, rather than undermined, the regime.

    2) United Arab Emirates

    Why it wins: Policy continuity and operational rails.

    The UAE’s advantage is not ideology, but execution. A dedicated regulatory apparatus, plus maturing bank behavior around licensed activity, turned what was once an offshore workaround into a domestic system. Residency pathways are fast, taxes are explicit, and reversals are rare.

    3) Singapore

    Why it wins: Institutional trust and enforcement symmetry.

    Singapore is not permissive. It is consistent. Licensing is strict, compliance expectations are high, and banking access follows approval rather than speculation. English is universal, administration is professional, and policy changes are announced well in advance.

    4) Georgia

    Why it wins: Speed and optionality at low cost.

    Georgia remains one of the fastest places to move from arrival to normal life. Long visa-free stays, no personal income tax on most crypto trading gains, and improving banking access create a low-friction environment for long-term testing. The trade-off is geopolitical exposure, which is why Georgia performs best as a secondary base.

    5) Panama

    Why it wins: Quiet stability in the Americas.

    Dollarization, territorial taxation, established residency pathways, and a long history of accommodating foreign capital make it one of the few Americas jurisdictions that remains boring under stress.


    How to use the bands in practice

    A man in a classroom pointing at hand-drawn boxes and arrows on a whiteboard, showing the bands being explained step by step

    The bands are not rankings. They are operating zones.

    Each band groups jurisdictions that share similar time-zone alignment and regulatory temperament. Used correctly, they allow you to distribute life risk the same way you distribute portfolio risk. One base for residency and paperwork. One base for banking depth. One base for lifestyle or cost control.

    A two- or three-band configuration works: an EU base for passport progression, a Gulf or Asia base for tax clarity, and an Americas base for time-zone coverage. The objective is not constant movement, but the ability to move without panic.

    If a band works, stay long enough to earn residency. If conditions shift, leave before urgency enters the decision.

    Two exposures sit outside the bands, and neither shows up in a headline tax rate. The first travels with the passport. The United States taxes its citizens wherever they live, so an American who settles in Lisbon or Dubai keeps the same annual filing duty that follows Americans moving to Thailand. The move diversifies the lifestyle and leaves the largest tax exposure exactly where it was. The second arrives on the 180th day. Thailand treats anyone present that long in a calendar year as tax resident, and since 1 January 2024 foreign income earned by a resident can become taxable once it is brought into the country, the same remittance rule that catches pension drawdowns. Gains realised offshore and wired in to pay the rent can fall under it too.


    A man working on a laptop at a seaside cafe above a sunlit harbor, showing a lifestyle move that leaves tax duties unchanged

    A time-zone map for long-term settlement


    🌍 BAND 0 UTC -1 to 0

    Mid-Atlantic and West Africa

    CountrySafetyNomad and settlement door 2026Crypto to fiat railsEnglish proficiencyGovernment stability memo2026 vs 2022 delta
    Cape VerdeNot rated by the GPIRemote-work “Caboverde Digital”, 6 months renewable, proof of income requiredEuro-linked escudo, EU-facing rails improving, P2P activeEnglish growing in tourismStable parliamentary democracy, low coup risk historyNewer program, still under-followed
    Azores (Portugal)Very low crimeSame D8 as mainland Portugal, 10 years to citizenship pathwaySEPA rails, no blanket crypto bansHighEU and Schengen stabilityShares Portugal’s post-2023 short-term tax reality
    Madeira (Portugal)Very low crimeRegional nomad program plus D8 pathwaysSEPA railsHighEU and Schengen stabilitySame as above
    Canary Islands (Spain)Very safe regionallySpain residency routes, Non-Lucrative options in practiceSEPA rails, slower KYCHigh in hubsEU stabilityBanking thawing since early 2020s

    🌎 BAND 1 UTC 0 to +1

    Western Europe core

    CountrySafetyNomad and settlement door 2026Crypto to fiat railsEnglish proficiencyGovernment stability memo2026 vs 2022 delta
    Portugal1.43D8 to 10-year citizenship trackSEPA rails with major exchangesVery highEU stabilityShort-term gains taxed since 2023
    Spain1.65Digital nomad visa plus standard residency routesSEPA rails, banks cautiousHighEU stabilityClearer nomad path than earlier cycle
    Germany1.66Freelance routes or Blue Card pathwaysStrong banks, strict complianceVery highEU stabilityRemains predictable for long-term planners
    France2.08Talent and innovation pathwaysStrong banks, cautious postureHighEU stabilityMore mainstream posture than early 2020s
    Ireland1.37Skilled routes, remote reality improvingStrong banking ecosystemNativeEU stabilityOperational clarity improved
    UK1.73HPI and Global Talent style routesStrong fintech railsNativeStable, politically noisy at timesContinues to be operational
    Switzerland1.36High barrier entry, strong residency optionsMature crypto banking ecosystemHighExtremely stableRemains top tier, entry cost is the trade
    LiechtensteinNot rated by the GPISmall, high compliance, business setup routesSwiss-adjacent railsHighExtremely stableTiny but predictable
    Netherlands1.57Startup routes and employment routesStrong banking, cautious complianceVery highStable coalitionsStrong English and rule persistence
    Belgium1.61Self-employed routesStrong banking, cautious complianceVery highStableIncremental improvement
    LuxembourgNot rated by the GPIInvestor and business routesInstitutional railsHighVery stableUnder-estimated settlement base

    🕌 BAND 2 UTC +1 to +4

    Balkans, Eastern Med, and the Gulf edge

    CountrySafetyNomad and settlement door 2026Crypto to fiat railsEnglish proficiencyGovernment stability memo2026 vs 2022 delta
    Greece1.83Digital nomad route plus standard residencySEPA railsHighEU stabilityClearer pathways than earlier cycle
    Cyprus1.97Nomad route plus residencySEPA railsHighEU stabilityRemains predictable
    MaltaNot rated by the GPINomad residence permitsEU rails, licensing cultureNative-level official languageEU stabilityBenefits from EU clarity
    Turkey2.61Property and long-stay optionsActive local exchangesModerateCurrency volatility riskStill usable, macro is the trade
    Georgia2.07Low-friction long staysImproving banking accessModerateGeopolitical watchMore operational than early 2020s
    Armenia1.83Long stays and IT routesImproving railsModerateRegional riskWorkable for some profiles
    UAE1.93Remote work, green, golden pathwaysDedicated regulator, expanding railsVery highHigh policy continuityClearer than 2022
    Israel3.12Innovation pathwaysStrong railsHighHigher security volatilityHighly case-dependent

    🌄 BAND 3 UTC +3 to +5:30

    Gulf depth, Central Asia, and South Asia hinge

    CountrySafetyNomad and settlement door 2026Crypto to fiat railsEnglish proficiencyGovernment stability memo2026 vs 2022 delta
    Saudi Arabia2.07Premium residency via investmentEmerging frameworkModerateHigh continuityStill evolving
    Qatar1.68Investment and income pathwaysConservative railsHighHigh continuityStable, selective
    Bahrain2.13Investor routesLicensed ecosystem, smaller scaleHighHigh continuityContinues to mature
    Oman1.85Investor pathwaysEarly-stage railsModerateHigh continuityNewer posture
    Iran2.76Settlement difficultSanctions constrain railsLowHigh riskGrey by nature
    Kazakhstan1.77Long stays and business routesMixed railsModerateModerate riskCase-dependent
    Uzbekistan1.73IT and business routesDeveloping railsLowReform trajectoryStill maturing
    India2.41No true nomad visaPolicy and banking cautionHighPolicy swingsHard for settle logic

    🌅 BAND 4 UTC +7 to +8

    Southeast Asia and East Asia

    CountrySafetyNomad and settlement door 2026Crypto to fiat railsEnglish proficiencyGovernment stability memo2026 vs 2022 delta
    Singapore1.44Talent and business pathwaysDeep regulated railsNative-levelExtremely stableRemains a top-tier anchor
    Malaysia1.51Nomad pathways plus standard residencyPractical railsHighStableStrong value profile
    Thailand2.09DTV 5-year multiple-entry structureImproving rails, compliance mattersHighGenerally stableDTV changed long-stay options
    Vietnam1.74No true nomad visaP2P heavyModerateStableSettlement friction remains
    Philippines2.09Long-stay options existImproving railsHighPopulist swingsGaining momentum
    Hong KongNot rated by the GPITalent routesLicensed exchange modelHighChina overlayMore open than early 2020s

    🌴 BAND 5 UTC -8 to -5

    North America and Central America

    CountrySafetyNomad and settlement door 2026Crypto to fiat railsEnglish proficiencyGovernment stability memo2026 vs 2022 delta
    Canada1.53Skilled and business pathwaysDeep railsNativeVery stableOperational, higher tax reality
    USA2.54No true nomad visaDeepest exchange ecosystemNativeElection noiseRails strong, immigration harder
    Mexico2.65Temporary resident routesStrong regional railsHighCartel pocketsTime-zone favorite
    BelizeNot rated by the GPILong-stay optionsNarrow railsNativeStableQuiet base profile
    Costa Rica1.86Rentista routesStrong railsHighStableStrong long-stay option
    Panama1.98Residency routesDollarized railsHighStableContinues as Americas anchor
    El Salvador2.26BTC-forward posture, residency variesBTC-forward railsModerate to high in expat zonesConcentrated powerUnique spend story, settlement trade-offs
    A traveler wheeling a suitcase past airport windows facing parked jets, showing options you can act on quickly

    Where the caravan is heading

    Pick two or three bands, not one country, and you buy time. You also buy leverage, because leverage often comes from having options you can execute quickly.

    The jurisdictions winning this decade are not the ones with the lowest headline rate. Thailand’s five-year DTV long-stay route is one example of a predictable, documented residency path.


    Hands arranging six printed city skyline photos beside a globe, showing candidate locations being compared before choosing

    Scoring methodology and weightings

    The Crypto Long-Term Settlement Index privileges durability over novelty. To achieve that, categories are weighted based on their historical impact on forced relocation and capital friction.

    Category weights

    Rule Persistence: 30 percent

    This is the dominant variable. It captures the probability that laws, banking access, and residency pathways remain intact after elections, cabinet changes, or regulatory backlash. Jurisdictions with written guidance, independent courts, and low retroactive risk score highest.

    Safety: 20 percent

    Derived primarily from the Global Peace Index and cross-checked against crime statistics and governance indicators. This measures everyday personal risk rather than geopolitical posture alone.

    Crypto to Fiat Rails: 20 percent

    Assesses the practical ability of a foreign resident to move between crypto and local banking. Licensing clarity, bank participation, and regulator transparency all contribute.

    Nomad-to-Residency Velocity: 15 percent

    Measures how quickly and realistically a foreigner can obtain a status that survives renewal cycles. Programs that look attractive but collapse under volume are discounted.

    English Penetration: 15 percent

    Evaluates the ability to operate legally and administratively in English. This includes banking, immigration, utilities, and property transactions.

    Normalization and scoring

    Raw inputs are normalized to a 0 to 100 scale within each category. Final country scores reflect weighted aggregation rather than simple averages. This is why some “crypto-friendly” jurisdictions rank lower than expected, and some conservative jurisdictions rank higher.

    The index intentionally penalizes environments where a single failure point, such as banking access or political volatility, can nullify otherwise attractive conditions.

    What the index does not measure

    The index does not attempt to score lifestyle preference, climate, cuisine, or social scene. It assumes those variables are subjective and secondary to settlement viability. It also does not reward short-term tax loopholes that lack legislative backing.

    Related reading: The Hidden Cost of Moving Abroad for Work Isn’t Money. It’s Your Life.

    Crypto Expat FAQs


    Where should I live long-term if most of my net worth is in crypto?

    If most of your net worth is in crypto, you are not choosing a “crypto-friendly country.” You are choosing a place where your life can still run normally during stress: bear markets, banking crackdowns, and political shifts. In our Index, that means prioritizing Rule Persistence and Safety first, then Crypto ↔ Fiat Rails, then residency speed and English.

    A sensible long-term setup is rarely one country. It is usually a two- or three-band configuration that reduces forced decisions. For example:

    * Portugal as an EU base if you want a credible long-term residency story and eventual citizenship pathway.
    * UAE (Dubai) as an operational base where policy continuity is high and your day-to-day rails can be strong once you are properly set up.
    * Panama as an Americas time-zone anchor that tends to be boring, which is often a feature, not a bug.


    The market risk is not only price volatility. In a deep drawdown, people make worse decisions, governments face pressure, and banks become conservative. Your goal is to live somewhere that still functions when your portfolio does not feel like it does.


    Which countries are safest for crypto holders to settle?

    Safety is not just crime rates. For crypto holders it is also:

    * whether you can live without defensive routines,
    * whether the rule of law is strong enough to make you predictable to institutions,
    * whether your residency status can survive scrutiny.

    Within the article’s framework, high-safety settlement candidates tend to include:

    * Portugal and several Western European states for personal safety plus institutional durability.
    * Singapore for high safety, tight compliance, and strong institutional behavior.
    * UAE for extremely low street crime in many areas, plus high policy continuity.

    The caution is that “safe” can become expensive quickly, especially after a place becomes popular, and cost pressure can distort decisions. A safe jurisdiction only stays safe for you if you can afford it without turning every month into a liquidation event.


    What countries won’t suddenly ban crypto or close bank accounts?


    No country can guarantee that. The closest thing to protection is a place where changes happen slowly, in writing, and within a legal and regulatory culture that does not rely on surprise enforcement.

    That is why our Index gives Rule Persistence the heaviest weight, at 30 percent. It is a proxy for the probability that a change of government, a market scandal, or a regulatory mood shift does not instantly become a banking freeze.

    In practice, the jurisdictions most aligned with “no sudden surprises” tend to be those with:

    * mature regulatory institutions,
    * clear licensing regimes,
    * strong legal systems,
    * and predictable political continuity.

    In the article’s positioning, that points you toward places like Singapore, UAE (Dubai), and much of core Western Europe. Even then, “banks won’t close accounts” is never a promise. Banks can react to risk teams, correspondent banking pressure, and reputational events. Your job is to minimize the probability of being treated as an exception by staying compliant, documenting source-of-funds carefully, and avoiding jurisdictions where rules exist mainly as rumor.


    If I want EU residency and hold crypto, where should I go?

    If your goal is EU residency with a credible long-term pathway, you want:

    * a residency route that survives renewals,
    * a legal environment that does not punish you retroactively,
    * and enough administrative capacity to process applications without chaos.

    In our article, Portugal remains the clearest “EU base” because the residency logic is legible and the broader EU framework tends to support rule persistence. The important nuance is that Portugal is not “the zero-tax crypto paradise” many people still imagine. The 2023 shift that introduced taxation on short-term gains is exactly the kind of reality correction serious settlers should expect. It does not make Portugal unusable. It makes it more normal, and normal is often what long-term life requires.

    If you want EU residency, treat crypto as wealth you must document, not magic money that bypasses paperwork. Your success tends to depend less on the country’s slogans and more on your ability to show clean provenance and stable life infrastructure.


    What’s the best place to live with crypto income in 2026?


    “Crypto income” is a loaded term. Countries and banks often distinguish between:

    * investment gains,
    * trading activity,
    * business revenue paid in crypto,
    * and salary-like payments converted from crypto.

    The “best” place depends on what your cashflow actually looks like and how you plan to prove it.

    From the article’s perspective:

    * If you want institutional clarity and defensibility, Singapore is often strongest, but it is strict and not cheap.
    * If you want a high-continuity operating base where policy is less likely to swing with elections, UAE is a strong candidate once you set up residency and banking properly.
    * If you want long-term life plus an EU trajectory, Portugal can still work, but you should assume future adjustments are possible and plan accordingly.

    Market instability matters here because crypto income can be volatile, and volatility looks like risk to immigration officers and banks. Settling long-term generally requires you to demonstrate stability even when your portfolio is unstable. That often means maintaining fiat buffers and documentation systems that do not depend on a bull market.


    Which crypto-friendly countries have stable governments?

    “Stable government” is not the same as “friendly laws.” You want stability in the sense that rules change slowly and are telegraphed, not reversed overnight.

    In the article’s worldview:

    * Singapore is a high-stability jurisdiction with strong institutions.
    * UAE offers policy continuity through a different model, with fewer electoral swings.
    * Much of core Western Europe offers institutional stability within the EU framework, though policy can still shift, especially around tax.

    Stability is also about how governments respond to stress. In a market scandal or a major enforcement event, some places clarify, others overreact. Our Index tries to measure that tendency indirectly through Rule Persistence.


    Where should I live long-term with crypto?

    The pragmatic answer is: do not design your life around a single jurisdiction if your net worth is concentrated in a volatile asset class. Use the bands. Build a base where:

    * Residency is realistic,
    * Banking is workable,
    * and the rules are hard to reverse.

    Then, add one additional base that provides either:

    * time-zone coverage,
    * tax clarity,
    * or lifestyle affordability.

    In our article, a common rational mix is Portugal + UAE + Panama, but the best answer is the one that fits your citizenship, risk tolerance, and how you intend to document funds.


    Which countries are safest for crypto investors

    If you mean “safest” in the broad sense, include:

    * physical safety,
    * legal predictability,
    * banking behavior,
    * and reputational risk.

    The safest jurisdictions for investors tend to be those with strong institutions and clear compliance expectations. In our framing, Singapore is a prime example: strict, consistent, and defensible. Many parts of Western Europe also fit this “predictable institutions” model.

    A key warning: some countries feel safe because they are lax. That is not safety, that is temporary neglect. When enforcement arrives, it arrives fast, and investors discover they were living in a policy gap, not a stable regime.


    Best crypto countries for residency

    “Best” depends on what you value: speed, permanence, cost, or defensibility.

    Our article’s bias is toward settlement, not tourism. That means:

    * If you want an EU track and a real long-term plan: Portugal stays near the top.
    * If you want operational clarity and high continuity once established: UAE is a strong contender.
    * If you want the most institutionally defensible environment: Singapore.
    * If you want low-friction testing and optionality: Georgia.
    * If you want Americas time-zone stability with practical pathways: Panama.

    The market risk is always present: if you choose a residency path that requires stable income or large capital thresholds, a drawdown can turn a plan into a scramble. Build around that reality.


    Will Portugal change crypto tax again?

    We cannot be certain, and anyone who speaks with certainty here is selling comfort.

    Portugal has already demonstrated that policy can change as adoption and attention increase. The 2023 shift that introduced taxation on short-term gains is a real example of how “crypto reputations” evolve into ordinary tax frameworks once a jurisdiction matures and political incentives shift.

    The correct way to plan is not to assume Portugal will stay the same. Assume instead:
    * Rules will keep evolving,
    * Enforcement will likely become more consistent,
    * And documentation expectations will rise.

    Portugal remains valuable because changes tend to be legislated, not impulsive, and because the broader EU environment generally supports rule predictability. But if your entire plan depends on one favorable interpretation lasting forever, it is not a plan. It is a wager.


    Is Dubai safe for crypto long term?


    Dubai can be very safe in the physical sense, and the UAE’s policy continuity is often strong. That is why it performs well in our Index logic. The long-term risks are not typically street-level risks. They tend to be:

    * compliance and banking expectations tightening,
    * the burden of proof around source-of-funds,
    * and the practical requirement to run your life through systems that expect documentation.

    Dubai is often excellent for long-term crypto holders who are willing to be “boringly compliant.” It is less forgiving for those who treat banking as an afterthought or assume crypto wealth exempts them from scrutiny.

    Market instability matters because in a major downturn, jurisdictions that are courting capital can still tighten controls on flows to protect reputational and systemic risk. The advantage in Dubai is that change is often structured and telegraphed rather than chaotic.


    Can I really bank with crypto in Singapore?


    You can often bank in Singapore if you are prepared for a high-compliance environment. Singapore tends to be consistent: it does not reward improvisation, but it does reward clarity.

    The realistic answer is:

    * If your source-of-funds is clean, documented, and explainable,
    * And your activity profile does not look like unmanaged risk,
    * Then Singapore can be one of the most defensible places to build long-term.

    If your records are poor, if your inflows are irregular, or if your story changes depending on who asks, Singapore becomes difficult quickly. That is not hostility. It is institutional risk control.

    In volatile markets, this matters even more. When the market turns, compliance teams become conservative everywhere. Singapore is one of the jurisdictions where you can predict that behavior in advance, which is part of why it scores well in “Rule Persistence.”


    Sources and data links


    Core safety and governance
    Global Peace Index (Institute for Economics & Peace)
    Institute for Economics & Peace (methodology and datasets)

    English proficiency
    EF English Proficiency Index (EF EPI)

    Global compliance baseline for crypto rails
    Financial Action Task Force (FATF) – Virtual Assets and VASP guidance

    European Union regulatory framework
    Markets in Crypto-Assets Regulation (MiCA), Regulation (EU) 2023/1114

    United Arab Emirates and Dubai virtual asset regulation
    Dubai Virtual Assets Regulatory Authority (VARA)

    Thailand long-stay and digital nomad visa references
    Thai Embassy – Destination Thailand Visa (DTV) overview
    BDO Thailand – DTV regulatory and Gazette reference (PDF)

    Payments, wallets, and card infrastructure
    MetaMask – official product and disclosures:
    Visa – digital currency and settlement initiatives

    General crypto risk, governance, and standards context
    VaaSBlock – blockchain credibility, risk assessment, and governance research

    Supplementary public reporting and analysis Major financial press, regulator releases, and licensed exchange disclosures (including central bank publications, immigration authorities, and compliance guidance referenced throughout the article)

  • Moving Abroad: A Research-Based Relocation Guide

    Moving Abroad: A Research-Based Relocation Guide

    A Data-Driven Approach to Relocating Successfully

    Moving house is one of life’s most significant transitions, ranking alongside marriage, divorce, and career changes in terms of psychological impact. Yet although moving profoundly affects mental health, relationships, and financial stability, most people prepare too little and expect too much.

    Packing boxes with dividers beside a clipboard checklist, tape and bubble wrap, showing how careful preparation eases a move

    The Hidden Complexity of Modern Moving

    U.S. Census Bureau data has tracked a multi-decade decline in the share of Americans who move each year, down from roughly one in five during the 1960s to a series of record lows since. That decline isn’t only about satisfaction with current housing: it reflects growing economic constraints, housing affordability pressure, and the psychological barriers that make moving increasingly daunting.

    Moving carries real emotional weight: anxiety, sadness, disrupted sleep. None of it is imagined weakness.

    Understanding the True Timeline: Why Most People Underestimate Moving

    The most common mistake in moving is underestimating the timeline. Moving-industry guidance typically calls for starting preparations about eight weeks out, extending to twelve for complex long-distance moves, yet most people allocate only 2-4 weeks. That compression sets off cascading failures that compound stress and costs.

    The Science of Moving Timelines

    Professional moving companies report these average time requirements:

    • Studio apartment: 2-3 hours with professional movers
    • 1-bedroom home: 2-4 hours with 2 movers
    • 2-bedroom home: 3-6 hours with proper preparation
    • 3-bedroom home: 5-8 hours, often requiring 4+ movers
    • 4+ bedroom homes: 8-12 hours, frequently spanning multiple days

    However, these figures cover only the physical moving day.

    The 7-Week Minimum Preparation Window

    This guide uses seven weeks as the minimum preparation window, accounting for:

    Weeks 7-6: Logistics and decluttering

    • Booking moving companies (optimal availability requires 2-3 weeks’ advance booking)
    • Beginning decluttering processes
    • Starting packing of non-essential items
    • Researching new communities and services

    Let Swift Cargo Solutions handle your Door-to-Door move.

    Weeks 5-4: Administrative tasks

    • Address changes with essential services
    • Utility transfers and scheduling
    • School record transfers for children
    • Medical record coordination

    Weeks 3-2: Final preparations

    • Packing majority of belongings
    • Appliance preparations
    • Travel arrangements
    • Final decluttering

    Week 1: Completion

    • Essential packing completion
    • Cleaning and preparation
    • Final walkthroughs and documentation

    The Psychology of Moving: Understanding Emotional Impact

    A mother, father and two children silhouetted at a window at sunset, showing how a move touches every member of a family

    Research from socio-ecological psychology demonstrates that residential mobility affects self-concept, social relationships, and long-term well-being.

    Childhood Mobility: Long-term Consequences

    A University of Virginia study following 7,108 American adults over 10 years found lasting effects from frequent childhood moves:

    • Introverted children who moved frequently showed substantially higher mortality risk by the 10-year follow-up
    • Extraverted children showed no negative health effects from frequent moves
    • Frequent movers (3 or more childhood moves) showed sharply higher rates of behavioral problems than children who never moved, per a separate 1994 study of over 10,000 school-age children
    • Educational impact: each school change is associated with a 0.02 GPA-point drop in the year of the change

    Adult Moving Stress: The Physiological Reality

    Moving triggers measurable stress responses:

    • Cortisol levels spike during moving transitions
    • Sleep disruption is common in the days immediately before and after a move
    • Immune function temporarily decreases, increasing illness susceptibility
    • Cognitive performance temporarily declines due to stress and sleep disruption

    Financial Reality: The True Cost of Moving

    Moving expenses consistently exceed expectations. Moving and storage generated $32.2 billion in direct U.S. economic activity in 2021 (rising to $92.2 billion once indirect and induced effects are counted).

    Cost Breakdown by Move Type

    Local moves (under 50 miles):

    • Professional movers: $301-$3,512 depending on home size
    • Hourly rates: $65-$251 per hour for professional crews
    • DIY moves: $150-$600 including truck rental and supplies

    Long-distance moves (over 50 miles):

    • Professional services: $2,509-$11,641 based on weight and distance
    • Average household goods: 1,000-1,500 pounds per furnished room

    Hidden Costs That Destroy Budgets

    Commonly overlooked expenses:

    • Utility connection fees: $50-$200 per service
    • Cleaning services: $150-$500 for move-out cleaning
    • Storage units: $60-$300 monthly for temporary storage
    • Eating out during transition: $200-$500 for 2-week period
    • Replacement items: $300-$1,000 for items damaged or discarded
    • Address change fees: $25-$75 for various services
    • Pet boarding: $25-$50 daily during moving chaos

    Common Moving Mistakes: Data-Driven Analysis

    1. Timeline Compression

    The mistake: Allocating insufficient preparation time. The cost: higher stress and higher expenses, driven by rush fees and last-minute decisions. The solution: Begin planning minimum 7 weeks in advance.

    2. Decluttering Failure

    The mistake: Moving unnecessary items. The cost: higher moving expenses and continued clutter in the new home. The solution: Implement systematic decluttering 6 weeks before moving.

    3. Documentation Neglect

    The mistake: Inadequate record-keeping and inventory. The cost: Insurance claim denials, lost items, disputes with movers. The solution: Photograph and inventory all items before packing.

    Photograph each item the moment it comes off the shelf, before it goes in a box, so the record-keeping step happens inside a motion you’re already making rather than as a separate task competing for attention on packing day.

    4. Utility Coordination Errors

    The mistake: Poor utility transfer timing. The cost: Service gaps, reconnection fees, temporary housing costs. The solution: Schedule utility transfers 4 weeks in advance.

    5. Emotional Underestimation

    The mistake: Ignoring psychological preparation. The cost: Family stress, relationship strain, mental health impact. The solution: Acknowledge emotional aspects and plan support strategies.

    A bedroom full of taped boxes with a stuffed rabbit and toy car on top, showing how a move touches children

    The Children’s Factor: Special Considerations for Families

    Moving affects children disproportionately.

    Developmental Impact by Age

    Infants and toddlers (0-3 years): Minimal long-term impact but require routine maintenance. Preschoolers (3-5 years): May show regression, clinginess, sleep disruption. School-age children (6-12 years): Friendship-loss anxiety, academic adjustment concerns. Adolescents (13-18 years): Highest risk group for negative outcomes including academic decline, social anxiety, and behavioral issues.

    Risk Factors for Negative Outcomes

    Research identifies these factors as increasing children’s moving difficulties:

    • Frequent moves (3+ within few years)
    • Mid-year school changes
    • Moves triggered by instability (divorce, job loss, eviction)
    • Drastically different environments (urban to rural, different cultures)
    • Moves during sensitive developmental phases (early adolescence particularly risky)

    Protective Strategies

    Successful family moves incorporate:

    • Early communication: Age-appropriate discussions about changes
    • Involvement in decisions: Allowing children choices in new home elements
    • Routine maintenance: Keeping familiar traditions and schedules
    • School coordination: Working with both old and new schools for smooth transitions
    • Social support: Facilitating both maintaining old friendships and creating new ones

    The Complete Moving Timeline: A Research-Based Approach

    Phase 1: Foundation (8-7 Weeks Before)

    Week 8: Decision and initial planning

    • Confirm moving date and destination
    • Research moving companies and get quotes
    • Begin neighborhood research for new area
    • Create moving budget and tracking system
    • Notify landlord if renting (typically 30-60 days required)

    Week 7: Logistics locking

    • Book a moving company (optimal availability window)
    • Begin systematic decluttering process
    • Start address change list (typically 25+ organizations require notification)
    • Research schools, healthcare providers, and essential services in new area
    • Begin packing non-essential items

    Phase 2: Preparation (6-4 Weeks Before)

    Week 6: Decluttering and early packing

    • Complete major decluttering (aim for 20-30% reduction in belongings)
    • Pack seasonal items and rarely-used possessions
    • Arrange donation pickups or sales for unwanted items
    • Begin consuming pantry and freezer items
    • Research utility companies and service providers

    Week 5: Administrative tasks

    • Submit official address changes (USPS, banks, insurance, employers)
    • Schedule utility disconnections and connections
    • Arrange school record transfers
    • Notify healthcare providers and arrange record transfers
    • Update subscriptions and membership services

    Week 4: Final logistics

    • Confirm moving company details and requirements
    • Arrange parking permits if needed
    • Schedule time off work for moving process
    • Plan travel arrangements if long-distance
    • Begin packing majority of belongings

    Phase 3: Execution (3-1 Weeks Before)

    Week 3: Intensive preparation

    • Pack majority of non-daily items
    • Prepare appliances for moving
    • Arrange pet care or boarding if needed
    • Confirm utility connections
    • Create “first night” essentials box

    Week 2: Final preparations

    • Complete packing except daily essentials
    • Arrange cleaning services or schedule move-out cleaning
    • Confirm moving day details with all parties
    • Prepare important documents for transport
    • Plan meals to minimize kitchen use

    Week 1: Completion

    • Finish final packing
    • Complete cleaning tasks
    • Conduct final walkthrough of old home
    • Confirm utility activation at new home
    • Prepare for moving day logistics

    Phase 4: Transition (Moving Week)

    Moving Day: Execution

    • Supervise loading process
    • Complete final walkthrough and documentation
    • Transport valuables personally
    • Direct unloading at new home
    • Basic unpacking of essentials

    Week 1 Post-Move: Stabilization

    • Unpack priority areas (bedrooms, bathrooms, kitchen)
    • Set up essential services
    • Explore neighborhood and locate essential services
    • Begin establishing new routines
    • Address immediate maintenance needs

    Weeks 2-4 Post-Move: Integration

    • Complete unpacking and organization
    • Update remaining address information
    • Register with new healthcare providers
    • Establish community connections
    • Evaluate and adjust routines

    Stress Management Strategies: Evidence-Based Approaches

    Strategies by stage:

    Pre-Move Stress Prevention

    Mindfulness practices: a short daily meditation practice in the weeks before a move can blunt the stress response

    Physical preparation: Maintaining exercise routines during moving preparation reduces cortisol levels and improves sleep quality

    Social support: Maintaining connections with friends and family throughout the moving process provides emotional buffering

    A couple practicing yoga to manage the stress of relocating abroad

    During-Move Coping Strategies

    Break scheduling: regular short breaks during physically demanding moving-day work reduce both injury risk and fatigue-driven stress

    Hydration and nutrition: Proper physical care maintains energy levels and emotional stability during intensive moving periods

    Task delegation: Accepting help from others reduces stress and creates positive social connections

    Post-Move Adaptation

    Routine establishment: Creating new routines within the first week accelerates adaptation and reduces relocation stress syndrome

    Community engagement: joining local groups soon after a move is one of the more reliable ways to speed up long-term satisfaction with the new place

    Professional support: Online therapy platforms provide continuity of care during transitions

    Special Populations: Customized Approaches

    Senior Citizens: Relocation Stress Syndrome

    Older adults face unique challenges including relocation stress syndrome, a recognized nursing diagnosis characterized by anxiety, confusion, and loneliness. Strategies include:

    • Familiar item prioritization: Keeping cherished possessions visible
    • Routine maintenance: Maintaining established daily patterns
    • Healthcare continuity: Ensuring seamless medical care transitions
    • Social connection: Facilitating contact with existing support networks

    Military Families: Frequent Relocation Adaptation

    Military families typically relocate every two to four years under permanent-change-of-station orders:

    • Systematic approaches: Standardized checklists and procedures
    • Community utilization: Immediate engagement with military support networks
    • Child resilience building: Age-appropriate involvement in moving process
    • Resource maximization: Full utilization of available military moving resources

    International Relocations: Cultural Adaptation

    International moves (whether a corporate posting or a full relocation to a destination like Thailand) add cultural adaptation challenges:

    • Language preparation: Early language learning for destination countries
    • Cultural research: Understanding social norms and expectations
    • Documentation preparation: Ensuring all legal requirements are met
    • Support network creation: Connecting with expatriate communities

    The seven-week minimum above assumes a domestic move; international sea freight adds weeks of its own, and an early estimate on volume and dates shows how many.

    Technology Integration: Modern Moving Tools

    Useful digital tools:

    Planning and Organization Apps

    • Moving checklist applications: Structured task management
    • Inventory tracking systems: Photographic documentation and categorization
    • Budget tracking tools: Real-time expense monitoring
    • Timeline management: Automated deadline reminders

    Service Connection Platforms

    • Utility connection services: One-stop utility setup
    • Address change services: Automated notification systems
    • Service provider matching: Vetted local service recommendations
    • Community connection platforms: Neighborhood social networks

    For people who built a life abroad that worked, the job that mattered most was rarely the job they moved for. The friendships that lasted were rarely the ones they expected to form. The country they ended up loving was sometimes the third country they tried, not the first.


    Related reading: Moving to Thailand Checklist: The Operational Version


    Sources: